Best Whole Life Insurance Companies in 2026: 8 Services Compared

Financial strength and blended cover · Starting price: See website
How we put this together: we compare official feature and pricing pages, app store listings, privacy policies and public user reviews. Prices change, so check the provider's site before you pay.
Key takeaways
- Northwestern Mutual, New York Life, MassMutual and Guardian lead on financial strength and participating whole life policies.
- Dividends are a possible benefit of participating policies, but they are never guaranteed and vary year to year.
- Whole life premiums are much higher than term life for the same death benefit, so affordability over decades matters more than the first quote.
- Penn Mutual and State Farm suit buyers who want flexible policy design or an agent-led purchase alongside other cover.
Quick comparison
| Name | Who it suits | Starting price | Free option | |
|---|---|---|---|---|
| Northwestern Mutual | Financial strength and blended cover | See website | No | Visit |
 New York Life | Customisation and legacy planning | See website | No | Visit |
 MassMutual | Participating policies and cash value | See website | No | Visit |
 Guardian | Flexible policy structures | See website | No | Visit |
 Penn Mutual | Early cash value and design flexibility | See website | No | Visit |
 State Farm | Agent-led buying and bundling | See website | No | Visit |
 Nationwide | Broad product range | See website | No | Visit |
 Mutual of Omaha | No-exam whole life options | See website | No | Visit |
The best whole life insurance companies
Whole life insurance covers you for life, with level premiums and a cash value that grows under the policy contract. That permanence comes at a price: premiums are far higher than term life for the same death benefit. We compared official product pages, financial strength information, dividend history, rider options and public reviews to build this list.
Northwestern Mutual is the largest life insurer in the United States by market share in recent industry data, and its whole life policies are participating, meaning eligible policyholders may receive dividends when the company performs well. Dividends are not guaranteed, but Northwestern Mutual has a long record of paying them, which matters to buyers who value cash value growth over decades.
The company also offers blended policies that combine whole life with term cover, which can raise the death benefit for a lower total premium than whole life alone. Buying is agent-led, so expect a planning conversation rather than an online checkout. If financial strength and long-term cash value are your priorities, Northwestern Mutual is a natural first quote.
- Very strong financial ratings
- Participating policies with dividend history
- Blended term and whole life options
- Agent-led purchase
- Premiums are high, as with all whole life
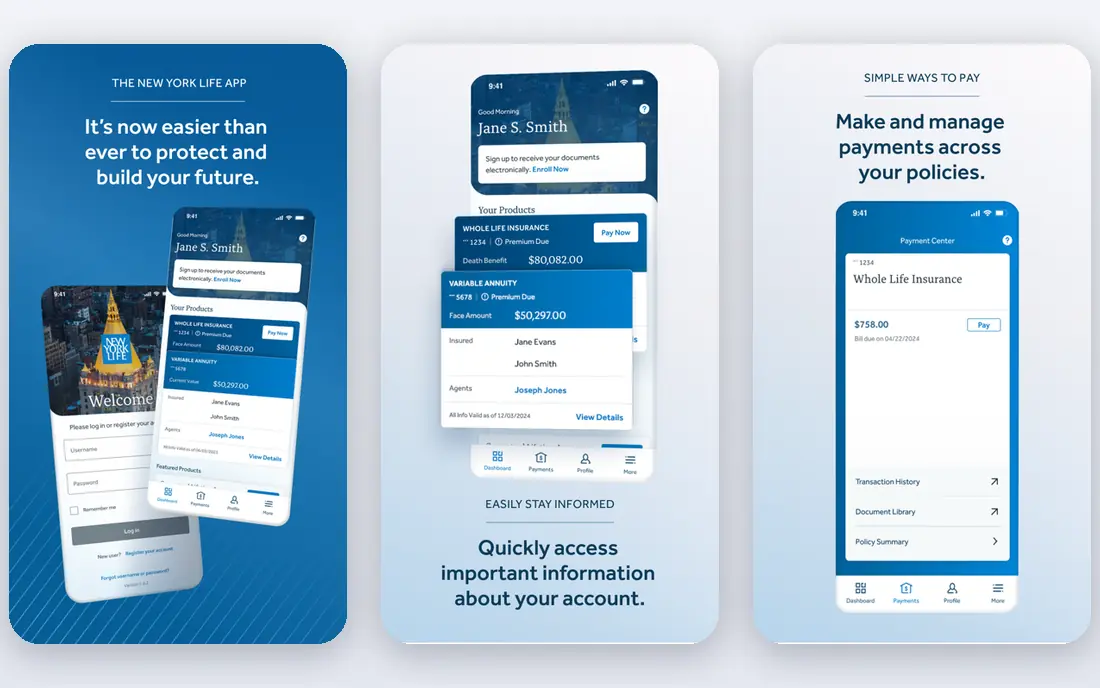
New York Life is the largest mutual life insurer in the United States, and its whole life policies suit buyers who want to shape cover around a plan. Payment options include level premiums and limited-pay structures, where premiums are paid over a set number of years rather than for life. Riders can add cover for disability, long-term care needs or additional insured family members, subject to underwriting.
The trade-off is process. Whole life from New York Life is bought through an agent, not online, and the illustration you receive will show guaranteed and non-guaranteed values side by side. Read both columns, since only the guaranteed column is promised. For legacy planning and custom policy design, New York Life is a strong choice.
- Large mutual insurer with long dividend history
- Flexible payment schedules and riders
- Strong agent network
- No online purchase for whole life
- Quotes need an agent conversation
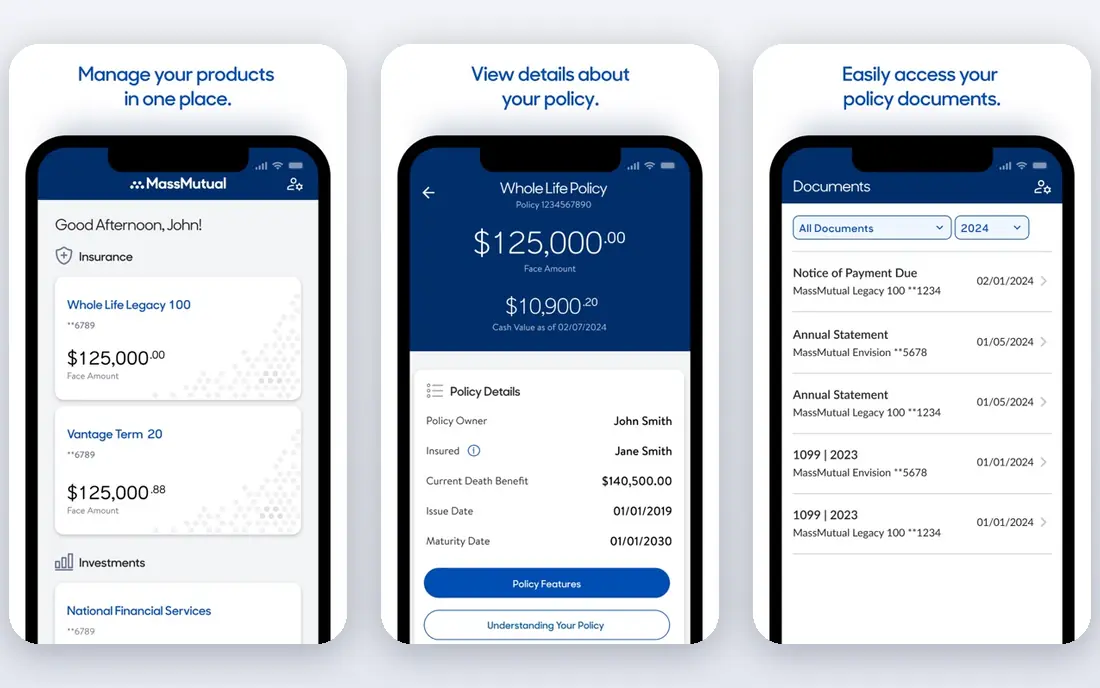
MassMutual, formally Massachusetts Mutual Life Insurance Company, is frequently cited in comparisons for cash value growth in its participating whole life policies. Policyholders may receive dividends, which can be taken as cash, used to reduce premiums, left to earn interest, or used to buy additional paid-up cover. That flexibility lets the policy adapt as your needs change.
MassMutual also offers a broad rider range and underwriting options that suit younger families planning decades ahead. As with every whole life policy, the premium commitment is the real test: a policy that lapses early delivers poor value, so buy a death benefit you can sustain. If cash value growth is a priority, MassMutual belongs on the shortlist.
- Participating whole life with strong dividend record
- High cash value growth potential in comparisons
- Broad rider range
- Agent-led purchase
- Whole life premiums need a long-term budget
Guardian stands out for the breadth of its whole life lineup, with level-premium and limited-pay structures and a range of riders. It is also noted in comparisons for offering cover to applicants with some health conditions, including policies for people living with HIV, which few competitors match. Financial strength ratings are among the highest in the industry.
The honest catch is transparency online. Guardian publishes less policy detail on its website than some rivals, so the useful comparison happens with an agent and a full illustration. Dividends, where applicable, are not guaranteed. If you want flexible structures or have a health history that other insurers treat harshly, Guardian is worth a conversation.
- Range of whole life products, including level-premium and limited-pay options
- Strong financial ratings
- Cover for some health conditions
- Policy details are limited online
- Purchase needs an agent
Penn Mutual is a mutual insurer whose whole life policies appeal to buyers focused on policy design. Paid-up additions, which use dividends or extra premiums to buy small chunks of additional paid-up cover, are a core feature, and comparisons often cite Penn Mutual for early cash value growth. That suits buyers who want the cash value to build sooner rather than later.
The trade-off is distribution. Penn Mutual sells through independent advisers and a smaller network than Northwestern Mutual or New York Life, so finding an adviser may take more effort. It is also less well known, which matters little for policy value but can matter for comfort. If design flexibility and early cash value appeal to you, Penn Mutual deserves a quote.
- Flexible whole life design
- Strong paid-up additions options
- Competitive early cash value in comparisons
- Smaller agent network than the largest mutuals
- Less name recognition
State Farm sells whole life insurance alongside its better-known home and auto cover, which suits buyers who prefer one company and one agent for several policies. Its whole life policies offer lifelong cover with cash value growth, level premiums and standard riders, without the more complex design options of the specialist mutuals.
That simplicity is both the strength and the limit. State Farm is easier to buy from if you already have an agent relationship, but buyers focused on dividend performance or advanced paid-up additions design will find the mutual leaders stronger. If convenience and a trusted local agent matter most, State Farm is a sensible whole life quote.
- Large local agent network
- Whole life alongside home and auto cover
- Straightforward policy options
- Less whole life specialisation than the mutual leaders
- Fewer advanced design options
Nationwide offers whole life as part of a broad life insurance range that also includes term, universal and variable universal life. That breadth helps buyers who are unsure whether whole life is right, since an adviser can compare permanent and term options in one conversation. Online tools give initial quotes for some products, although permanent policies usually need an adviser to complete.
The catch is focus. Nationwide is a strong general insurer, but whole life specialists such as MassMutual and Guardian offer deeper participating policy design. If you want to compare whole life against other permanent options, or you already hold Nationwide policies, it is a useful quote. If whole life is already decided, the mutual leaders lead.
- Whole life, universal life and term under one company
- Online quote tools for some products
- Broad agent network
- Whole life is not its standout product
- Online detail for permanent policies is limited
Mutual of Omaha suits a different buyer from the rest of this list: older applicants, or people who want whole life without a medical exam. Its guaranteed acceptance whole life policies are available to applicants aged 45 to 85 up to $25,000 of cover in published materials, with no health questions and no exam. That access matters for people who might otherwise struggle to get cover.
The limits are amount and price. Guaranteed acceptance cover is modest, and no-exam premiums reflect the higher risk the insurer takes. This is not the policy for a young family needing a large death benefit, where fully underwritten whole life from a mutual leader gives far better value. For final-expense needs or older applicants, Mutual of Omaha fills a real gap.
- Guaranteed acceptance whole life for older applicants
- No-exam options up to set limits
- Long company history
- Guaranteed acceptance cover amounts are modest
- Premiums are higher for no-exam cover
How we picked these
We compared official product pages, financial strength ratings, dividend histories, rider options and public reviews for insurers that sell whole life cover in the United States. We favoured mutual insurers with participating policies and strong ratings, plus companies that fill specific needs such as no-exam cover or agent-led bundling. We did not rank on sample premiums, because whole life pricing depends heavily on age, health, death benefit, payment structure and riders.
Whole life versus term life, honestly
Term life buys a large death benefit for a set period at a much lower premium, which suits income replacement while raising children or paying a mortgage. Whole life buys lifelong cover with cash value, but at a far higher premium for the same death benefit. Many families do best with term cover for the large need and a smaller whole life policy for permanent needs, such as final expenses or legacy goals.
How to read an illustration
An illustration shows guaranteed values, which the contract promises, and non-guaranteed values, which assume dividends or interest that may not occur. Judge the policy on the guaranteed column first, and treat anything above it as a possible bonus. Also check the premium payment period, surrender charges in early years, and what happens if you stop paying.
Questions to ask an agent
Ask whether the policy is participating, how dividends have performed over the past 20 years, and what riders are included versus added at extra cost. Ask about paid-up additions, loan provisions and the effect of loans on the death benefit and cash value. A good agent will walk through the guaranteed column without rushing past it.
Please note: this article is general information, not insurance or financial advice. Rates and policy features depend on individual circumstances and location, including age, health, state, death benefit and policy design. Dividends are not guaranteed. Compare full illustrations from at least two insurers before buying.
Frequently asked questions
What is whole life insurance?
Whole life insurance is permanent cover that lasts for life as long as premiums are paid, with level premiums and a cash value that grows under the policy contract. The death benefit is paid to beneficiaries when the insured person dies, whenever that happens. Cash value can be borrowed against or withdrawn, although both reduce the death benefit if not repaid.
Is whole life insurance worth it?
Whole life is worth it for people who need lifelong cover, want cash value features, or have estate planning needs, and who can afford the higher premiums for decades. It is poor value if the premium strains your budget, since a lapsed policy delivers little. Most families needing large income replacement cover get better value from term life.
Do whole life policies pay dividends?
Participating whole life policies from mutual insurers may pay dividends when the company performs well, but dividends are never guaranteed. They can be taken as cash, used to reduce premiums, left to earn interest, or used to buy additional paid-up cover. Non-participating policies do not pay dividends.
How much does whole life insurance cost?
Whole life premiums are typically several times higher than term life for the same death benefit, and the exact price depends on age, health, death benefit, payment structure and riders. Insurers rarely publish whole life prices online, because underwriting and policy design change the figure so much. Get full illustrations from at least two insurers for a real comparison.
Can I buy whole life insurance online?
Some insurers offer online quotes for term life and simpler products, but whole life usually needs an agent conversation, because policy design, riders and illustrations affect long-term value. An agent can also compare participating and non-participating options and explain the guaranteed column of the illustration.
What happens if I stop paying whole life premiums?
If you stop paying, the policy may lapse, although many policies offer a grace period and options such as reduced paid-up cover or extended term cover using the cash value. The exact options depend on the contract and how much cash value has built up. Ask your agent about these options before you buy, not after a missed payment.
Sources we checked (8)

Online Jobs is an independent blog about careers, online work, learning new skills and the tools that help people earn. More about us.
Keep reading
All posts
Best Trading Apps for Beginners
Compare the best trading app for beginners, with $0 stock commissions, fractional shares, education, paper trading and account types explained in 2026 now.
Best Trading App
We compared the best trading apps for beginners and active traders on fees, tools, accounts and ease of use, so you can pick a platform that fits your plan.
Best Tax Software
Compare the best tax software in 2026 for simple returns, investors, freelancers, and preparers, with free options, state fees, and honest limits for filing.