Best Renters Insurance Companies in 2026: 8 Companies Compared

How we put this together: we compare official feature and pricing pages, app store listings, privacy policies and public user reviews. Prices change, so check the provider's site before you pay.
Key takeaways
- Lemonade and Allstate both advertise renters policies starting at $5 per month, though your actual quote depends on where you live and how much coverage you choose.
- Your landlord's policy covers the building, not your belongings, so a renters policy is what protects your furniture, electronics and clothes.
- USAA is a strong option for military families, but membership is limited to eligible service members, veterans and their families.
- Get quotes from at least three companies with the same coverage limits and deductible, since that is the only fair way to compare prices.
- Flood and earthquake damage are usually not covered by a standard renters policy, so ask about separate coverage if you live in an area where those risks matter.
Quick comparison
| Name | Who it suits | Starting price | Free option | |
|---|---|---|---|---|
 Lemonade | Fast digital quotes and claims | $5 per month | No | Visit |
 State Farm | Local agent support | See website | No | Visit |
 Allstate | Low starting price with agent access | $5 per month | No | Visit |
 USAA | Military families | See website | No | Visit |
 Progressive | Bundling with auto insurance | See website | No | Visit |
 GEICO | Existing GEICO customers | See website | No | Visit |
 Liberty Mutual | Customizable coverage | See website | No | Visit |
 Nationwide | Broad coverage options | See website | No | Visit |
The best renters insurance companies
Renters insurance is one of the cheapest policies you can buy, and it covers far more than most renters expect. We compared the companies below on price, coverage, claims handling and service, using their official pricing and coverage pages and public reviews. This is general information, not financial advice, and your quote will depend on your address, coverage limits and deductible.
Lemonade is our pick for renters who want to get covered quickly without phone calls or paperwork. You can get a quote, adjust your personal property and liability limits, and see the monthly price change as you go, all online or in the app. The company says straightforward claims can be handled in minutes through the app, which is a real advantage when you are dealing with a theft or a burst pipe.
The catch is the service model. If you like sitting down with a local agent to talk through your coverage, Lemonade does not offer that. Its renters policies start at $5 per month on the company's own site, with a basic policy that includes $10,000 of personal property coverage, but most renters will pay more once they raise their limits to match what they actually own. Check the availability in your state before you set your heart on it, and add extra coverage for high-value items like jewelry or fine art, which have their own limits under the base policy.
- Very low advertised starting price
- Fully digital quote and claims process
- Replacement cost coverage for belongings
- No local agent network
- Availability varies by state
- Standard policies do not cover flood or earthquake damage
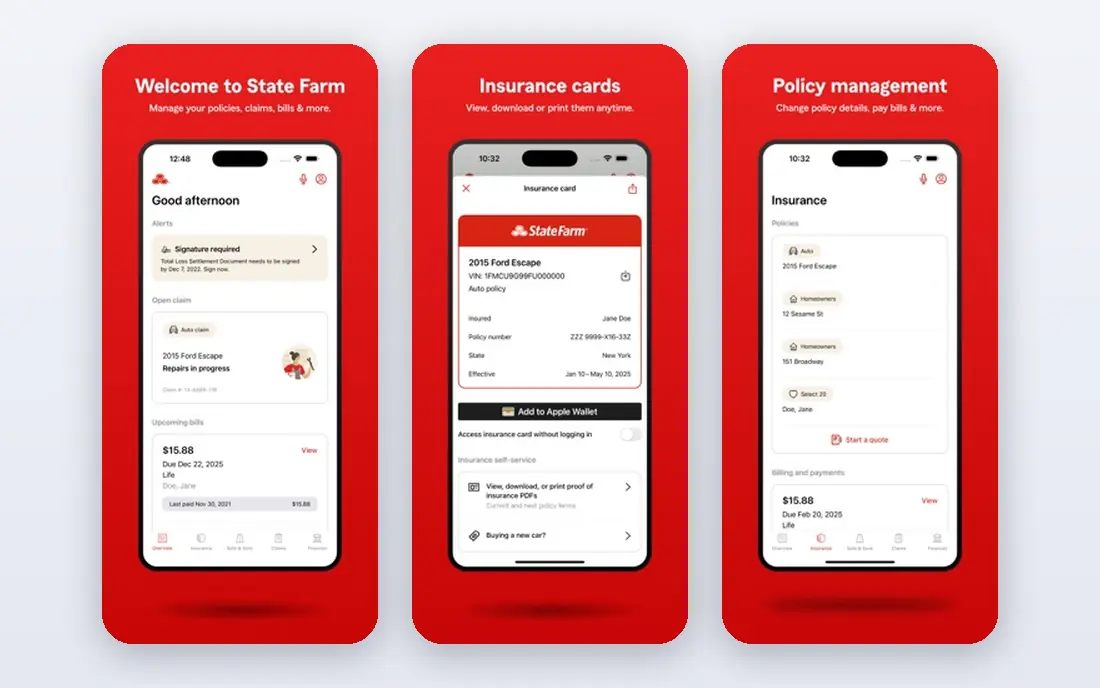
State Farm is the pick for renters who want a person, not just an app, behind their policy. With agents in most towns across the country, you can get help choosing limits, filing a claim and updating your policy when you move. The company says bundling renters and auto insurance could save customers up to $900 a year on average, based on its own survey of new policyholders, which makes it worth pricing if you already drive.
The trade-off is that State Farm does not publish one starting price, so you need a quote to know what you would pay. Its renters page cites a national survey putting average renters coverage at about $13 a month for roughly $34,000 in coverage limits, but your own price will move with your location, deductible and coverage choices. Like most standard policies, it does not cover flood damage, and high-value items may need a separate personal articles policy for full protection.
- Large network of local agents
- Strong bundling discounts with auto insurance
- Inflation coverage that raises limits over time
- No single published starting price
- Quotes and service can vary by agent
- Flood insurance is not offered
Allstate gives you two things that rarely come together: a very low advertised starting price and a nationwide agent network. Its renters page says coverage is available in all 50 states, with policies starting at $5 per month, and you can customize personal property, family liability, guest medical and temporary housing coverage. If you already have Allstate auto insurance, bundling the two is a simple way to cut the bill a little further.
The honest catch is that $5 per month is a starting point, not a promise. Location, the value of your belongings and your deductible all push the price up, and Allstate's own bundle example puts the renters saving at up to 5 percent on the two policies combined. Still, for renters who want a household name, an app for managing the policy and an agent to call when something goes wrong, Allstate is a solid middle ground between digital-only carriers and smaller regional insurers.
- Policies advertised from $5 per month
- Available in all 50 states
- Online quotes plus local agents
- Your actual premium may be well above the advertised starting price
- Bundling savings are modest compared with some rivals
USAA is the company military renters ask about first, and for good reason. Its policies are built around moves, deployments and life on and off base, and its personal property coverage can follow you around the world rather than stopping at your apartment door. Members can manage policies, claims and banking in one place, which matters when you move every few years and need to update an address quickly.
The limit is eligibility. If you are not a current or former service member, or an eligible family member, you cannot buy a USAA policy at all. For everyone else, this entry is simply not available, so treat it as a strong option only if you qualify. Eligible renters should still compare a USAA quote with one or two civilian carriers, since prices vary by location and coverage choices even within USAA's membership.
- Coverage built for military life, including worldwide personal property coverage
- Strong reputation for service
- Bundling with other USAA products
- Membership is limited to eligible military members, veterans and family
- Not an option for civilian renters
Progressive makes the most sense if you already insure a car with the company. Adding renters coverage to an existing auto policy is a quick quote, and bundling is where most of the savings come from. The online quote flow lets you compare coverage options without an agent visit, and you can manage the policy and file claims through the company's website and app.
One thing to check is who actually underwrites your policy. In some states, Progressive renters policies are issued through partner carriers rather than by Progressive itself, which can change the claims experience and the fine print. That is not a dealbreaker, but it is worth asking about before you buy, along with whether flood coverage or extra protection for valuables needs a separate endorsement.
- Easy bundling with Progressive auto policies
- Online quotes and policy management
- Flexible coverage options
- Renters policies in some states are underwritten by partner carriers
- No single published starting price
GEICO is a convenient choice if you already have a GEICO auto policy and want one company to deal with. You can get a renters quote through GEICO, manage payments in the GEICO app and often earn a multi-policy discount for keeping both policies together. For renters who value a single login and a familiar brand, that convenience counts.
The important detail is that GEICO does not underwrite renters policies itself. Your policy comes from a third-party partner carrier, and the partner varies by state, so two GEICO renters customers in different states may hold quite different policies. Before you buy, find out which carrier would underwrite your policy, read its coverage terms and check how claims are handled, since you will deal with that carrier, not GEICO, when you file a claim.
- Simple add-on for GEICO auto customers
- Multi-policy savings
- App-based policy management
- Renters policies are written through third-party partner carriers
- Coverage terms can vary by state and partner
Liberty Mutual suits renters who want to shape a policy around specific needs rather than take a standard package. You can adjust personal property and liability limits, add replacement cost coverage so belongings are replaced at today's prices rather than their depreciated value, and add coverage for items like jewelry. Quotes are available online, or through an independent agent if you prefer advice.
The downside is price. Liberty Mutual rarely competes with the cheapest digital carriers on a basic policy, and the discounts it advertises, including bundling savings, vary by state and by how you buy. It is worth a quote if you have valuables that need scheduled coverage or if you want more control over limits, but compare it directly with a lower-cost option using identical coverage amounts before you decide.
- Highly customizable policies
- Replacement cost options for belongings
- Online quotes or independent agents
- Prices can run higher than budget carriers
- Discount details vary by state
Nationwide is a good fit for renters who expect their insurance needs to grow. Alongside a standard renters policy, you can add endorsements for valuables, identity theft and other risks, and bundle with auto insurance from the same company. As a large national carrier, it offers the stability and claims infrastructure that smaller insurers sometimes lack.
As with several traditional carriers here, there is no single starting price to compare, so a quote is the only way to know your cost. Coverage options and availability also vary by state, which means the policy your friend holds in another state may not match what is offered where you live. Get the quote with the same limits and deductible you used for the other companies on this list, and read the exclusions for flood, earthquake and high-value items before you commit.
- Wide range of coverage options and endorsements
- Bundling with auto and other policies
- Large national carrier
- No published starting price for renters
- Availability and options vary by state
How we picked these
We compared official coverage pages, pricing pages and quote tools from each company, along with public reviews and comparison data on renters insurance costs. We favored companies with nationwide availability, clear coverage descriptions and a claims process renters can actually use, and we included both digital-first carriers and traditional insurers with agent networks. We did not claim hands-on testing of claims, since we compared published information rather than filing claims ourselves. Prices shown are starting prices published by the carrier or marked as See website where the carrier does not publish a single starting rate, because renters premiums vary sharply by location, coverage limits and deductible.
What to check before you buy renters insurance
Start with an inventory of what you own
Walk through your home and add up what it would cost to replace your furniture, electronics, clothes and kitchen gear at today's prices. Most renters are surprised by the total, and that total is the number your personal property limit should cover. Take photos of serial numbers and receipts for expensive items, and keep the list somewhere outside your home, such as in cloud storage, so it survives the same fire or theft you would claim for.
Match your liability limit to your lease
Many leases require at least $100,000 of liability coverage, and some ask for more. Liability coverage helps pay if someone is injured in your home or if you accidentally damage a neighbor's property, for example with a washing machine leak that floods the unit below. Raising the limit is usually cheap compared with the protection it adds, so do not default to the minimum without checking what your lease requires.
Read the exclusions before you need them
Standard renters policies typically do not cover flood, earthquake, normal wear and tear, or damage you cause on purpose. High-value items like jewelry, watches, cameras and musical instruments often have lower sub-limits, which means you may need extra scheduled coverage for full protection. Roommates who are not named on the policy are usually not covered either, so each roommate may need their own policy or to be listed on yours.
Compare identical quotes, not headline prices
A $5 per month starting price and a $20 per month quote can describe very different policies. When you compare, use the same personal property limit, the same liability limit and the same deductible for every company, and ask about discounts for safety devices, claims-free history and bundling. That is the only way to tell whether one company is genuinely cheaper or simply offering less coverage.
Frequently asked questions
What is the best renters insurance company?
There is no single best company for every renter. Lemonade and Allstate lead on advertised starting price, State Farm leads on local agent support, and USAA leads for eligible military families. Get quotes from at least three companies with identical coverage limits and pick the one that gives you the coverage you need at a price you can afford.
What is the best company for renters insurance if I want the cheapest policy?
Start with Lemonade and Allstate, which both advertise policies from $5 per month, and add GEICO if you already hold a GEICO auto policy. Your actual price depends on your ZIP code, coverage limits and deductible, so a cheap starting price in one state can still mean a higher quote in yours.
Does renters insurance cover my belongings outside my home?
Most standard policies cover personal property away from home, such as a laptop stolen from a coffee shop or luggage taken while traveling, up to your policy limits and minus your deductible. Check your policy for limits on specific categories, and confirm whether high-value items need extra scheduled coverage.
Do I need renters insurance if my landlord has insurance?
Yes, in most cases. Your landlord's policy covers the building and the landlord's own property, not your belongings or your liability. Some leases also require you to carry your own policy and to show proof of coverage before move-in, so read your lease carefully.
What do renters insurance reviews usually say about claims?
Reviews tend to praise digital carriers for fast, app-based claims on simple losses, and traditional carriers for agent help on larger or more complex claims. The pattern to look for is how a company handles your kind of claim, so ask about the claims process, the deductible and the timeline before you buy, not after a loss.
Sources we checked (8)

Online Jobs is an independent blog about careers, online work, learning new skills and the tools that help people earn. More about us.
Keep reading
All posts
Best Whole Life Insurance Companies
We compared the best whole life insurance companies on dividends, cash value, riders and financial strength, so buyers can shortlist wisely in 2026 today.
Best Trading Apps for Beginners
Compare the best trading app for beginners, with $0 stock commissions, fractional shares, education, paper trading and account types explained in 2026 now.
Best Trading App
We compared the best trading apps for beginners and active traders on fees, tools, accounts and ease of use, so you can pick a platform that fits your plan.