Best House Insurance Companies in 2026: 9 Companies Compared

How we put this together: we compare official feature and pricing pages, app store listings, privacy policies and public user reviews. Prices change, so check the provider's site before you pay.
Key takeaways
- Amica Mutual stands out for claims satisfaction in US studies, while State Farm suits buyers who want a large agent network and bundling.
- USAA is often the best value for eligible military families, but eligibility is limited, so most buyers cannot choose it.
- In the UK, Aviva, Direct Line, LV= and Admiral all offer strong combined buildings and contents policies, but limits and add-ons differ by tier.
- Chubb suits high-value homes, with broader replacement cover, but premiums are usually higher than standard insurers.
- Price depends heavily on location, property type, rebuild cost and claims history, so quotes for the same home can vary widely.
Quick comparison
| Name | Who it suits | Starting price | Free option | |
|---|---|---|---|---|
 Amica Mutual | Claims satisfaction overall | See website | No | Visit |
 State Farm | Bundling and agent support | See website | No | Visit |
 Allstate | Digital tools and optional cover | See website | No | Visit |
 Chubb | High-value homes | See website | No | Visit |
 USAA | Military families | See website | No | Visit |
 Aviva | UK combined cover and digital claims | See website | No | Visit |
 Direct Line | UK all-round buildings and contents | See website | No | Visit |
 LV= | UK customer service and claims | See website | No | Visit |
 Admiral | UK multi-policy discounts | See website | No | Visit |
The best house insurance companies
House insurance is not a product you buy on price alone, because the real test comes when you claim. A cheap policy with a low contents limit, a high excess or missing accidental damage cover can cost far more than the premium saved. We compared official policy pages, independent ratings, claims studies and public reviews to sort companies by coverage, claims service and fit, across both the US and the UK.
This is not financial advice. Insurance needs depend on your home, location, mortgage terms and personal circumstances, so use this guide to shortlist companies, then read the policy wording and get quotes for your own property before buying.
Amica Mutual is the company other US insurers are measured against for claims. In J.D. Power property claims studies, Amica has ranked at or near the top, and its customer satisfaction scores are consistently strong. Amica also offers a database of vetted contractors, with guarantees on work in some programmes, which can make repairs less uncertain.
The downside is price and availability. Amica is rarely the cheapest quote, and some discounts and features vary by state. It also does not serve every buyer in every market in the same way as a larger carrier. If claims service is your top priority and the quote is within reach, Amica is a strong first quote to get.
- Top-ranked claims satisfaction in US studies
- Strong customer service record
- Contractor database with work guarantees in some programmes
- Premiums are not usually the cheapest
- Availability and discounts vary by state
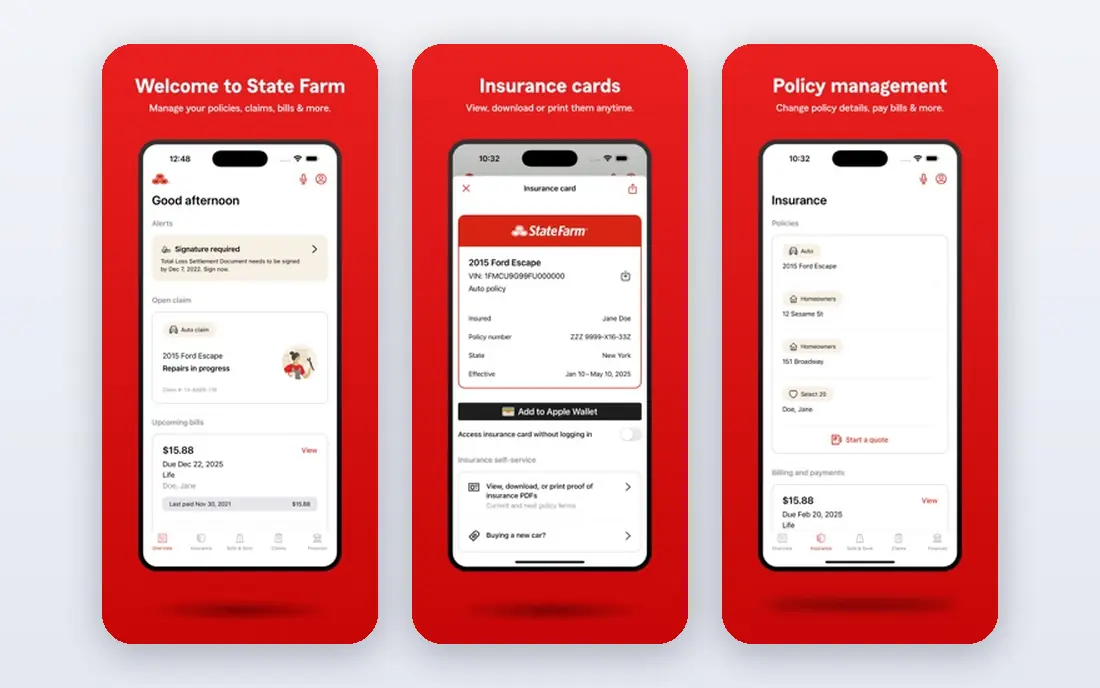
State Farm suits buyers who want a local agent and a single company for home and auto. As the largest US home insurer by market share, it has a wide agent network, broad coverage options and bundling discounts that can lower the combined premium. Its digital tools and mobile app also make policy management and claims filing straightforward for many customers.
The trade-off is that claims satisfaction, while solid, does not always match Amica or Chubb in independent studies. Premiums can also be higher than smaller regional insurers for the same home. State Farm is a safe, well-known choice, especially for buyers who value an agent they can call, but it is still worth comparing with at least two other quotes.
- Largest US home insurer by market share in many sources
- Large agent network
- Bundling discounts for home and auto
- Claims satisfaction trails top-ranked carriers in some studies
- Premiums can be higher than regional rivals
Allstate is a good fit for buyers who manage most things online and want a wide choice of add-ons. Its app and website make it easy to view cover, pay bills and start a claim, and optional cover includes scheduled personal property, yard and garden protection and water backup, which standard policies often limit. Claim RateGuard, where available, can help prevent a premium rise after a qualifying claim.
The weakness is consistency. In some customer satisfaction and claims studies, Allstate sits behind Amica, Chubb and other top carriers. That does not mean every claim goes badly, but it is a reason to read recent reviews for your state and to check the excess and limits on the exact policy offered. Allstate works best when its digital tools and add-ons match your needs and the quote is competitive.
- Strong mobile app and online policy tools
- Broad optional cover, including water backup and scheduled property
- Claim RateGuard in eligible states
- Customer satisfaction and claims experience trail top carriers in some studies
- Premiums can be higher than regional competitors
Chubb is built for homes where standard limits fall short. It offers broader replacement cost cover, higher limits for valuables and collections, and extra services that standard policies often exclude or cap. In J.D. Power claims studies, Chubb has ranked near the top, which matters when a large claim involves specialist repairs or replacement of high-value items. For owners of larger or older homes, that depth can be worth the premium.
The price is the main barrier. Chubb is not trying to be the cheapest quote for a standard home, and its full value only shows when the home and contents need higher limits. If your home is standard and your main concern is price, a mainstream insurer may give similar core cover for less. Chubb fits best when replacement cost and service matter more than the lowest premium.
- Broad cover for high-value homes
- Strong replacement cost options
- High claims satisfaction in US studies
- Premiums are usually higher than standard insurers
- Not the right fit for a basic, low-value home
USAA is often the best value choice for those who can join it. It serves military members, veterans and eligible family members, and its home insurance is frequently cited for competitive pricing and strong service. Bundling home and auto, plus discounts for claims-free history and safety features, can make the combined cost attractive. For eligible households that move often, USAA also understands military housing needs better than many general insurers.
The limit is obvious: most buyers cannot join. Eligibility rules are strict, and family eligibility depends on the member's status. If you are eligible, USAA should be one of your first quotes. If you are not, Amica, State Farm or a regional carrier is a closer comparison for your situation.
- Strong value for eligible members in many comparisons
- High satisfaction scores
- Good bundling options for military households
- Eligibility is limited to military members, veterans and eligible family
- Not available to the general public
Aviva is one of the largest UK insurers, and its home policies suit buyers who want buildings and contents in one place with online management. Combined cover can reach high buildings limits, and digital tools make it easier to file and track a claim without long phone calls. Some policies also include support for flood resilience, which matters in higher-risk areas, though cover depends on location and property.
As with most UK insurers, the headline policy and the top tier are different products. Accidental damage, home emergency cover and personal possessions cover may be add-ons or higher-tier features, so a cheap quote can miss cover you assumed was included. Compare the policy wording, not just the premium, and check the excess for escape of water and other common claims.
- Competitive combined buildings and contents policies
- Digital claims tools
- Flood resilience support in some policies
- Best cover sits on higher tiers
- Add-ons and limits need careful checking at quote stage
Direct Line is known for solid, straightforward home cover in the UK. Its buildings and contents policies offer high limits on higher tiers, with options for accidental damage, personal possessions and home emergency cover. Because it does not sell through comparison sites, you need to get a quote direct, which takes a little longer but can give a clearer view of the exact policy on offer.
Direct Line suits buyers who want a well-known insurer with broad cover and are willing to spend a few extra minutes getting a direct quote.
- Strong all-round buildings and contents cover
- Does not sell through comparison sites, so quotes come direct
- High contents limits on top tiers
- No comparison site pricing makes quick comparison harder
- Premiums vary by property and location
LV=, also written Liverpool Victoria, is frequently rated highly for service and claims in the UK. Its home policies include high buildings and contents limits on higher tiers, with features such as bike cover and green rebuild options in some plans. A guarantee on repairs when using recommended repairers, where offered, can also reduce worry after a claim. For buyers who rank service above the lowest price, LV= is a strong shortlist choice.
The premium for the best cover is not always the lowest, and some features that look standard on a comparison table are tier-dependent. Check accidental damage, personal possessions and alternative accommodation limits on the exact quote, and compare the excess. LV= fits buyers who want a service-led insurer and are willing to pay a little more for it.
- Highly rated for customer service and claims handling
- Five-star rated policies in independent comparisons
- Green rebuild options in some policies
- Top cover and add-ons increase the premium
- Limits vary by tier, so check contents and alternative accommodation limits
Admiral suits households that already use Admiral for car or other cover, or that want several policies in one place. Its home insurance comes in tiers, with the platinum tier offering higher contents limits, accidental damage as standard and home emergency cover included. Multi-policy discounts can make the combined cost attractive, especially for families with several cars and a home to insure.
The cheapest tier is more basic, so a low Admiral quote may not include the cover a higher tier offers. Compare tiers carefully, and check whether home emergency, legal cover and personal possessions are included or add-ons. Admiral is a good value choice when the tier matches your needs and the multi-policy discount applies, rather than on headline price alone.
- Competitive multi-policy discounts
- Tiered policies from standard to platinum
- Accidental damage included on higher tiers
- Cheapest tier is more basic than the top tier
- Contents limits and emergency cover vary by tier
How we picked these
We compared official policy pages, independent ratings, claims satisfaction studies and public reviews, and we checked that each company offers real house or home insurance in October 2026. We favoured companies with strong claims records, clear policy tiers, broad coverage options and a track record in their home market. We included both US and UK companies because readers search for house insurance in both markets, and we noted eligibility limits where they apply, such as USAA.
We did not claim hands-on testing of claims, and we did not publish premium figures, because premiums vary so much by property, location and history that a single figure would mislead. Use the company pages and quotes for your own home, and read the policy wording for limits, excesses and exclusions before buying. This is not financial advice.
What to check before you buy house insurance
Start with rebuild cost, not market value. Buildings cover should reflect what it would cost to rebuild your home, including fees and debris removal, not what you could sell it for. An underinsured home can leave you paying part of a large claim yourself, so check the buildings limit and whether the policy offers unlimited cover or a fixed sum.
Check contents, accidental damage and water cover
Contents limits, single-item limits and accidental damage cover vary widely. A standard policy may cap valuables, bikes or tech, and may exclude accidental damage unless you add it. Escape of water is a common and costly claim, so check the excess and any conditions on pipes, tanks and trace-and-access cover. Personal possessions cover matters if you take valuables outside the home.
Compare excess, add-ons and claims service together
A low premium with a high excess can be poor value if you claim. Compare the compulsory and voluntary excess, the cost of add-ons such as home emergency and legal cover, and the claims service record. Read recent claims reviews for your country, and check whether the insurer offers a repair guarantee or a vetted contractor network. The best house insurance company for you is the one whose cover, excess and service fit your home and budget together.
Frequently asked questions
Which home insurance company is the best?
There is no single best company for every home, because price and cover depend on location, property and claims history. In US studies, Amica Mutual often leads for claims satisfaction, while in the UK, Aviva, Direct Line, LV= and Admiral all rank strongly in independent comparisons. Get quotes from at least three companies, compare limits and excesses, and choose the policy that covers your rebuild cost and contents properly.
What is the best home insurance company for high-value homes?
Chubb is a strong choice for high-value homes, with broader replacement cost cover and higher limits for valuables. Some UK insurers also offer high-value or prestige policies with higher limits and specialist claims handling. If your home or contents exceed standard limits, ask for a high-value quote rather than trying to stretch a standard policy.
Who is the best home insurance company for military families?
USAA is often cited as the best value for eligible military families in the US, with competitive pricing and strong service. Eligibility is limited to military members, veterans and eligible family members, so check the current rules before assuming you can join. If you are not eligible, Amica and State Farm are common alternatives for military households.
Is the cheapest house insurance quote the best?
Not always. A cheap quote can have a lower contents limit, a higher excess, missing accidental damage cover or exclusions that matter for your home. Compare the policy wording, limits and excess beside the premium, and check claims reviews. The cheapest quote that still covers your rebuild cost, contents and common risks is better than the cheapest quote overall.
What does house insurance usually cover?
House insurance usually covers buildings and contents against fire, storm, flood, theft, escape of water and other named risks, depending on the policy. Standard policies often exclude or limit wear and tear, gradual damage, and some types of water or subsidence damage. Always read the exclusions and the limits for valuables, bikes and items taken outside the home.
How can I lower my house insurance premium?
You can lower a premium by raising your voluntary excess if you can afford it, improving security with approved locks and alarms, bundling home and auto cover, and avoiding small claims that affect your history. Keeping your home maintained, fixing leaks early and reviewing your cover each year also help. Do not cut cover you need, such as rebuild cost or accidental damage, just to save a small amount.
Sources we checked (9)

Online Jobs is an independent blog about careers, online work, learning new skills and the tools that help people earn. More about us.
Keep reading
All posts
Best Whole Life Insurance Companies
We compared the best whole life insurance companies on dividends, cash value, riders and financial strength, so buyers can shortlist wisely in 2026 today.
Best Trading Apps for Beginners
Compare the best trading app for beginners, with $0 stock commissions, fractional shares, education, paper trading and account types explained in 2026 now.
Best Trading App
We compared the best trading apps for beginners and active traders on fees, tools, accounts and ease of use, so you can pick a platform that fits your plan.