Best Home Owners Insurance Companies in 2026: 8 Services Compared

Local agent support and bundling · Starting price: See website
How we put this together: we compare official feature and pricing pages, app store listings, privacy policies and public user reviews. Prices change, so check the provider's site before you pay.
Key takeaways
- State Farm suits most homeowners who want a local agent and a broad set of discounts, while Amica stands out for bundling and claim-free savings.
- USAA often offers strong value, but only military members, veterans and eligible family members can join.
- Lemonade fits simpler homes and digital-first buyers, while larger insurers fit older homes, high-value homes and complex claims better.
- No single quote tells the full story, since rates depend on location, rebuild cost, roof age, deductible and claims history.
Quick comparison
| Name | Who it suits | Starting price | Free option | |
|---|---|---|---|---|
| State Farm | Local agent support and bundling | See website | No | Visit |
 USAA | Military families | See website | No | Visit |
 Amica | Bundling and claim-free discounts | See website | No | Visit |
 Allstate | Wide coverage options | See website | No | Visit |
 Travelers | Green home and new home discounts | See website | No | Visit |
 Nationwide | Broad agent and online service | See website | No | Visit |
 Lemonade | Fast digital quotes and claims | See website | No | Visit |
 Progressive | Bundling with auto cover | See website | No | Visit |
The best home owners insurance companies
We compared national insurers on the cover they offer, the discounts they publish, how claims work, and who can actually buy a policy. Prices are individual, so use this list to shortlist two or three companies and compare quotes on the same dwelling limit and deductible.
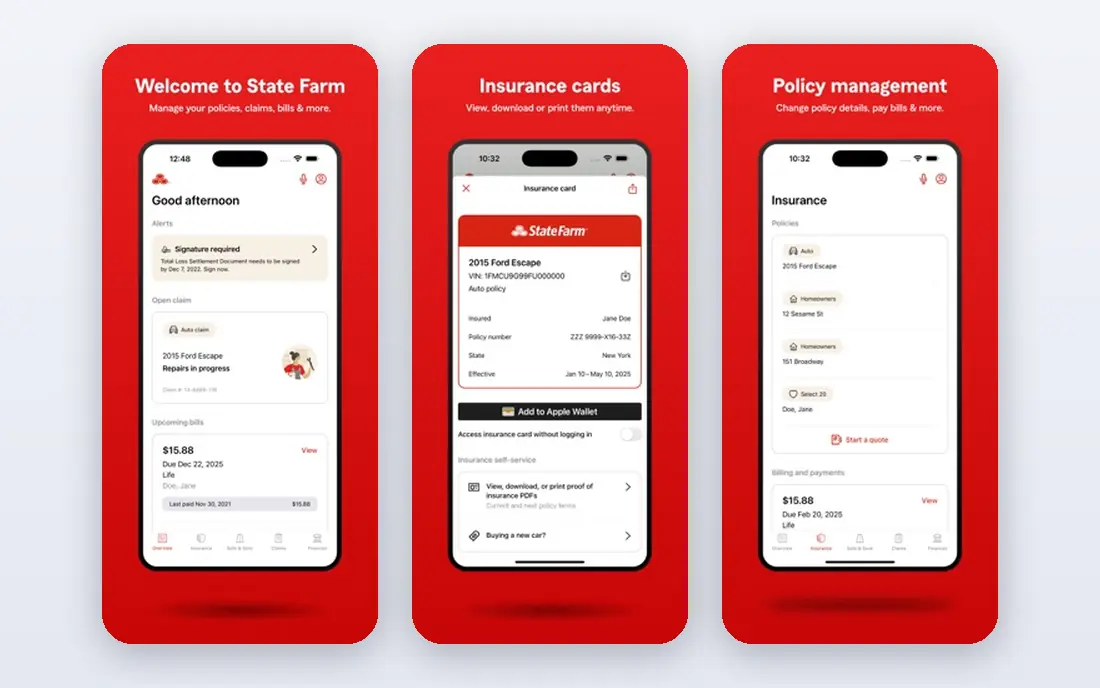
State Farm is the practical starting point for many homeowners, mainly because you can talk to a local agent and still manage much of the policy online. Its homeowners cover includes dwelling, personal property, liability and additional living expenses, with endorsements available for items such as water backup and higher-value belongings. That mix makes it a sensible fit for standard family homes, including homes where the owner wants advice on rebuild cost rather than guessing a limit alone.
The catch is price variation. State Farm is competitive in many states and less so in others, especially where wildfire, hurricane or hail risk is high. Bundling home and auto cover usually helps, and discounts for protective devices and claim-free history can narrow the gap further. Get the quote in writing, check the roof settlement terms, and confirm whether replacement cost or actual cash value applies to the roof.
- Large agent network
- Broad coverage and endorsement options
- Bundling discounts for home and auto
- Quotes vary a lot by state
- Online-only buyers may prefer a more digital insurer
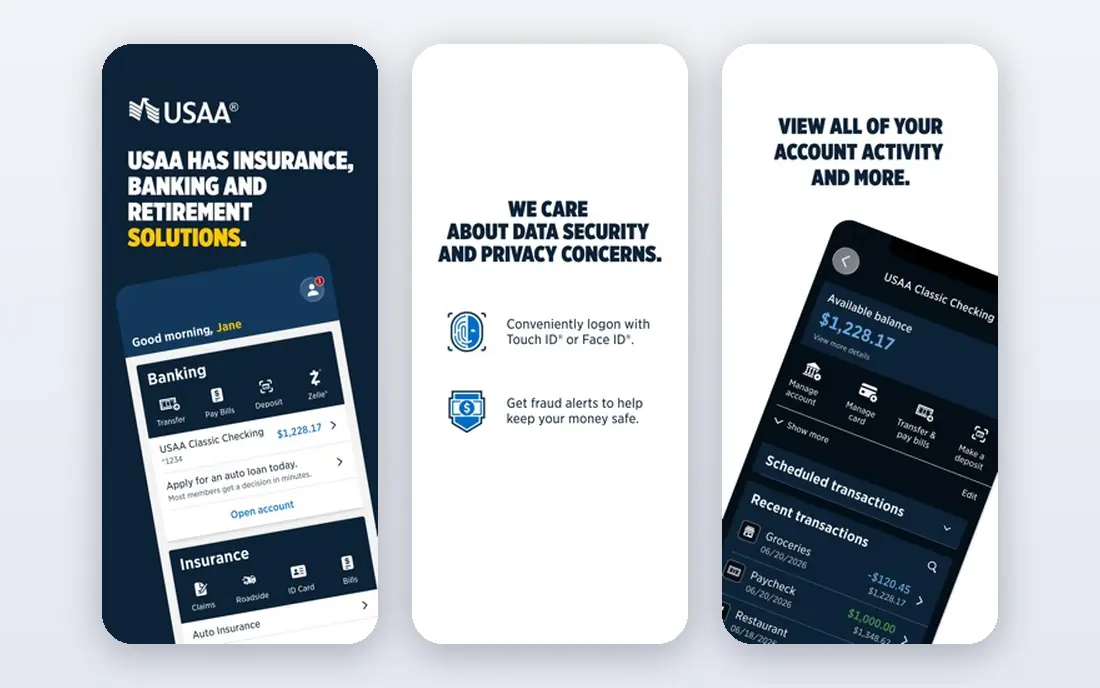
USAA serves current military members, veterans and eligible family members, and that focus shows in its policies. Cover includes standard dwelling and personal property protection, plus options that reflect military life, such as cover for uniforms and equipment in some policies. Members can quote, manage policies and file claims online or through the app, which suits families who move often.
The limit is eligibility, not quality. If you do not qualify, USAA is not an option at any price, so check membership before spending time on a quote. If you do qualify, it belongs on every shortlist, because its combination of service and military-specific cover is hard for general insurers to match. As with any insurer, compare the same limits and deductible against at least one other quote.
- Cover shaped for military life
- Strong member service reputation
- Bundling and protective device discounts
- Membership is restricted
- Not available to the general public
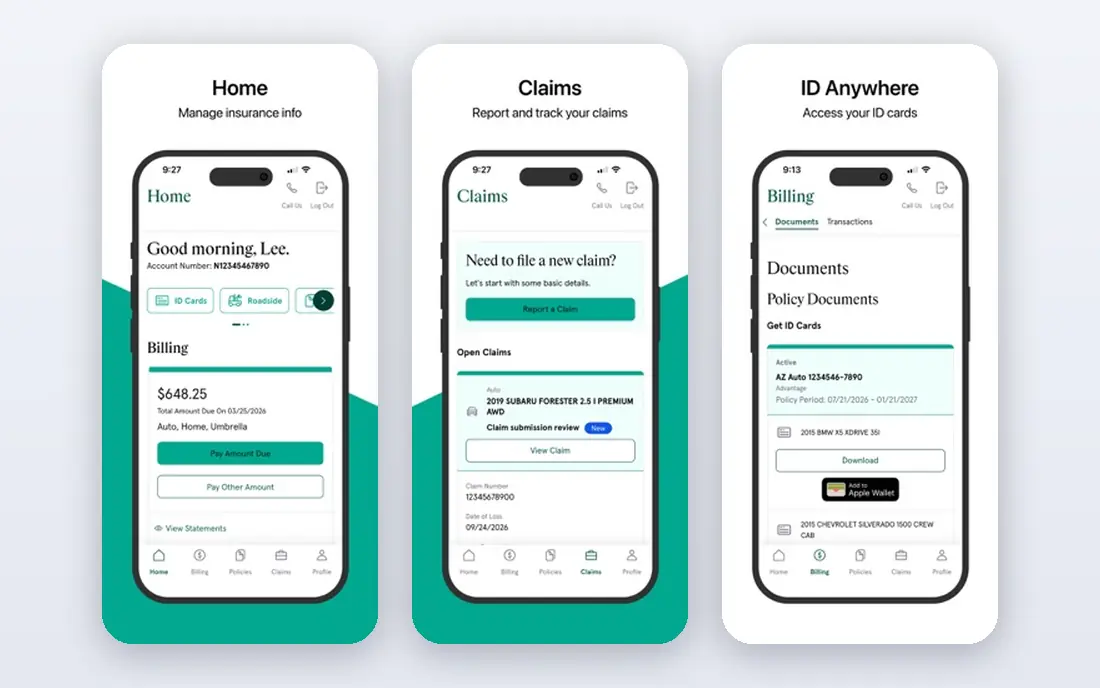
Amica is a mutual insurer, which means eligible policyholders may receive dividends when the company performs well, although dividends are never guaranteed. Its homeowners policies cover the dwelling, personal property and liability, with endorsements for water backup, earthquake in some states, and scheduled personal property. Claims can be filed online, by phone or through the app, and the app tracks claim status.
Amica rewards loyalty and careful ownership. Its published discounts include bundling home with auto, umbrella or life cover, staying claim-free, paying by autopay, going paperless and paying in full. Those savings matter, because the starting quote is not always the lowest. If you already insure a car with Amica, or you plan to bundle, the combined price is often where Amica wins.
- Bundling discount of up to 30 percent in published materials
- Claim-free and autopay discounts
- Dividend policies for some customers
- Premiums can be higher before discounts
- Some endorsements vary by state
Allstate offers a wide menu of homeowners cover, which helps when a standard policy does not fit. Beyond dwelling, property and liability cover, buyers can add options for water backup, identity protection and higher limits for valuables, subject to state availability. Agents are widely available, and the app supports claims, payments and policy documents.
The honest catch is that Allstate pricing can swing a lot between states and even ZIP codes, so a neighbor's good rate says little about yours. Some of its better-known features, such as claim-free rewards, depend on the policy form and state, so read the declarations page rather than assuming they apply. Allstate fits buyers who want choice and are willing to compare endorsements line by line.
- Broad endorsement range
- Claim RateGuard and deductible rewards in some policies
- Large agent network
- Rates vary sharply by region
- Some features need specific policy forms
Travelers is a good pick for owners of newer or certified green homes, because its published discounts include savings for new homes, green certification and protective devices. Standard homeowners cover includes dwelling, other structures, personal property, liability and loss of use, with endorsements for valuables, water backup and equipment breakdown in many states.
The trade-off is consistency. Travelers sells through agents and partners in many areas, so the buying experience depends on where you live. That is not a flaw in the cover itself, but it means you should confirm which endorsements are offered in your state before assuming the national list applies. For a newer home with alarms and updated systems, Travelers is worth a quote.
- Green home discount for certified homes
- New home and protective device discounts
- Strong commercial and personal lines background
- Agent availability varies
- Online quote experience differs by state
Nationwide covers standard homeowners needs with dwelling, personal property, liability and loss of use protection, plus endorsements such as water backup and brand-new belongings replacement on some policies. Buyers can work with an agent or quote online, and claims can be filed through the app or by phone. That flexibility suits buyers who want a choice in how they buy and manage cover.
Nationwide is rarely the standout on price alone, and its feature set varies by state, so the policy you read about online may differ from the one offered to you. Where it earns a place is breadth: home, auto, life and pet cover under one company, with bundling discounts across several of them. If you plan to consolidate policies, compare the total household price, not just the home premium.
- Wide product range
- Bundling discounts
- Online quoting and claims in many states
- Availability and features vary by state
- Not the cheapest in every region
Lemonade takes a different approach from the traditional insurers on this list, with quotes and claims handled mainly through its app and website. Its homeowners policies cover dwelling, personal property, liability and loss of use, with extra cover available for valuables and equipment. The buying process is quick for straightforward homes, and the policy documents are written in plainer language than many competitors use.
The limit is scope. Lemonade fits condos, newer homes and standard houses best, and it is less suited to older homes, historic properties or homes with unusual risks. Availability also varies by state, so check that first. If your home is straightforward and you prefer to manage everything on your phone, Lemonade is a strong, low-friction option.
- Fast online quotes
- App-based claims
- Clear policy summaries for simpler homes
- Limited fit for older or high-value homes
- Availability varies by state
Progressive is best known for auto insurance, but it also sells homeowners cover, in many states through partner insurers. That matters, because the underwriting company, claims team and available endorsements can differ from the Progressive brand you know from car insurance. Standard cover includes dwelling, personal property, liability and loss of use, with endorsements depending on the partner.
The advantage is bundling. If Progressive already insures your cars, adding home cover through the same quote flow can save money and simplify billing. The catch is that you should identify the actual home insurer on the quote and check its claims reputation and endorsement list. For existing Progressive auto customers, it is a sensible quote to get, but not one to accept without that check.
- Home and auto bundling
- Online quoting
- Broad partner network for home policies
- Home cover is often underwritten by partner insurers
- Experience varies by partner
How we picked these
We compared official feature pages, pricing and discount pages, app store listings, privacy policies and public reviews for national insurers that sell homeowners cover in the United States. We favoured companies with broad availability, published discount details, clear claims routes and a range of endorsements, and we included both traditional agent-led insurers and a digital-first option. We did not rank on a single average premium, because homeowners rates depend so heavily on location, rebuild cost, roof age and deductible that a national average would mislead more than it helps.
What to compare before you buy
Start with the dwelling limit, not the premium. Ask each insurer how it calculated rebuild cost, and check whether the policy pays replacement cost or actual cash value for the roof. A low premium with a low dwelling limit or a cash-value roof settlement can leave a large gap after a major loss, which is exactly when the policy matters most.
Discounts that actually move the price
Bundling home and auto cover is usually the largest single saving, followed by protective devices, claim-free history and paying in full. Tell every insurer about alarms, sprinkler systems, leak detectors, a new roof and recent renovations, so each quote reflects the same facts. Discounts vary by state, so do not assume a discount listed on a national page applies in yours.
Cover gaps to check in writing
Standard homeowners policies do not cover flood damage from outside the home, and earthquake cover usually needs a separate endorsement. Water backup from drains and sump pumps is also commonly excluded unless added. If you live near water, in a quake zone, or in a home with a basement, ask for those endorsements by name and get the answer on the quote.
Please note: this article is general information, not insurance or financial advice. Rates depend on individual circumstances and location, including your home, its age and construction, your claims history and your state. Compare quotes on identical limits and deductibles, and check the full policy wording before you buy.
Frequently asked questions
How much does homeowners insurance cost?
There is no single answer, because the price depends on your state, rebuild cost, roof age, deductible, claims history and the cover you choose. National averages give a rough range, but two homes on the same street can receive very different quotes. The reliable method is to get three quotes on identical limits and deductibles and compare the total, including endorsements.
What does a standard homeowners policy cover?
A standard policy usually covers the dwelling, other structures such as a detached garage, personal property, liability if someone is hurt on your property, and additional living expenses if a covered loss makes the home uninhabitable. Flood damage from outside the home and earthquake damage are normally excluded unless you add separate cover.
Is USAA available to everyone?
No, USAA membership is limited to current military members, veterans, pre-commissioned officers and eligible family members, including spouses and children of members. If you are unsure whether you qualify, check the membership page on the USAA website before requesting a quote. Everyone else should shortlist from the general insurers on this list.
Should I bundle home and auto insurance?
Bundling often saves money and simplifies billing, and several insurers on this list publish bundling discounts. It is not always the cheapest route, though, because one company may price your home well and your cars poorly. Compare the combined price against the best separate quotes before deciding.
How do I choose a deductible?
A higher deductible usually lowers the premium, but it raises what you pay out of pocket after a claim. Choose a deductible you could pay without strain, and check whether wind, hail or hurricane deductibles are set as a percentage of the dwelling limit in your state. Those percentage deductibles can be much larger than a flat deductible.
Is Lemonade good for older homes?
Lemonade fits simpler, newer homes best, and its digital process is quick for those properties. Older homes, historic homes and homes with unusual construction often need the wider endorsement range and agent advice that traditional insurers offer. If your home falls in that group, get quotes from agent-led insurers first.
Sources we checked (8)
- https://www.statefarm.com/insurance/homeowners
- https://www.usaa.com/inet/wc/insurance-homeowners
- https://www.amica.com/home-insurance/discounts
- https://www.allstate.com/home-insurance/
- https://www.travelers.com/personal-insurance/home-insurance
- https://www.nationwide.com/personal/insurance/homeowners/
- https://www.lemonade.com/homeowners
- https://www.progressive.com/homeowners/

Online Jobs is an independent blog about careers, online work, learning new skills and the tools that help people earn. More about us.
Keep reading
All posts
Best Whole Life Insurance Companies
We compared the best whole life insurance companies on dividends, cash value, riders and financial strength, so buyers can shortlist wisely in 2026 today.
Best Trading Apps for Beginners
Compare the best trading app for beginners, with $0 stock commissions, fractional shares, education, paper trading and account types explained in 2026 now.
Best Trading App
We compared the best trading apps for beginners and active traders on fees, tools, accounts and ease of use, so you can pick a platform that fits your plan.