Best Credit Score Apps in 2026: 9 Apps Compared

How we put this together: we compare official feature and pricing pages, app store listings, privacy policies and public user reviews. Prices change, so check the provider's site before you pay.
Key takeaways
- Most free apps show VantageScore, while most lenders use FICO, so the number in a free app may differ from the number a lender sees.
- Credit Karma and Experian are the best free starting points, because they cover different bureaus and offer useful alerts.
- myFICO is the best paid pick if you need lender style FICO scores from all three bureaus before a mortgage or car loan.
- Checking your own score in an app is a soft inquiry and does not hurt your score, while applying for credit can create a hard inquiry.
- This is not financial advice. If you are rebuilding credit after missed payments or debt, consider advice from a nonprofit credit counsellor.
Quick comparison
| Name | Who it suits | Starting price | Free option | |
|---|---|---|---|---|
 Credit Karma | Free two bureau tracking | Free | Yes | Visit |
 Experian | Free FICO score | Free | Yes | Visit |
 myFICO | Lender style FICO scores | Free | Yes | Visit |
 Credit Sesame | Actionable credit tips | Free | Yes | Visit |
 NerdWallet | Scores plus money tools | Free | Yes | Visit |
 CreditWise | Free score simulations | Free | Yes | Visit |
 Kikoff | Credit building | $5 per month | No | Visit |
 Aura | Identity protection plus credit | See website | Free trial | Visit |
 WalletHub | Daily score updates | Free | Yes | Visit |
The best credit score apps
We compared official feature pages, app store listings, privacy policies and public reviews for the apps below. Prices are US list prices reported in 2026 coverage and can change, so check the vendor site for the current plan. Focus on score type and bureau coverage first, because a free score from one bureau is less useful than it looks if your lender checks a different bureau or model.
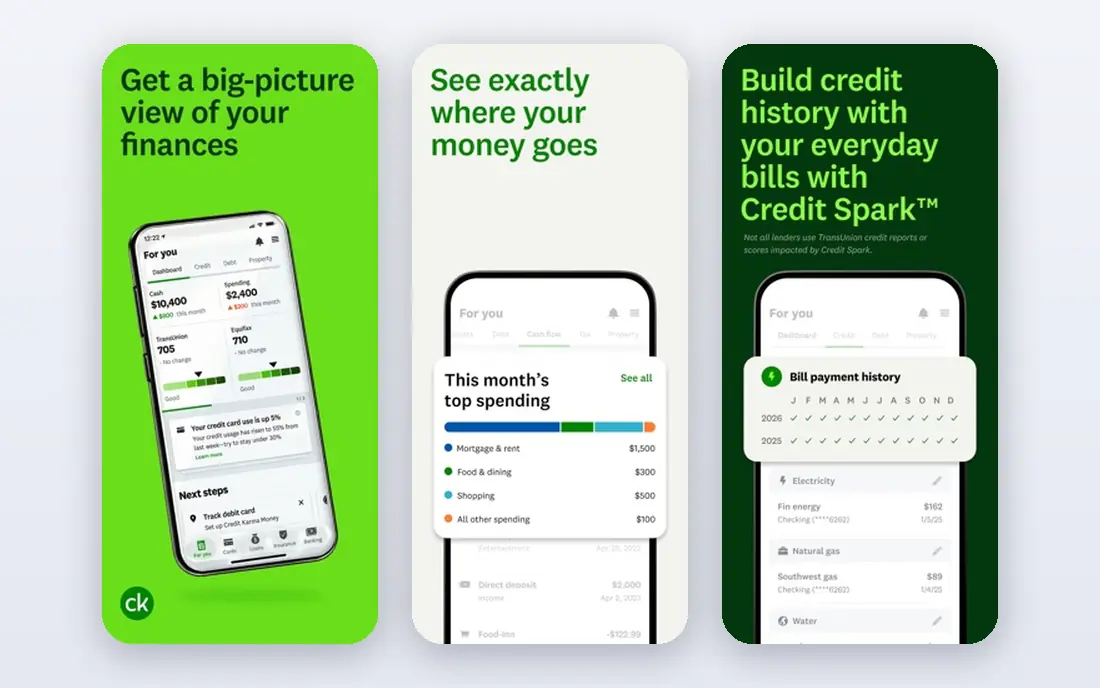
Credit Karma is our pick for free, frequent credit tracking. You get scores from two bureaus, alerts when something changes on those reports, and a simulator that shows how paying down a balance or opening a card might affect your score. For most people checking credit monthly, that is enough to spot errors and track progress.
The limits matter. Credit Karma does not show an Experian score, and its scores use VantageScore, which most lenders do not use for decisions. Treat the Credit Karma score as a trend indicator, not as the exact number a mortgage lender will see, and pair it with a FICO source before a major application.
- Free VantageScore from TransUnion and Equifax
- Alerts for new accounts and inquiries
- Score simulator
- No Experian score on the free plan
- Dashboard includes many card and loan offers
- Score is VantageScore, not FICO
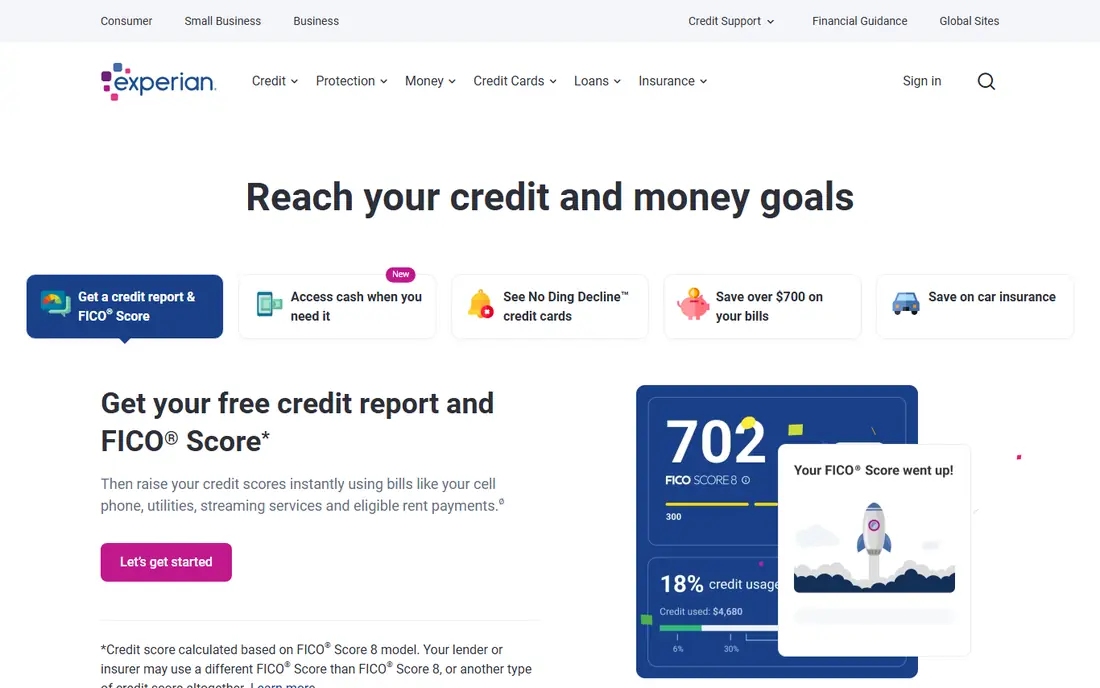
Experian is the best free complement to Credit Karma, because it fills the gaps the other app leaves. The free plan gives a FICO Score 8 based on Experian data, which is closer to what many lenders use, and Experian Boost lets you add qualifying on time utility, streaming and phone payments to your Experian file. That can help people with thin credit files who pay bills reliably but have few traditional accounts.
The free plan is limited to one bureau, so it will not catch changes at TransUnion or Equifax. Paid IdentityWorks adds three bureau monitoring and identity protection, but most users should start free and only upgrade if they need daily three bureau alerts or identity theft insurance.
- Free FICO Score 8 from Experian data
- Experian Boost can add utility and phone payments
- Credit lock on some plans
- Free plan covers only Experian
- Full three bureau monitoring requires a paid plan
- Boost may not help every lender, since not all use the boosted score
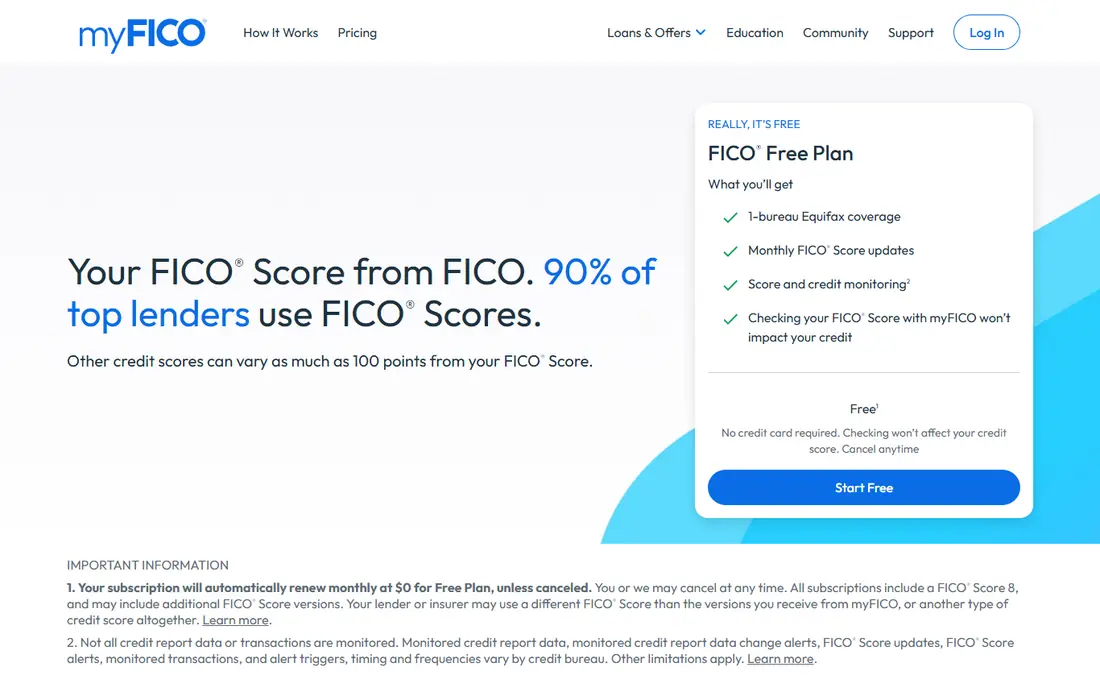
myFICO is the paid pick for a specific moment: the months before a mortgage, auto loan or other major application. It shows FICO scores and versions that lenders actually use, including industry specific scores, which free VantageScore apps cannot show. That detail helps you spot a bureau specific problem before a lender does.
For everyday tracking, myFICO is overkill. The paid plans are expensive for a monthly habit, and the free plan only covers one bureau score. Use myFICO for a short period before a big application, then cancel and return to free apps for routine monitoring.
- FICO scores from all three bureaus on paid plans
- Industry specific scores for mortgages and auto loans
- Score simulator and identity protection on paid plans
- Paid plans cost $29.95 or $39.95 per month in reported 2026 pricing
- Free plan is limited
- Updates on the basic paid plan are quarterly, not monthly
Credit Sesame is a solid free alternative if you want more guidance than a score alone. It explains factors affecting your score and suggests actions, such as lowering utilisation or disputing an error, in terms tied to your report. That coaching element helps people who are new to credit and unsure what to do next.
Credit Sesame covers only TransUnion on the free plan, so pair it with Credit Karma or Experian for broader coverage. Paid tiers add three bureau scores and identity features, but check whether you need them before upgrading, since free apps already cover much of the same ground.
- Free VantageScore from TransUnion
- Credit building tips tied to your report
- Paid tiers add three bureau monitoring
- Free plan covers only one bureau
- Paid tiers add cost quickly
- Recommendations include partner product offers
NerdWallet suits people who want credit tracking inside a wider money app. You can check your score, review accounts and read explanations of how credit works without switching apps. That breadth helps if you are also comparing cards, savings accounts or loans and want one place to start.
As a pure credit monitor, NerdWallet is thinner than Credit Karma, because it covers one bureau and updates less often. It is best as a companion app for money planning, with Credit Karma or Experian handling routine score alerts.
- Free VantageScore from TransUnion
- Budgeting and account tools in the same app
- Clear explanations of credit factors
- Only one bureau on the free score
- App includes financial product recommendations
- Score updates are less frequent than some rivals
CreditWise from Capital One is a useful free FICO option that does not require you to be a Capital One customer. It shows a FICO Score 8 based on TransUnion data and includes a simulator, which helps you test the effect of paying down debt or opening an account before you act. Weekly updates keep the trend visible without daily noise.
CreditWise covers only TransUnion, so it will miss changes at the other bureaus. Use it as a second FICO source alongside Experian, and remember that a simulator shows a possible direction, not a guaranteed score change.
- Free to use without a Capital One account
- FICO Score 8 from TransUnion data
- Simulator and weekly updates in reported coverage
- Only TransUnion coverage
- Fewer identity features than paid rivals
- Simulator is an estimate, not a lender decision
Kikoff is for people with little or no credit history who need a reported payment record. Its credit builder account reports payments to the bureaus, which can help establish a history of on time payments over time. The entry price is lower than many paid monitoring apps, which makes it accessible for a first step.
Kikoff will not fix credit overnight, and missed payments on a builder product can hurt rather than help. It is best for someone who can commit to small, regular payments for several months and who understands that utilisation, late payments and inquiries also affect the score.
- Low entry price for a credit builder account
- Payments reported to bureaus
- Weekly report access on some plans
- Credit builder product is not a traditional loan
- Higher tiers cost more
- Building credit takes months of on time payments
Aura suits households where credit monitoring is part of a wider identity protection need. It combines three bureau credit monitoring with dark web scans, VPN and antivirus on some plans, and identity theft insurance, which free score apps do not offer. Family plans can cover several people under one subscription.
Aura is not a good value pick if you only want a score. Free apps cover that need, and Aura paid plans make sense only if you also want identity monitoring, fraud resolution support and insurance. Check the plan terms for what is insured and what is excluded before subscribing.
- Three bureau monitoring on paid plans
- Dark web monitoring and identity theft insurance on many plans
- Family plans available
- Paid only for full features
- Price is higher than free score apps
- Credit tools alone do not justify the cost if identity protection is not needed
WalletHub is a good free choice if you like checking your score often. Daily updates show changes faster than weekly apps, and alerts flag new accounts or inquiries on your TransUnion report. That frequency helps if you are actively rebuilding credit and want to see the effect of payments and disputes.
WalletHub covers only TransUnion for free, and its score uses VantageScore, so it should not be your only source before a loan application. Pair it with Experian for a FICO view, and treat daily movement as noise unless a report item actually changes.
- Free VantageScore from TransUnion
- Daily updates in reported coverage
- Credit monitoring alerts
- Only TransUnion on the free plan
- Site includes many partner offers
- Score is VantageScore, not FICO
How we picked these
We compared official feature pages, pricing pages, app store listings, privacy policies and public reviews, and we weighted score type, bureau coverage, update frequency, alerts, identity features and price. We mixed free and paid apps so readers can start free and upgrade only for a clear reason, such as three bureau FICO scores or identity protection.
We did not claim hands on testing of every paid plan. Where prices differed between sources, we used the most consistently reported figures and marked uncertain prices as See website, so readers verify the current plan on the vendor site before subscribing.
How to use credit apps without confusion
Start by learning which score and bureau each app shows, and write it down. A VantageScore from TransUnion, a FICO Score 8 from Experian and a lender specific FICO score can all differ for the same person on the same day, and none of them is wrong. Track the trend inside each app, rather than comparing numbers across apps as if they were the same score.
Check your full reports, not just scores
Scores summarise reports, but errors live in the reports themselves. Get your free reports from AnnualCreditReport.com, check names, accounts, balances and payment history, and dispute errors with the bureau that holds the wrong item. An app alert can tell you something changed, but only the full report shows what changed and why.
Protect your login and personal data
Credit apps hold sensitive personal data, so use a strong unique password, turn on two factor authentication where offered, and check what data the app shares with partners. Free apps often earn money from product offers, so review privacy settings and opt out of marketing data sharing where the app allows it.
Frequently asked questions
What is the best app to check credit score for free?
Credit Karma and Experian together are the best free combination, because Credit Karma covers TransUnion and Equifax with VantageScore, while Experian adds a free FICO Score 8. CreditWise and WalletHub are good additional free sources, but each covers only one bureau, so use more than one app for broad coverage.
Is VantageScore or FICO better?
Neither is better in general. VantageScore is used by many free apps and some lenders, while FICO scores are used by most top lenders for mortgage, auto and card decisions. Check which model your lender uses if you are applying soon, and track the same model over time for a consistent trend.
Does checking my credit score hurt my score?
No. Checking your own score through an app or a bureau is a soft inquiry and does not lower your score. Applying for a card or loan can create a hard inquiry, which may lower your score by a few points for a short time. Multiple rate shopping inquiries for a mortgage or auto loan in a short window are often treated as one inquiry by scoring models.
How often should I check my credit score?
Monthly checks are enough for most people, with more frequent checks if you are rebuilding credit, disputing an error or preparing for a loan. Daily apps can create anxiety from small movements that reflect reporting timing, not real change. Focus on report accuracy and on time payments, which matter more than daily score noise.
Can an app improve my credit score?
An app alone cannot raise your score. It can help you spot errors, track utilisation and payment history, and simulate the effect of actions, but the score only improves when your report improves: on time payments, lower balances, and time without new negative items. Credit builder products can help only if payments are made on time.
What should I do if I find an error on my credit report?
Dispute the error with the bureau reporting it, and keep copies of your dispute and supporting documents. The bureau must investigate, and you can also contact the creditor that supplied the wrong information. Check all three bureau reports, since an error on one report may not appear on the others.
Sources we checked (9)

Online Jobs is an independent blog about careers, online work, learning new skills and the tools that help people earn. More about us.
Keep reading
All posts
Best Trading Apps for Beginners
Compare the best trading app for beginners, with $0 stock commissions, fractional shares, education, paper trading and account types explained in 2026 now.
Best Trading App
We compared the best trading apps for beginners and active traders on fees, tools, accounts and ease of use, so you can pick a platform that fits your plan.
Best Tax Software
Compare the best tax software in 2026 for simple returns, investors, freelancers, and preparers, with free options, state fees, and honest limits for filing.