Best Term Life Insurance Companies in 2026: 9 Options Compared
 Online Jobs·Updated Oct 24, 2026·12 min read

Online no-exam coverage you can reduce over time · Starting price: From $5 per month (sample quote)
How we put this together: we compare official feature and pricing pages, app store listings, privacy policies and public user reviews. Prices change, so check the provider's site before you pay.
Key takeaways
- Term life insurance prices are quoted per person, so almost no company publishes a fixed price. The published examples we found are samples, such as Ladder's $5 a month and Fabric's $7.85 a month for young, healthy applicants.
- Term lengths range widely. Banner Life lists 10 to 40 years, Ethos 10 to 40, Ladder and Fabric 10 to 30, and State Farm's Select Term 10, 20 or 30.
- Ladder and Ethos say no medical exam is needed for term coverage up to $3 million, based on health questions. Approval and price still depend on your answers.
- State Farm and Northwestern Mutual both state that you can convert term coverage to permanent insurance without a health check. Conversion rules and deadlines differ, so read them first.
- Bestow no longer sells term life to consumers directly, so we left it out. Its site says it now sells software to carriers.
Quick comparison
| Name | Who it suits | Starting price | Free option | |
|---|---|---|---|---|
| Ladder | Online no-exam coverage you can reduce over time | From $5 per month (sample quote) | No (free quote) | Visit |
 Banner Life | Long terms and high coverage amounts | As low as $8 per month (company claim) | No (free quote) | Visit |
 State Farm | Buying through a local agent | See website | No (free quote) | Visit |
 Northwestern Mutual | Advisor-led planning and guaranteed conversion | See website | No (free quote) | Visit |
 New York Life | Agent-based term with conversion options | See website | No (free quote) | Visit |
 Mutual of Omaha | Return of premium options | See website | No (free quote) | Visit |
 Fabric by Gerber Life | Parents who want a quick online application | From $7.85 per month (sample quote) | No (free quote) | Visit |
 Ethos | Fast online quotes from several carriers | See website | No (free quote) | Visit |
 Policygenius | Comparing many insurers in one place | See website | No (free quote) | Visit |
The best term life insurance companies
This article is general information, not insurance, legal or financial advice. Term life insurance pays a set amount to your beneficiaries if you die during the term, and nothing if you outlive it unless you buy a return of premium version. Your price depends on your age, health, tobacco use, location and coverage amount, so confirm every detail with the insurer or a licensed agent before you apply. We have not ranked these by price, because a fair price needs a quote for you.
Ladder sells term life online and focuses on a feature it calls laddering, where you reduce coverage as your needs fall. Terms run 10 to 30 years. Policies up to $3 million need only health questions, and larger amounts may need a free at-home health check.
Ladder's page shows prices starting at $5 a month, but that sample is for a 20-year-old with a $100,000, 10-year policy in the Preferred-Plus class, valid as of April 2026. Expect a different number for you. Policies are issued by Amica Life, Fidelity Security Life and S.USA Life, and each insurer is responsible for its own claims.
Availability is the main limit. Amica and Fidelity cover all states except New York, and S.USA excludes New York and Connecticut too. You can cancel within 30 days for a full refund and later with no cancellation fee. The policy may not pay for death by suicide or fraud.
- Terms from 10 to 30 years
- Up to $3M with health questions only
- Cancel within 30 days for a full refund
- Not sold in New York
- Sample prices are for young, healthy applicants
Banner Life, part of the Legal & General America family, has one of the widest ranges of term lengths on this list: 10, 15, 20, 25, 30, 35 or 40 years, with 20 years the most common. Coverage starts at $100,000 and goes beyond $10 million, and the company covers ages 20 to 75.
At the end of the term you can renew or convert to a permanent policy. Optional riders include extra term coverage, a child rider that covers children to age 25, and an accelerated death benefit for a qualified terminal illness on policies effective 2011 or later, subject to availability.
Banner advertises term insurance for as little as $8 a month, with no conditions on that page, and it says quotes depend on age, gender, health, location, coverage amount and length. Use the online quote tool or ask an agent.
- Terms of 10 to 40 years
- Coverage from $100,000 to more than $10 million
- Ages 20 to 75
- Quotes depend on your details
- Sold with agent support
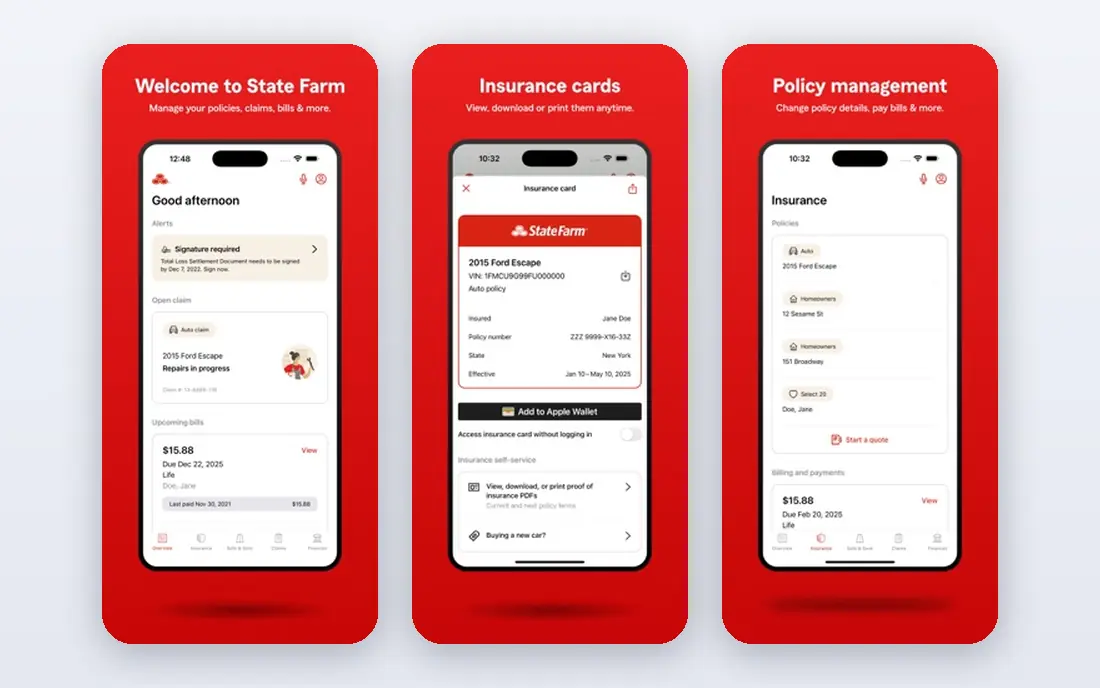
State Farm's Select Term comes in 10, 20 and 30-year versions. Issue ages are 18 to 75 for the 10-year term, 18 to 65 for the 20-year term and 18 to 45 for the 30-year term. Coverage starts at $100,000.
After the level period, coverage can continue year to year to age 95 at rising premiums, which cannot exceed the maximum stated in your policy. State Farm says you can convert to permanent coverage regardless of health, with conversion options varying by state.
It also sells Return of Premium Term with a 20 or 30-year level period. If no death benefit has been paid and you have paid every premium, those premiums are returned at the end of the term. Issue ages for the 20-year version run to 60 for non-tobacco users and 55 for tobacco users. You can start a quote online or contact an agent.
- Select Term in 10, 20 or 30 years
- Convert to permanent without a health check
- Return of premium option
- 30-year term only up to age 45
- Prices need a quote
Northwestern Mutual
Who it suits: Advisor-led planning and guaranteed conversion
Northwestern Mutual offers term life for 10 years, 20 years or to age 80. It also offers annual renewable term, which costs less at first but rises every year, and level premium term, which keeps the same premium for the term.
You can convert some or all of a term policy to whole life with guaranteed approval regardless of health, and waiting makes the premiums more expensive. A waiver of premium rider lets you stop paying during a qualifying disability while keeping coverage.
The company shows one example: for a healthy 35-year-old in the premier class buying $500,000 of coverage to age 80 with the waiver rider, the first-year premium is about $253 a year for a woman and $306 for a man, and it increases annually. The page repeatedly points readers to an advisor for quotes, so this is a conversation, not a checkout page.
- Guaranteed conversion to whole life
- Level and annual renewable options
- Waiver of premium rider
- Quotes go through an advisor
- Sample prices rise every year on renewable term
New York Life sells level term that locks in premiums for 10, 15 or 20 years, plus yearly renewable term with premiums that start low and rise each year. Its page says term policies can often be converted to permanent coverage, and conversion windows vary by product, with some at ten years and others at five.
Riders include a disability waiver of premium, a spouse paid-up purchase option and a living benefit for terminal illness. The living benefit has a cost and is not available in every state.
You buy through a financial professional. The company says it has more than 12,000 agents and advisors, and you can search by ZIP code or request a call. That works for people who want guidance, though the page does not list coverage amounts or issue ages.
- Level term for 10, 15 or 20 years
- Often convertible to permanent coverage
- 12,000+ agents and advisors
- Coverage amounts and ages not listed
- No online checkout
Mutual of Omaha's Term Life Express offers level terms of 10, 15, 20 and 30 years, and the 20 and 30-year versions have return of premium options. Policies are underwritten by United of Omaha Life Insurance Company, and by Companion Life in New York.
The site notes that features and availability vary by state. It also states the standard suicide exclusion: if the insured dies by suicide within two years of issue, the premiums paid are returned instead of the death benefit.
Return of premium costs more than plain term, so compare the refund with what you could earn by saving the difference. The company's pages do not show prices, so request a quote or contact an agent.
- Term Life Express in 10, 15, 20 and 30 years
- Return of premium on 20 and 30-year terms
- Wide product range
- Coverage amounts and ages not on the page we read
- Availability varies by state
Fabric by Gerber Life
Who it suits: Parents who want a quick online application
Fabric is Gerber Life's digital brand, aimed at families. Its page lists terms of 10 to 30 years and coverage from $100,000 to $5 million. The advertised starting price of $7.85 a month assumes a 25-year-old woman with $100,000 of coverage, so treat it as a sample.
The company says you could get instant coverage with no medical exam if you qualify, and that the application can take as little as 10 minutes. It also promises a price lock as long as premiums are paid, a 30-day money-back guarantee, cancellation at any time and no hidden fees.
Fabric also offers an app, a will tool and an investing account for children. If you want one place for family finances, that is a plus. If you want to compare many insurers, start elsewhere.
- 10 to 30-year terms
- Coverage from $100K to $5M
- 30-day money-back guarantee
- Sample price is for a 25-year-old woman
- No medical exam only for qualified applicants
Ethos offers policies from multiple carriers and says most people get an instant quote. Term policies run 10 to 40 years for up to $3 million, applicants must be 20 to 85 for its products, and term life is open to people 69 or younger.
No medical exam is required. You answer health questions online, and many applicants can get same-day coverage in as little as 10 minutes, according to Ethos. Applying is free and does not affect your credit score.
Ethos is licensed in 49 states and D.C., with New York the exception. Product options depend on age, state and product, and the page does not name its carriers, so check which insurer issues your policy before paying.
- Terms of 10 to 40 years
- No medical exam, health questions online
- Licensed in 49 states plus D.C.
- Not available in New York
- Term life only to age 69
Policygenius is a licensed independent insurance broker, so it does not issue policies. It lets you compare quotes from multiple insurers in one place, and licensed agents are available. Its page defines term life as coverage for a set period, usually 10 to 40 years.
Quotes are free, but premiums shown are non-binding estimates. The insurer sets the final premium after underwriting, so the price can change.
The page we read did not explain how Policygenius is paid and did not list the states it serves, so check both before you start. Comparing options is its main benefit.
- Compares quotes from multiple insurers
- Licensed agents answer questions
- Free to use
- A broker, not an insurer
- Shown premiums are non-binding estimates
How we picked these
We compared official product pages, quote tools, term and coverage details, conversion rules and riders, and we selected a mix of large insurers, digital sellers and one broker. We did not buy policies or test quote tools, and we did not rank by price. Where a company did not publish a figure on pages we could read, we wrote See website. Check financial strength ratings from rating agencies such as AM Best before you buy.
How to choose term life insurance
Pick a term that covers your biggest obligations
Many people choose a term that lasts until the mortgage is paid or the youngest child is independent. A 20 or 30-year term is common for families, and shorter terms suit short-term debts. Longer terms cost more per month but lock in your rate for longer.
Decide how much coverage
A common rule of thumb is to multiply income by 10 or more, then adjust for debts, savings and dependents. It is only a starting point. Use the insurer's calculator or talk to an agent.
Weigh no-exam against full underwriting
No-exam policies are faster, but healthy applicants may pay less after a full exam. Ladder and Ethos use health questions. Traditional insurers may ask for an exam depending on your age and the amount, so ask each one.
Read the conversion and renewal rules
Conversion lets you switch to permanent coverage later without a new health check, but deadlines apply. After the term, premiums on renewable coverage rise steeply.
Check the free-look period
Many policies let you cancel shortly after purchase. Ladder offers 30 days for a full refund, and Fabric offers a 30-day money-back guarantee.
Frequently asked questions
Which company has the best term life insurance?
It depends on your age, health and needs. Ladder and Ethos are quick online options, Banner Life offers long terms and high limits, and State Farm and Northwestern Mutual add agent or advisor support. Compare quotes for the same coverage.
How long should my term be?
Match it to the years your family relies on your income. Banner Life lists up to 40 years, State Farm's longest is 30, and the 30-year version is only available through age 45.
Can I get term life insurance without a medical exam?
Yes. Ladder says no exam is needed up to $3 million and Ethos says no exam is required. Both rely on your answers to health questions, so answer them accurately.
What happens when my term ends?
Coverage ends unless you renew, which usually costs much more, or convert to permanent insurance. Return of premium plans, such as State Farm's and Mutual of Omaha's, refund the premiums if you outlive the term.
Is term life cheaper than whole life?
Term coverage is generally lower in cost than permanent policies because it expires. Prices vary by person, so ask for both quotes.
Sources we checked (14)
- https://www.ladderlife.com/
- https://www.bannerlife.com/
- https://www.bannerlife.com/life-insurance/term
- https://www.statefarm.com/insurance/life/term-life/select-term
- https://www.statefarm.com/insurance/life/term-life/return-of-premium
- https://www.northwesternmutual.com/life-insurance/term-life-insurance/
- https://www.newyorklife.com/
- https://www.newyorklife.com/products/insurance/term-life
- https://www.mutualofomaha.com/life-insurance
- https://www.mutualofomaha.com/life-insurance/term-life-insurance
- https://meetfabric.com/term-life-insurance
- https://www.ethos.com/
- https://www.policygenius.com/life-insurance/
- https://www.bestow.com/
Online Jobs is an independent blog about careers, online work, learning new skills and the tools that help people earn. More about us.
Keep reading
All posts
Best Personal Loan Companies
Compare the best personal loan companies in 2026, including Discover, Wells Fargo, Upgrade, Best Egg and Avant, with APR ranges, fees, loan amounts and credit fit.
Best Insurance Companies
Which is the best insurance company for car coverage in 2026? Eight major insurers compared on discounts, driving programs, agents and J.D. Power results.
Best Cash Advance Apps
Compare the best cash advance apps in 2026, from EarnIn, Dave and MoneyLion to Chime MyPay and Varo, with limits, fees, tips and who each one suits.