Best Financial Advisor Companies in 2026: 9 Companies Compared

Low-cost human advice for most investors · Starting price: See website
How we put this together: we compare official feature and pricing pages, app store listings, privacy policies and public user reviews. Prices change, so check the provider's site before you pay.
Key takeaways
- Vanguard Personal Advisor leads on low-cost human advice for most investors.
- Fidelity and Schwab suit buyers who want advice inside a broad brokerage and banking service.
- Betterment Premium suits goal-based planning with human access.
- Facet suits complex planning on a flat fee, while Garrett suits hourly one-off advice.
- Compare total cost on your own balance, including fund expenses, before choosing.
Quick comparison
| Name | Who it suits | Starting price | Free option | |
|---|---|---|---|---|
| Vanguard Personal Advisor | Low-cost human advice for most investors | See website | No | Visit |
 Fidelity Wealth Services | Advice inside a broad brokerage | See website | No | Visit |
 Charles Schwab Wealth Advisory | Advice with banking and brokerage together | See website | No | Visit |
 Betterment Premium | Goal-based advice with human access | See website | No | Visit |
 Wealthfront | Low-cost automated investing | See website | No | Visit |
 Empower Wealth Management | Advice plus a full net-worth dashboard | See website | No | Visit |
 Facet Wealth | Flat-fee planning for complex finances | See website | No | Visit |
 Edelman Financial Engines | Advice for workplace retirement savers | See website | No | Visit |
 Garrett Planning Network | Hourly fee-only advice without asset minimums | See website | No | Visit |
The best financial advisor companies
Advisor firms look similar on a homepage and differ sharply on fees, minimums, and how much human help you actually get. The right firm matches your balance, goals, and how involved you want to be.
Vanguard Personal Advisor
Who it suits: Low-cost human advice for most investors
For investors with at least a moderate balance who want low-cost advice, Vanguard Personal Advisor is a strong starting point. The core strength here is cost, with index portfolios and human advice at a lower fee than many traditional advisors. That combination makes it a sensible shortlist entry for buyers who want that specific strength without paying for a much larger platform.
The honest catch is that the minimum balance rules out smaller accounts, so check eligibility before planning around it. Check the current pricing page and free plan limits on your own device before you commit, since plans and limits change. We think it earns its place here because it solves a clear job well, even if it is not the right fit for every buyer.
- Low advisory fee relative to traditional firms
- Index-oriented portfolios
- Access to human advisors
- Minimum balance applies
- Service is less tailored than a private wealth firm
Fidelity Wealth Services
Who it suits: Advice inside a broad brokerage
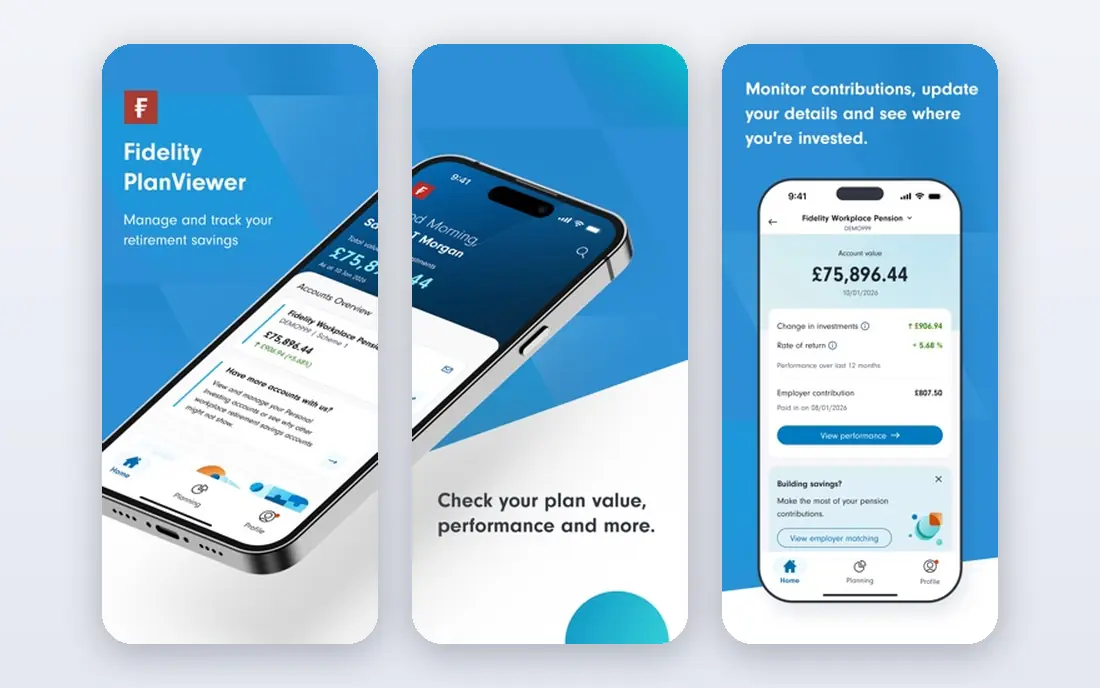
If you need existing Fidelity customers who want advice plus a full brokerage, Fidelity Wealth Services deserves a close look. The main draw is breadth, with brokerage, retirement, and advice accounts under one login. That combination makes it a sensible shortlist entry for buyers who want that specific strength without paying for a much larger platform.
The honest catch is that fees and advice depth vary by tier, so ask which tier your balance qualifies for and what it includes. Check the current pricing page and free plan limits on your own device before you commit, since plans and limits change. We think it earns its place here because it solves a clear job well, even if it is not the right fit for every buyer.
- Wide account and fund choice
- Coaching and planning options
- Strong digital tools
- Fees vary by service tier
- Advice depth depends on the tier chosen
Charles Schwab Wealth Advisory
Who it suits: Advice with banking and brokerage together
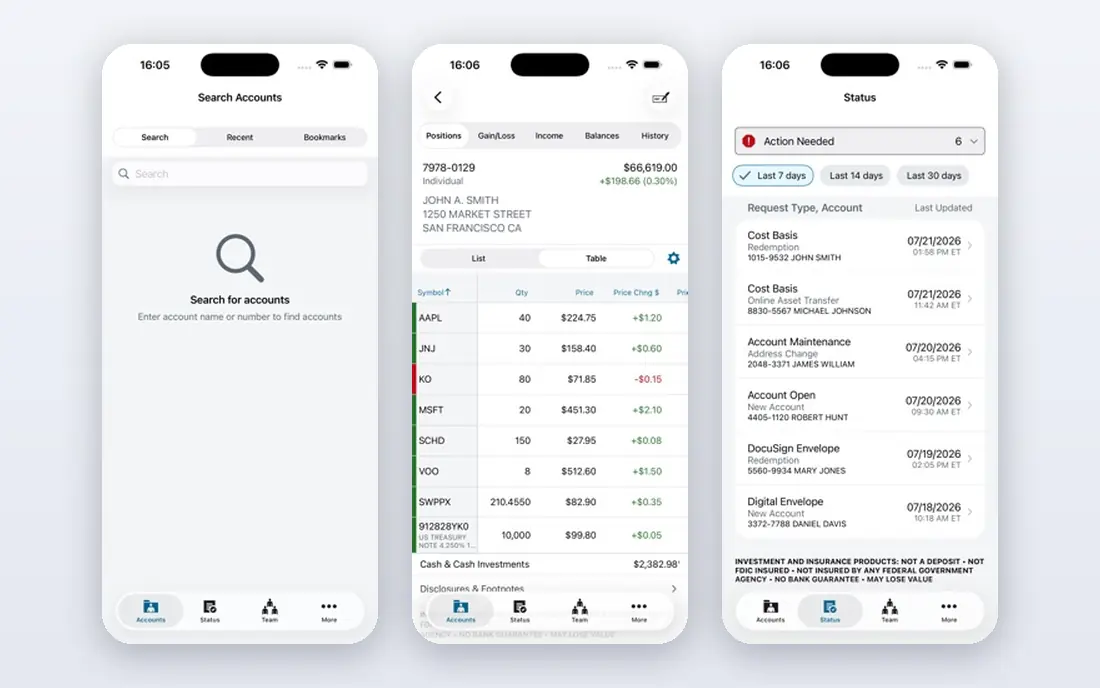
Charles Schwab Wealth Advisory fits investors who want brokerage, banking, and advice in one firm well, with a clear focus on what matters. In practice, buyers praise integration, with accounts, banking, and advice visible in one place. That combination makes it a sensible shortlist entry for buyers who want that specific strength without paying for a much larger platform.
The honest catch is that the cash allocation in automated portfolios can drag returns in strong markets, so ask how it is set. Check the current pricing page and free plan limits on your own device before you commit, since plans and limits change. We think it earns its place here because it solves a clear job well, even if it is not the right fit for every buyer.
- Broad brokerage and banking integration
- Automated portfolios plus human advice options
- Wide branch and phone support
- Advice tiers and minimums vary
- Automated portfolios hold a cash allocation
Teams looking for goal-based investors who want human advice on top of automation will find Betterment Premium a practical choice. What keeps users with it is planning, with goals, projections, and human advice combined in one account. That combination makes it a sensible shortlist entry for buyers who want that specific strength without paying for a much larger platform.
The honest catch is that the Premium fee adds up over years, so weigh it against the value of the human advice you will actually use. Check the current pricing page and free plan limits on your own device before you commit, since plans and limits change. We think it earns its place here because it solves a clear job well, even if it is not the right fit for every buyer.
- Goal-based planning tools
- Automated tax-loss harvesting where eligible
- Human advisor access on Premium
- Premium fee is higher than digital-only plans
- Minimum applies for Premium
When hands-off investors who are comfortable with a digital-only service is the priority, Wealthfront stands out for a clear reason. What sets it apart is automation, with tax-loss harvesting and rebalancing handled without manual trades. That combination makes it a sensible shortlist entry for buyers who want that specific strength without paying for a much larger platform.
The honest catch is that if you want regular calls with a dedicated advisor, a hybrid service will fit better. Check the current pricing page and free plan limits on your own device before you commit, since plans and limits change. We think it earns its place here because it solves a clear job well, even if it is not the right fit for every buyer.
- Low advisory fee
- Automated tax-loss harvesting where eligible
- Simple digital onboarding
- Human advice is limited
- Planning tools are less personal than a dedicated advisor
Empower Wealth Management
Who it suits: Advice plus a full net-worth dashboard
Empower Wealth Management is built around investors who want a dashboard plus a dedicated advisor, and that focus shows in daily use. Where it earns its place is the dashboard, which gives a clear view of accounts, spending, and retirement progress in one place. That combination makes it a sensible shortlist entry for buyers who want that specific strength without paying for a much larger platform.
The honest catch is that the wealth fee is higher than a digital-only plan, so use the dashboard free tier first to test the fit. Check the current pricing page and free plan limits on your own device before you commit, since plans and limits change. We think it earns its place here because it solves a clear job well, even if it is not the right fit for every buyer.
- Free dashboard for net worth and spending
- Dedicated advisor on wealth plans
- Retirement planning tools
- Wealth fees are higher than robo-only services
- Minimum applies
For buyers who need high-income households with complex planning needs, Facet Wealth offers a direct route. Its clearest strength is flat pricing, which does not rise as your balance grows. That combination makes it a sensible shortlist entry for buyers who want that specific strength without paying for a much larger platform.
The honest catch is that the flat fee may cost more than a percentage fee on a small balance, so compare both on your own numbers. Check the current pricing page and free plan limits on your own device before you commit, since plans and limits change. We think it earns its place here because it solves a clear job well, even if it is not the right fit for every buyer.
- Flat annual fee rather than a percentage of assets
- Dedicated CFP professional
- Planning covers tax, estate, and insurance topics
- Flat fee can be high for small balances
- Investment management is part of a planning service
Edelman Financial Engines
Who it suits: Advice for workplace retirement savers
If workplace retirement savers who want help with a 401(k) and retirement income matters most, Edelman Financial Engines is worth testing first. The standout feature is workplace reach, with advice tied to employer plans and retirement income planning. That combination makes it a sensible shortlist entry for buyers who want that specific strength without paying for a much larger platform.
The honest catch is that fees and service depth vary by plan, so check what your employer plan includes. Check the current pricing page and free plan limits on your own device before you commit, since plans and limits change. We think it earns its place here because it solves a clear job well, even if it is not the right fit for every buyer.
- Workplace plan advice
- Retirement income planning
- Large advisor network
- Fees are higher than low-cost robo services
- Service varies by employer plan
Garrett Planning Network
Who it suits: Hourly fee-only advice without asset minimums
Garrett Planning Network suits people who need a one-off plan or a second opinion, with strengths that match that job. In daily use, the strength is hourly pricing, which suits a single question or a plan review without handing over assets. That combination makes it a sensible shortlist entry for buyers who want that specific strength without paying for a much larger platform.
The honest catch is that ongoing management is not the core offer, so it fits check-ins better than full portfolio management. Check the current pricing page and free plan limits on your own device before you commit, since plans and limits change. We think it earns its place here because it solves a clear job well, even if it is not the right fit for every buyer.
- Pay by the hour
- No asset minimum
- Fee-only advisors across the US
- Hourly cost adds up for ongoing help
- You manage investments yourself unless agreed
How we picked these
We compared firm pages, fee disclosures, minimums, and planning scope for each company. We favoured firms with clear fees, fiduciary advice where offered, and a service model that fits the balance stated. Fees and minimums change, so confirm terms in the advisory agreement before opening an account. This is not financial advice; investing carries risk, including possible loss.
We also weighed ease of setup, support quality, and how well each product fits its stated best use. A product that is strong in general but weak for the stated job did not make the list. Where a price or free tier could not be verified on a vendor page, we wrote See website rather than guessing a number.
How to choose an advisor firm without paying for help you will not use
Decide first whether you want a human advisor, a digital service, or a mix, since that choice drives cost more than brand. Compare total cost, including advisory fees and fund expenses, on your own balance, not just the headline rate. Ask what planning is included, such as retirement, tax, estate, and insurance, and how often you will speak to an advisor. Start with a trial conversation or a free dashboard where offered, and check whether you can leave without a large exit cost.
Make a short list of two or three options and test each one on a real task from your own work. Note setup time, daily friction, and total cost, including any paid tier you will actually need. The best choice is usually the one your team or household keeps using after the first week, not the one with the longest feature list.
Frequently asked questions
What company is the best financial advisor?
Vanguard Personal Advisor suits most investors who want low-cost human advice, while Fidelity and Schwab suit customers who want advice inside a broad brokerage. Betterment Premium suits goal-based planning, and Facet suits flat-fee planning for complex finances. Pick by fee, minimum, and how much human help you want.
How much do financial advisors charge?
Fees vary from a low percentage of assets for digital and hybrid services to higher percentages for traditional firms, plus flat fees and hourly rates for other models. Fund expenses sit on top of advisory fees. Compare total cost on your own balance and ask what is included.
Do I need a financial advisor for retirement planning?
Many investors can plan retirement with a low-cost portfolio and a clear savings plan, while complex tax, estate, or income questions often justify advice. A one-off hourly plan can answer a specific question without ongoing fees. Use an advisor when the decision is large, irreversible, or hard to judge alone.
What is the difference between a robo-advisor and a human advisor?
A robo-advisor automates portfolio management and rebalancing, while a human advisor adds personal planning, tax guidance, and behavioural support. Hybrid services combine both, with automation plus access to a person. Choose by how much personal guidance you want during market falls.
Can I switch advisor companies later?
Yes, you can usually transfer accounts, though the process, timing, and tax effects depend on account type and holdings. Taxable accounts need care, since selling holdings can trigger tax. Ask the new firm to handle the transfer and confirm any fees before you move.
Sources we checked (5)

Online Jobs is an independent blog about careers, online work, learning new skills and the tools that help people earn. More about us.
Keep reading
All posts
n8n Alternatives
n8n alternatives compared for 2026, with Zapier, Make, Activepieces, and more, covering visual builders, code steps, self-hosting, and pricing models.

eBay Alternatives
Looking for ebay alternatives? We compared 9 marketplaces for sellers on fees, buyer reach, categories and ease of listing, to help you sell with confidence.

ZoomInfo Alternatives
The best ZoomInfo alternatives in 2026, compared on price, free plans, data coverage, and which tool fits small teams or large sales teams best in detail.