Best Buy Now Pay Later Apps in 2026: 8 Apps Compared

Shoppers wanting Pay in 4, Pay in 30 and financing in one app · Starting price: Free
How we put this together: we compare official feature and pricing pages, app store listings, privacy policies and public user reviews. Prices change, so check the provider's site before you pay.
Key takeaways
- Pay in 4 is interest-free on every app here when you pay on time, but late fees and monthly plan interest differ sharply, so the cheapest app depends on how you pay.
- Affirm and PayPal Pay Later charge no late fees at all, while Klarna caps late fees at $7 and Afterpay at $8 per missed payment, each capped at 25% of the order.
- Sezzle is the only Pay in 4 app here that reports on-time payments to all three credit bureaus through its opt-in Sezzle Up feature.
- Splitit is the odd one out in a good way: it splits purchases on your existing credit card with no new loan, no credit check and no late fees.
- Perpay suits W-2 employees paid by direct deposit who want paycheck deductions, but it only works inside its own marketplace.
Quick comparison
| Name | Who it suits | Starting price | Free option | |
|---|---|---|---|---|
| Klarna | Shoppers wanting Pay in 4, Pay in 30 and financing in one app | Free | Yes | Visit |
 Affirm | Larger purchases with no late fees ever | Free | Yes | Visit |
 Afterpay | Everyday Pay in 4 with a simple schedule | Free | Yes | Visit |
 PayPal Pay Later | PayPal users wanting Pay in 4 or Pay Monthly | Free | Yes | Visit |
 Sezzle | Shoppers wanting to build credit from Pay in 4 | Free | Yes | Visit |
 Zip | Shopping anywhere Visa is accepted | Free | Yes | Visit |
 Splitit | Cardholders wanting installments without a new loan | Free | Yes | Visit |
 Perpay | W-2 employees wanting paycheck deductions | Free | Yes | Visit |
The best buy now pay later apps for every shopper
This is not financial advice. Buy now pay later plans are a form of credit: missing payments can mean fees, account restrictions and, on some plans, credit reporting. Only split a purchase you could afford to pay for outright, and read the plan terms at checkout before confirming.
Klarna is the most flexible BNPL app on this list. Pay in 4 splits a purchase into four interest-free payments over six weeks, Pay in 30 lets you settle the full amount within 30 days with no interest, and monthly financing covers larger purchases over 6 to 36 months.
The costs sit in the details. Pay in 4 and Pay in 30 are interest-free when paid on time, but a late fee of up to $7 can apply per missed payment, capped at 25% of the order, and monthly financing carries interest from 0% up to around 25% APR or higher depending on credit and merchant. For shoppers who want one app for everyday splits and occasional financing, Klarna is the broadest choice.
- Three payment options in one app
- Wide merchant acceptance
- Virtual card for in-store use
- Late fees up to $7 per missed payment
- Monthly financing APR can reach about 25% or more
Affirm stands out for one simple reason: it never charges late fees. Pay in 4 splits a purchase into four interest-free payments every two weeks, and monthly plans run from a few months up to 60 months, with rates from 0% to 36% APR depending on credit, merchant and purchase amount. Affirm shows the total amount you will pay before you confirm, and that number never increases, which makes longer plans easier to judge honestly.
The honest limit is the APR range: a longer plan at the top end is expensive credit, and Affirm plans may be reported to credit bureaus, so missed payments can still matter even without a late fee. For a larger purchase where you want cost certainty and no late-fee risk, Affirm is the strongest pick.
- No late fees, hidden fees or annual fees
- Pay in 4 at 0% APR
- Monthly plans up to 60 months
- Monthly plan APR can reach 36%
- Larger plans need an eligibility check and may require a down payment
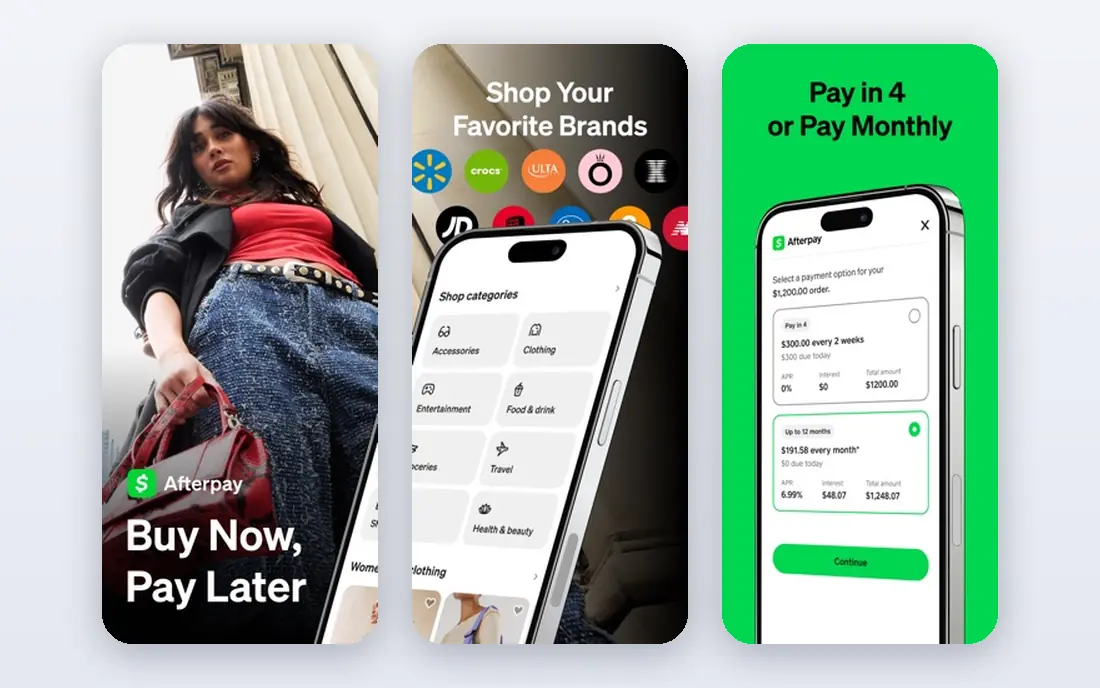
Afterpay keeps BNPL: Pay in 4 splits a purchase into four interest-free payments over about six weeks, with the first payment due at checkout and the rest every two weeks. The app shows amounts and dates before you confirm, sends reminders before payment. For larger orders, Pay Monthly covers 3, 6, 12 or 24 months with interest from 0% to 35.99% APR.
Late fees are the main cost to watch. A fee of up to $8 can apply per missed installment, generally after a grace period of about 10 days, with total late fees capped at 25% of the order, and your account is frozen from new purchases until the overdue payment is resolved. Pay Monthly is not available in Hawaii, Nevada, New Mexico or West Virginia. For everyday purchases where you want a predictable schedule and a well-known app, Afterpay remains a solid default.
- Simple Pay in 4 schedule
- Reminders before each payment
- Pay Monthly for larger orders
- Late fees up to $8 per missed payment
- Pay Monthly not available in some states
PayPal Pay Later gives existing PayPal users two options without a separate app. Pay in 4 covers purchases from $30 to $1,500 in four interest-free payments over six weeks, while Pay Monthly covers $49 to $10,000 in 3, 6, 12 or 24 monthly payments with a fixed APR from 9.99% to 35.99%. Both plans charge no late fees and no sign-up fees, and early payoff carries no penalty, which is a cleaner fee structure than most rivals.
The catch is availability. Pay Later appears at millions of online merchants where PayPal is accepted, but it may not show up at a specific checkout, for a specific fare class or for a very low promotional price, so it works best as a helpful option rather than a guaranteed funding plan. For shoppers who already pay with PayPal, this is the lowest-friction BNPL choice.
- No late fees or sign-up fees on either plan
- Accepted at millions of PayPal merchants
- Purchase Protection on eligible items
- Pay Monthly APR can reach 35.99%
- Pay Later may not appear at every checkout
Sezzle splits purchases into four interest-free payments over six weeks, with 25% due upfront and the rest every two weeks, and it works at more than 47,000 partner stores plus anywhere Visa is accepted through its virtual card. The basic account is free, with no sign-up or annual fees, and a free reschedule per order gives you a safety net if a due date slips. Paid tiers add unlimited virtual card access: Sezzle Premium from $12.99 a month and Sezzle Anywhere with waived service fees and 1% back on non-BNPL purchases.
Sezzle Up is the feature that sets Sezzle apart. Opting in reports your on-time Pay in 4 payments to TransUnion, Equifax and Experian, which can help build a thin credit file, though late payments are reported too, so only opt in when you are confident about every due date. For shoppers who want BNPL to also build credit, Sezzle is the clear pick.
- Pay in 4 at 0% interest
- Sezzle Up reports on-time payments to all three bureaus
- Free reschedule per order
- Late fees up to $10 and a $6.95 failed payment fee
- Virtual card purchases can carry a small service fee
Zip, formerly Quadpay in the US, splits purchases into 2, 4 or 8 payments every two weeks with no interest, and its biggest advantage is acceptance. The app generates a one-time virtual Visa card, so you can use Zip at any merchant that accepts Visa, including grocery stores, gas stations and independent retailers that offer no BNPL option at checkout.
The cost catch is fees. Zip charges an origination or installment fee on many orders, reported in a range from about $1 per installment up to larger amounts on bigger purchases, and a late fee of up to $7 can apply on missed payments. That means Zip is rarely the cheapest option when Klarna, Afterpay or Affirm are available at the same merchant, but it is the most widely usable one. For a purchase at a store with no BNPL checkout, Zip is the practical way to split the cost.
- One-time virtual Visa card works at any Visa merchant
- Pay in 2, 4 or 8
- No hard credit check
- Origination or installment fees apply on many orders
- Limits can be slow to grow
Splitit works differently from every other app here: it splits a purchase using your existing credit card instead of creating a new loan. At checkout you choose a plan of 3 to 36 months, Splitit places a temporary authorization hold for the full purchase amount, charges the first installment immediately, then charges the rest monthly at 0% interest on retail plans. There are no applications, no credit checks, no late fees and no prepayment penalties, and your card rewards and purchase protection stay active.
The hold is the key constraint. You need enough available credit to cover the full purchase when you buy, even though you pay over time, and the hold only shrinks as installments are paid. If you carry a credit card balance month to month, your issuer's standard APR still applies to those charges, so Splitit is only truly free when you pay the card bill in full. For cardholders with available credit who want installments without another account, Splitit is the cleanest option.
- No credit checks, no new loan, no late fees
- Keeps card rewards and purchase protection
- Plans from 3 to 36 months
- Needs enough available credit for a full-amount hold
- Fewer merchants offer it at checkout
- Card interest applies if you carry a balance
Perpay is a closed-marketplace BNPL service built for W-2 employees. You shop Perpay's own catalog of electronics, home goods, appliances, clothing and furniture, and payments are deducted from your paycheck through direct deposit before the money reaches your bank. Marketplace purchases carry no interest, no fees and no late fees, and applying does not affect your credit score, which is why Perpay can approve shoppers that other BNPL apps turn down.
The limits are structural. You need full-time W-2 employment paid by direct deposit, so gig workers, freelancers and self-employed shoppers do not qualify, and you can only buy what Perpay stocks, with a spending limit up to $1,000 based on your paycheck. For eligible employees who want automatic payments they cannot forget, Perpay is a useful niche option, but it cannot replace a general BNPL app.
- No interest, no fees and no late fees on marketplace purchases
- No hard credit pull
- Payments come straight from your paycheck
- Only works inside Perpay's own marketplace
- Requires W-2 employment with direct deposit
- Spending limit up to $1,000
How we picked these
We compared official product pages, help centers, fee disclosures and public reviews for the leading BNPL apps, and we kept only services that are live and usable in October 2026. Pay in 4 terms, late fees, monthly plan APR ranges and credit check practices had to be stated by the provider or in a current comparison of provider terms, since BNPL fees change often and vary by state.
We weighted fee transparency, late-fee policy, credit reporting, merchant acceptance and the range of plans offered. That is why the list mixes general checkout apps with two specialists: Splitit for cardholders who want no new loan, and Perpay for employees who want paycheck deductions.
What to check before you choose
Count the total cost, not just the first payment
Pay in 4 looks free because the first payment is only 25% of the price, but late fees, origination fees and monthly plan interest change the total fast. Compare the full fee schedule for your plan: Klarna up to $7 and Afterpay up to $8 per late payment, Zip's per-order fees, and monthly APRs that can reach 36%.
Match the plan to your cash flow
Four payments over six weeks suit a purchase you can cover from the next two paychecks. A 12 or 24 month plan suits a larger purchase only if the APR is low and the monthly amount fits your budget for the whole term.
Decide whether credit building matters
Most Pay in 4 plans do not build credit on their own. Sezzle Up reports on-time payments to all three bureaus, Affirm may report plan activity, and Perpay+ reports marketplace payments, but late payments can be reported too.
Check acceptance before you rely on it
BNPL availability varies by merchant, product and purchase amount, and PayPal Pay Later or Zip may not appear at a given checkout. Confirm the option is offered for your exact purchase before counting on it, and keep a backup payment method ready.
Frequently asked questions
What is the best buy now pay later app?
For most shoppers, Klarna offers the widest choice of plans, Affirm offers the strongest fee promise with no late fees ever, and Afterpay offers the simplest Pay in 4 schedule. Sezzle wins for credit building, Splitit wins for cardholders who want no new loan, and PayPal Pay Later wins for existing PayPal users. The best app depends on your purchase size, your payment habits and where you shop.
Do buy now pay later apps charge interest?
Pay in 4 plans are interest-free when paid on time across all eight apps here. Interest appears on longer monthly plans: Affirm 0% to 36% APR, Afterpay Pay Monthly 0% to 35.99%, Klarna financing up to around 25% or more, and PayPal Pay Monthly 9.99% to 35.99%. Splitit retail plans and Perpay marketplace purchases charge no interest, though Splitit users still face their card issuer's APR if they carry a card balance.
Do buy now pay later apps affect your credit score?
Checking eligibility for Pay in 4 usually involves only a soft credit check, which does not affect your score. Longer monthly plans may involve a hard inquiry, and some plans report payment activity: Sezzle Up reports to all three bureaus, Affirm may report, and Perpay+ reports marketplace payments. Late payments that get reported can lower your score, so treat due dates seriously even on no-late-fee plans.
What happens if you miss a buy now pay later payment?
It depends on the app. Affirm and PayPal charge no late fees, while Klarna charges up to $7 and Afterpay up to $8 per missed payment, each capped at 25% of the order, and Zip charges a late fee of up to $7. Afterpay freezes new purchases until the overdue payment is resolved, and most apps send reminders before each due date. Sezzle offers a free reschedule per order, which is worth using before a payment fails.
Can you use buy now pay later in stores?
Yes, with the right setup. Klarna's virtual card works with Apple Pay and Google Pay, Afterpay offers Pay in 4 in-store at thousands of brands, Zip generates a virtual Visa card for any Visa merchant, and Splitit works in-store through participating merchants and wallets. Availability varies by store, so check the app for nearby locations before you go.
Are buy now pay later apps safe?
They are regulated financial products with real terms, not free money. The main risks are overspending because the first payment looks small, stacking multiple plans, and missing payments that bring fees or credit reporting. This article is not financial advice, and plan terms vary by state and merchant.
Sources we checked (12)
- https://www.klarna.com/
- https://www.affirm.com/
- https://www.afterpay.com/
- https://www.paypal.com/
- https://sezzle.com/
- https://zip.co/
- https://www.splitit.com/
- https://www.perpay.com/
- https://financer.com/personal-finance/buy-now-pay-later/
- https://luthersales.com/
- https://www.creditkarma.com/personal-loans/i/afterpay-review-no-interest-loan
- https://www.paypal.com/us/digital-wallet/ways-to-pay/buy-now-pay-later/furniture

Online Jobs is an independent blog about careers, online work, learning new skills and the tools that help people earn. More about us.
Keep reading
All posts
Who Is the Best Company to Get Travel Insurance
Compare the best travel insurance companies, including World Nomads, Allianz Travel, SafetyWing and AXA, with coverage types, limits and who each suits.
Top AI Financial Software
Searching for top AI financial software? We compared 9 AI finance tools for AP, spend, close, forecasting and bookkeeping to help teams choose wisely.
Quicken Alternatives
Compare the best quicken alternatives for Mac, Windows, and small business owners, from Monarch Money and YNAB to Copilot, Tiller, and Banktivity in 2026.