Best Wealth Management Companies in 2026: 9 Compared

Low cost human advice · Starting price: See website
How we put this together: we compare official feature and pricing pages, app store listings, privacy policies and public user reviews. Prices change, so check the provider's site before you pay.
Key takeaways
- Vanguard Personal Advisor suits low cost, index focused investors who want a human adviser at a modest percentage fee.
- Fidelity and Schwab suit investors who already bank or invest with them, because planning, accounts and advice sit in one place.
- Merrill, Morgan Stanley and Edward Jones suit investors who want a dedicated adviser and branch access, with higher fees and minimums to match.
- Betterment Premium and Empower suit goal based and dashboard led investors who want digital tools plus human advice.
- This article gives general information only and is not financial advice; investing carries risk, and the value of investments can fall as well as rise.
Quick comparison
| Name | Who it suits | Starting price | Free option | |
|---|---|---|---|---|
| Vanguard Personal Advisor | Low cost human advice | See website | No | Visit |
 Fidelity Wealth Services | All-round advice for Fidelity clients | See website | No | Visit |
 Schwab Intelligent Portfolios Premium | Hands-off advice with CFP access | See website | No | Visit |
 Merrill Wealth Management | Bank linked advice at Bank of America | See website | No | Visit |
 Morgan Stanley Wealth Management | Full service private wealth advice | See website | No | Visit |
 Edward Jones | Local branch advice and planning | See website | No | Visit |
 Ameriprise Financial | Comprehensive planning and advice | See website | No | Visit |
 Betterment Premium | Goal based digital advice | See website | No | Visit |
 Empower Wealth Management | Dashboard led advice and planning | See website | No | Visit |
The best wealth management companies
We compared firms that offer managed portfolios, financial planning and human adviser access in 2026, not only brokerage accounts. Fees, minimums and planning scope differ sharply, so we judged each firm on the investor it serves best.
Vanguard Personal Advisor pairs a low cost, index focused portfolio with access to a human adviser, which is why it tops many 2026 adviser guides. Published guides list a fee around 0.30 percent of assets under management and a minimum around $50,000, although you should confirm current terms on Vanguard site before applying. Portfolios use low cost Vanguard funds, and planning covers retirement, goals and tax aware investing.
The limit is complexity. Vanguard suits long term, index focused investors who want clear, low cost advice, but investors with complex estates, business holdings or concentrated stock may need a more bespoke private wealth firm. If low cost and simplicity matter most, and you meet the minimum, Vanguard is our first pick.
- Low percentage fee in published guides
- Index focused portfolios
- Human adviser access
- Minimum investment applies
- Less suited to complex estate or business planning at entry level
Fidelity Wealth Services
Who it suits: All-round advice for Fidelity clients
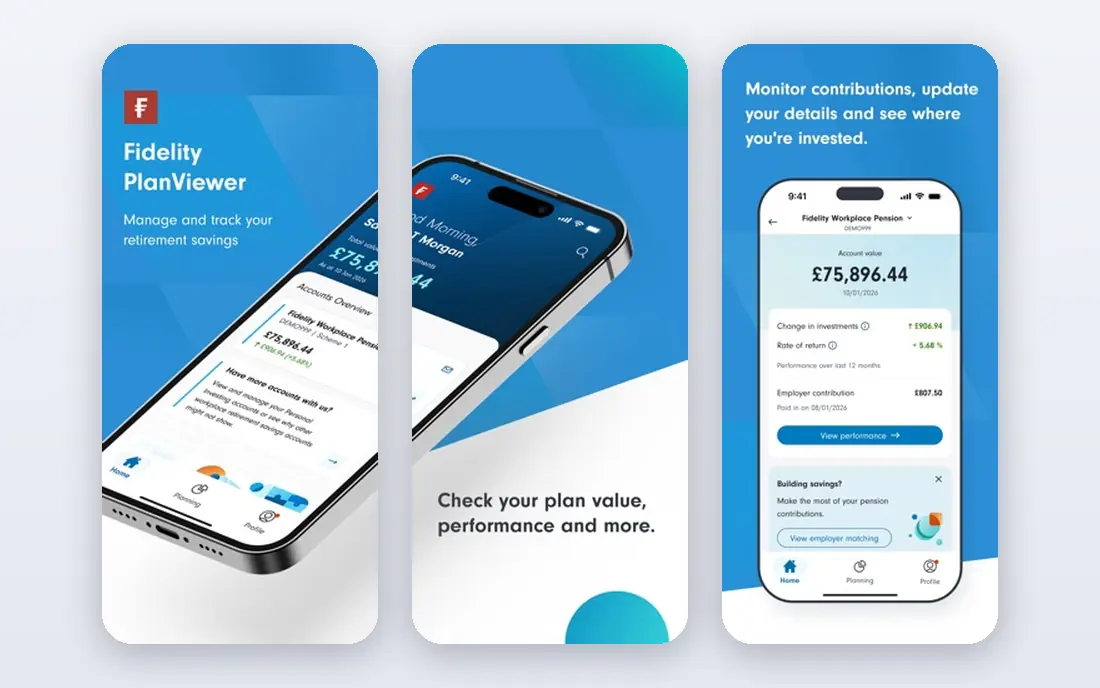
Fidelity Wealth Services covers a wide range, from Fidelity Go digital advice to full wealth management with a dedicated adviser. That range helps investors who start small and grow, because accounts, retirement planning, tax tools and managed portfolios can stay inside one firm. Fidelity research, fractional shares and zero expense index funds also support long term investors who want control alongside advice.
Fees vary by tier, with published guides listing a range from around 0.50 percent to 1.50 percent depending on service level and assets, so the exact cost depends on the tier you choose. Higher touch advice with a dedicated team costs more than digital advice. Fidelity fits existing Fidelity clients and investors who want a firm that can grow with them from digital advice to full planning.
- Broad account and planning range
- Strong research and tools
- Coaching and adviser tiers
- Fees vary by service tier
- Higher touch advice costs more
Schwab Intelligent Portfolios Premium
Who it suits: Hands-off advice with CFP access
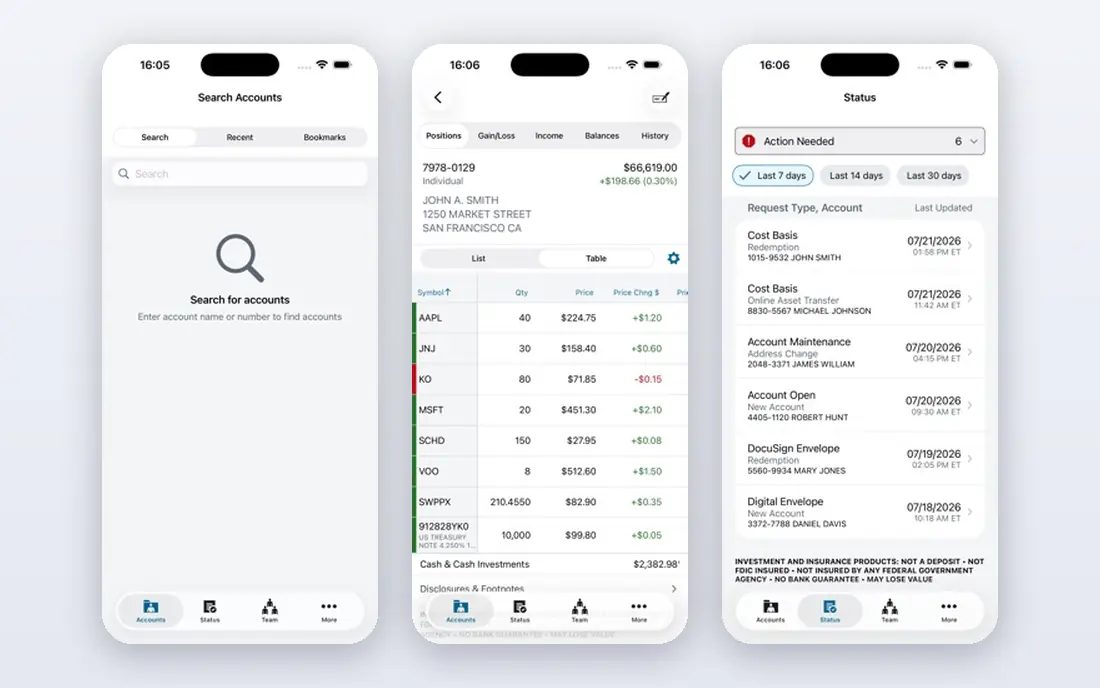
Schwab Intelligent Portfolios offers automated, diversified portfolios with rebalancing and tax-loss harvesting for eligible accounts, while Premium adds access to certified financial planners. Published guides list Premium at around $30 per month plus a one-time $300 planning fee, with a minimum around $25,000, although you should confirm current Schwab terms. That structure suits hands-off investors who still want a planner to talk to about goals.
The basic version charges no advisory fee but requires a cash allocation, which can drag returns in strong markets, and Premium costs more than a pure robo service. Schwab banking and brokerage links also help investors who want cash, investing and advice in one place. Schwab fits hands-off investors who value planner access without a full percentage fee firm.
- Automated portfolios
- Access to certified financial planners in Premium
- Schwab banking links
- Premium has a monthly fee and minimum
- Basic Intelligent Portfolios has a cash allocation requirement
Merrill Wealth Management
Who it suits: Bank linked advice at Bank of America
Merrill Wealth Management, part of Bank of America, suits clients who already bank with Bank of America and want investing, lending and planning in one relationship. Merrill Guided Investing offers digital advice with a lower minimum, while full wealth management pairs clients with an adviser for comprehensive planning. Preferred Rewards links can also add banking benefits for larger balances.
Full adviser service is aimed at higher asset clients, and fees vary by program, so smaller investors may start with Guided Investing. The bank link is a strength for clients who value one login and coordinated cash and investing, but it is less relevant if you bank elsewhere. Merrill fits Bank of America clients who want advice that sits close to their everyday banking.
- Links to Bank of America banking
- Merrill Guided Investing and adviser options
- Broad planning tools
- Full adviser service needs higher assets
- Fees vary by program
Morgan Stanley Wealth Management
Who it suits: Full service private wealth advice
Morgan Stanley Wealth Management is a full service firm for affluent and high net worth investors, with advisers, specialists and private banking links for complex needs. Planning can cover retirement, estate, tax, philanthropy, business succession and concentrated stock, supported by global research and lending options. For investors with complex balance sheets, that breadth matters more than a low headline fee.
Minimums and fees reflect that service level, and smaller investors will find better value at Vanguard, Fidelity or Schwab. Morgan Stanley also offers digital and workplace advice tiers for smaller balances, but its strength lies in full service advice. It fits investors with substantial assets and complex planning needs who want a dedicated team, not just a portfolio.
- Deep private wealth expertise
- Estate, tax and lending planning
- Global research
- High minimums for private wealth tiers
- Fees are higher than robo or low cost advisers
Edward Jones is built around local branches and face to face adviser relationships, with thousands of offices across the United States. That local presence suits investors who prefer to meet an adviser in person, discuss retirement and goals over time, and build a long term relationship in their community. Planning focuses on retirement, education, estate basics and income in retirement.
Fees are higher than digital or low cost advisers, and the quality of the relationship depends on the individual adviser, so meet the adviser before committing. Edward Jones also suits investors who want guidance to stay invested through market falls, with a person to call rather than an app alone. For local, personal advice, it remains a strong traditional choice.
- Thousands of local branches
- Face to face adviser relationships
- Long term planning focus
- Higher fees than digital advisers
- Branch experience varies by adviser
Ameriprise Financial emphasises comprehensive financial planning, with advisers who build a plan covering retirement, tax, estate, insurance and investment goals before choosing portfolios. That plan first approach suits investors who want advice on the whole financial picture, not only on asset allocation. Its adviser network offers both in person and virtual meetings, with digital tools to track the plan.
Fees vary by adviser, plan complexity and assets, and comprehensive planning can cost more than a portfolio only robo service. Investors who only need a managed portfolio may find better value elsewhere. Ameriprise fits investors who want a detailed plan, regular reviews, and an adviser who coordinates across retirement, tax and estate topics.
- Comprehensive financial planning focus
- Adviser network
- Retirement and estate planning depth
- Fees vary by adviser and plan
- Comprehensive planning can cost more than portfolio only advice
Betterment Premium pairs digital, goal based investing with access to human advisers, for investors who want automation plus a person to discuss big decisions. Published guides list Premium at around 0.65 percent of assets with a minimum around $100,000, while the digital plan is lower cost with a lower minimum, so confirm current Betterment terms for your balance. Goal tracking, retirement planning tools and tax-loss harvesting for eligible taxable accounts are core strengths.
The lack of branches is the main limit for investors who want face to face meetings, and Premium minimums exclude smaller investors. Betterment fits goal focused investors who are comfortable online, who want clear progress tracking, and who want adviser access for major life changes without a traditional firm fee structure.
- Goal based portfolios
- Tax-loss harvesting for eligible accounts
- Human adviser access in Premium
- Premium needs a higher minimum
- No branch network
Empower Wealth Management
Who it suits: Dashboard led advice and planning
Empower Wealth Management, formerly Personal Capital, combines a popular free dashboard for tracking accounts, net worth and retirement progress with a managed advice service. Published guides list managed fees from around 0.49 percent to 0.89 percent depending on assets, with a minimum around $100,000 for the managed service, so confirm current Empower terms. That dashboard first approach appeals to investors who like to see every account in one place.
The managed fee is higher than Vanguard or a pure robo service, and the free dashboard alone does not include advice. Empower fits investors who already track their wealth closely, who want a clear retirement plan, and who want an adviser to manage the portfolio while they monitor progress through the dashboard.
- Strong net worth dashboard and planning tools
- Human adviser access
- Retirement planning depth
- Higher minimum for managed service
- Fee range varies by assets
How we picked these
We compared fee guides, Form ADV summaries and vendor pages in October 2026, and we kept only firms with active managed advice, human adviser access and current public terms. We weighted total cost, minimums, planning scope, fiduciary status where published, technology and adviser access, because a low fee with no planning help is a different product from comprehensive advice. We used See website for starting prices where fees depend on assets, tier or negotiation, rather than presenting a single fee as universal.
We did not claim that any firm will outperform the market, and we treated published fee ranges as guides, not quotes. Investors should request a written fee schedule, a Form ADV Part 2A brochure, and a clear statement of conflicts and services before signing, and should compare at least two firms on the same asset level.
How to choose a wealth management company
Start with your assets, your planning needs and how much human contact you want, then match the firm to that profile.
Compare total cost, not just the advisory fee
Add the advisory fee to fund expense ratios, trading costs, planning fees and any account fees. A 0.30 percent adviser using low cost funds can cost less overall than a 0.65 percent adviser using higher cost funds, and a flat fee firm can be cheaper for large balances. Ask for a total cost example on your asset level, in writing, before you decide.
Check minimums, planning scope and adviser fit
Confirm the minimum, whether you get a dedicated adviser or a team, how often you meet, and what planning topics are included. Retirement, tax, estate, insurance, education and business planning are not included in every service, so list your needs first. Meet the adviser, ask how they are paid, and check whether they act as a fiduciary for your account.
Test the tools and the exit terms
Use the dashboard, reporting and planning tools during any trial or onboarding period, and check how easy it is to view holdings, fees and performance. Read the exit terms: transfer fees, account closure rules and how long a transfer takes. A good firm makes it easy to leave, because it expects to earn your business each year, not lock you in.
Frequently asked questions
Which wealth management company is the best?
There is no single best firm for every investor. Vanguard Personal Advisor suits low cost index investors, Fidelity and Schwab suit clients who want advice inside a large brokerage, and Morgan Stanley, Merrill and Edward Jones suit investors who want dedicated, full service advice. Match the firm to your assets, planning needs and preferred contact style.
What is the best wealth management company for low fees?
Vanguard Personal Advisor is often cited for low fees, with published guides listing around 0.30 percent, while Schwab Intelligent Portfolios charges no advisory fee on its basic tier, subject to a cash allocation. Betterment digital and Fidelity Go are also lower cost digital options. Compare total cost, including fund expenses, not only the advisory fee.
What are the best companies for wealth management for high net worth investors?
Morgan Stanley, Merrill, Ameriprise and Edward Jones offer full service planning for affluent investors, with estate, tax, lending and philanthropy support. Vanguard and Fidelity also offer higher tier advice for larger balances. High net worth investors should compare adviser teams, specialist access and planning depth, not only fees.
What are the best investment advisory services for beginners?
Digital advice from Fidelity Go, Schwab Intelligent Portfolios, Betterment and Vanguard Digital Advisor suits beginners with lower minimums and automated portfolios. These services handle diversification and rebalancing, while coaching or planner access helps with early questions. Start with a service that explains its portfolios clearly and charges a fee you understand.
Is wealth management worth the fee?
It can be, if the firm provides planning, tax aware investing, rebalancing and behavioural support that you would not do alone. It is less worthwhile if you only need a simple diversified portfolio and you will stay invested without advice. Compare the fee against the planning, tax and time value you actually receive, and review that value each year.
Does this article give financial advice?
No. This article gives general information only and is not financial advice. Investing carries risk, and the value of investments can fall as well as rise. Speak to a qualified, regulated adviser about your own circumstances before making investment decisions.
Sources we checked (9)

Online Jobs is an independent blog about careers, online work, learning new skills and the tools that help people earn. More about us.
Keep reading
All posts
Top AI Financial Software
Searching for top AI financial software? We compared 9 AI finance tools for AP, spend, close, forecasting and bookkeeping to help teams choose wisely.
Quicken Alternatives
Compare the best quicken alternatives for Mac, Windows, and small business owners, from Monarch Money and YNAB to Copilot, Tiller, and Banktivity in 2026.
QuickBooks Online Alternatives
Looking for quickbooks online alternatives? We compared 8 accounting tools on invoicing, bank feeds, payroll, pricing and fit for small businesses today.