Best Pay Later Apps in 2026: 10 Apps Compared

How we put this together: we compare official feature and pricing pages, app store listings, privacy policies and public user reviews. Prices change, so check the provider's site before you pay.
Key takeaways
- Pay in 4 plans are often interest-free when paid on time, but longer monthly plans can carry interest.
- Affirm suits larger purchases with longer terms, while Afterpay and Klarna suit smaller split payments.
- Late fees, interest and credit reporting vary widely, so read the terms for each plan, not just the app.
- Shop Pay and PayPal suit people who already shop or pay through those platforms.
- Split payments make budgeting easier only when the total fits your monthly income.
Quick comparison
| Name | Who it suits | Starting price | Free option | |
|---|---|---|---|---|
 Klarna | Flexible short and longer payment plans | Free | Yes | Visit |
 Affirm | Larger purchases over longer terms | Free | Yes | Visit |
 Afterpay | Simple four-payment shopping | Free | Yes | Visit |
 PayPal Pay Later | Pay later for existing PayPal users | Free | Yes | Visit |
 Sezzle | Budget shoppers who want payment flexibility | Free | Yes | Visit |
 Zip | Everyday purchases anywhere | Free | Yes | Visit |
 Splitit | Splitting payments on an existing card | Free | Yes | Visit |
 Shop Pay Installments | Split payments in Shopify stores | Free | Yes | Visit |
 Perpay | Shoppers with limited credit history | Free | Yes | Visit |
 Cash App Afterpay | Pay later inside Cash App | Free | Yes | Visit |
The best pay later apps
This guide compares ten pay later apps that split a purchase into smaller payments or spread it over months. We focus on plan types, fees, credit checks and where each app works, so you can pick a plan that fits the purchase rather than the checkout button.
Klarna suits shoppers who want choice at checkout. Short pay in 4 plans split a purchase into four payments, while longer financing covers bigger items over months. The app also tracks orders and payments in one place, which helps if you shop at several stores. The catch is that choice needs care. Longer plans may carry interest, and missing a payment can bring fees and affect credit reporting for some plans. Check the exact terms shown before you confirm, and keep the total of all open plans within what you can repay from one pay cycle.
- Pay in 4 and pay later options
- Longer financing at many retailers
- Wide store coverage
- Interest can apply on longer plans
- Late fees may apply
- Credit reporting varies by plan
Affirm suits larger purchases such as furniture, electronics and travel, where four payments would be too tight. It shows the total interest cost before you commit, which makes budgeting more honest, and many plans carry no late fees. That clarity is its main strength. The trade-off is interest. A longer term lowers the monthly payment but raises the total cost, and rates vary by retailer and credit profile. Compare the total cost with paying outright or saving for a month, and avoid stretching a term just to afford an item you do not need yet.
- Clear total cost shown before checkout
- Terms for larger items
- No late fees on many plans
- Interest can apply, with APR varying by purchase
- Credit check may apply
- Not available at every store
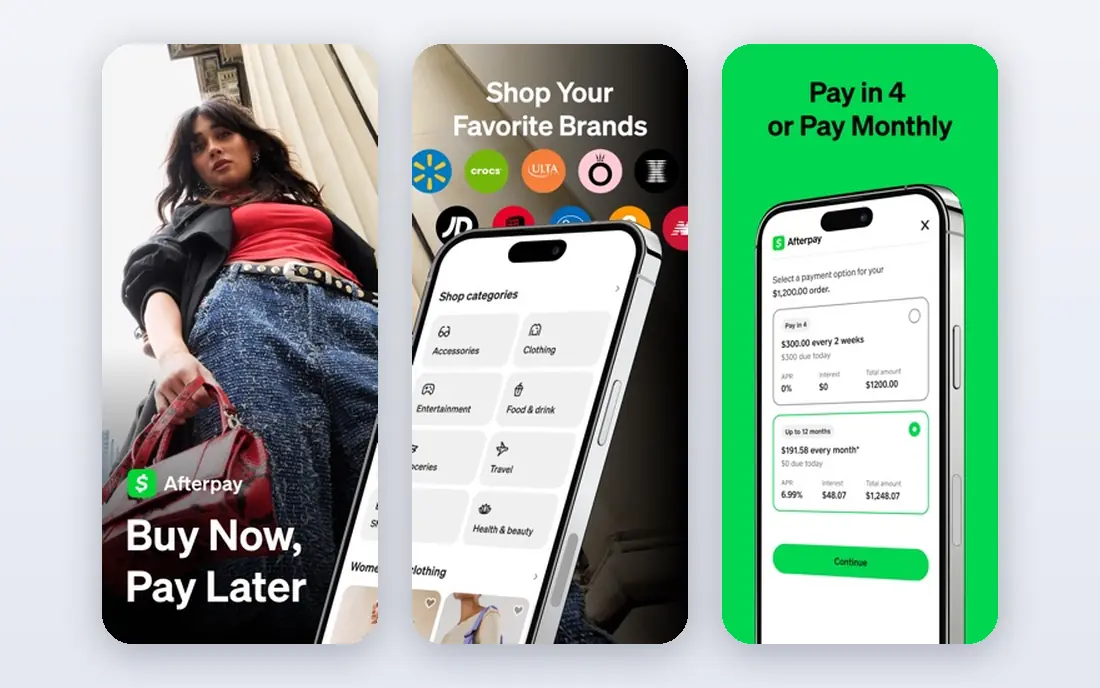
Afterpay suits regular shoppers who want a simple split. Four equal payments over six weeks keep the maths easy, and interest does not apply when you pay on time. It is widely available in fashion, beauty and lifestyle stores, both online and in some physical shops. The risk is stacking plans. Several small Afterpay orders can add up to a large monthly total, and late fees can apply if a payment fails. Set a personal cap for open plans, keep payment details current, and pause new orders if an existing payment is already tight.
- Four equal payments over six weeks
- Interest-free when paid on time
- Strong fashion and lifestyle coverage
- Late fees can apply
- Spending limits vary
- Some plans may affect credit reporting in some regions
PayPal Pay Later suits people who already pay with PayPal and do not want another app. Pay in 4 splits smaller purchases, while monthly plans cover larger ones at participating retailers. Payments sit inside the PayPal account you already check, which reduces forgotten bills. The catch is the split between plan types. Pay in 4 is usually interest-free when paid on time, but monthly plans can carry interest and different terms. Read the plan shown at checkout, note the limit for your purchase, and do not assume every PayPal purchase can be split.
- Pay in 4 for smaller purchases
- Monthly plans for larger ones
- Works where PayPal is accepted
- Monthly plans can carry interest
- Limits vary
- Late payment terms vary by plan
Sezzle suits shoppers who want a little more room when a payday shifts. The standard plan splits a purchase into four interest-free payments, and rescheduling options can help when a date moves by a few days. Some regions also offer a credit-building path for on-time payments. Fees and limits are the details to check. Rescheduling or premium features can carry charges, and spending limits depend on history and merchant. Treat Sezzle as a budgeting tool for planned purchases, not as a way to buy more than your income can cover.
- Four interest-free payments
- Options to reschedule
- Credit-building option in some regions
- Fees can apply for rescheduling or some plans
- Limits vary
- Credit-building features vary by region
Zip suits shoppers who want pay later beyond a short list of partner stores. Its virtual card approach lets you split purchases in more places, and the app keeps upcoming payments visible. For everyday items that are easier in four parts, that reach is useful. The cost is in the small print. Some plans carry a fee per order, limits depend on your history, and late payments can add charges. Add up fees across all open Zip plans before you start another one, and check whether a debit purchase would be cheaper overall.
- Pay in 4 at many stores
- Virtual card for wider use
- Simple app for tracking payments
- Fees can apply per order or plan
- Limits vary
- Late fees may apply
Splitit suits cardholders who want instalments without opening a new credit account. It splits a purchase across your existing credit card, so you keep the card rewards and terms you already know. For people with available credit and a clear payoff plan, that simplicity is appealing. The catch is that the card still matters. If you do not clear the card balance, card interest can apply on top of the split, which defeats the point. Check available credit first, confirm the store supports Splitit, and plan to clear the full card balance on schedule.
- Uses your existing credit card
- No new credit application in many cases
- Interest-free instalments at participating stores
- Needs available credit on your card
- Merchant coverage varies
- Card interest applies if you do not clear the balance
Shop Pay Installments suits shoppers who buy often from Shopify stores. Four interest-free payments cover smaller orders, while monthly plans help with larger ones, all inside a checkout you already know. Saved details also make repeat purchases faster. The limit is coverage and cost on longer plans. Monthly instalments can carry interest, and not every Shopify store offers the option. Check the plan terms at checkout, compare the total cost, and remember that fast checkout should not replace a quick budget check.
- Four interest-free payments
- Monthly plans for larger orders
- Built into Shopify checkout
- Monthly plans can carry interest
- Only where Shopify stores offer it
- Limits vary by store and profile
Perpay suits people with limited or poor credit history who want a structured way to buy and repay. Repayment through payroll, where available, keeps payments regular, and the marketplace model bundles shopping and repayment in one place. For some users, that structure helps. The trade-off is choice and cost. You shop within its marketplace, and terms vary by product and employer setup. Compare the total price with buying elsewhere, check the repayment schedule against your pay dates, and avoid a purchase that strains your monthly budget.
- Repayment through payroll in some cases
- Marketplace shopping
- No traditional credit check for some users
- Product choice is tied to its marketplace
- Repayment terms vary
- Total cost needs careful checking
Cash App Afterpay suits people who already use Cash App and want pay later without a separate account. It brings Afterpay-style four-payment plans into an app many users open daily, which makes tracking easier. In-store options, where offered, extend that convenience beyond online shopping. The catch is variation. Limits, fees and store coverage can differ by region and account history, so do not assume every Afterpay term applies in Cash App. Read the plan screen, keep a cap on open plans, and check payment dates against your balance.
- Four payments through Cash App and Afterpay
- Familiar app for many US users
- In-store card option in some cases
- Availability and limits vary
- Late fees can apply
- Terms differ from standard Afterpay in some cases
How we picked these
We reviewed official product, pricing and help pages, plus app store listings, for each pay later app. We compared plan types, interest, fees, credit checks, spending limits and store coverage, and we gave weight to clarity at checkout. Where a fee or limit varies by purchase, region or credit profile, we wrote See website rather than copying a single figure. We did not claim hands-on testing. This guide is not financial advice, and costs and terms vary, so check the provider before you buy. A pay later plan is a form of credit, and missed payments can bring fees and affect credit records.
How to use pay later without hurting your budget
Start with the total, not the instalment. Add up every open pay later plan, then check that the total due in the next month fits comfortably after rent, bills and food. If the instalment looks easy but the total does not, the purchase is too large or too soon. A good rule is one or two open plans at a time, not five small ones that hide the sum. Next, read the plan terms before you tap confirm. Note whether interest applies, what happens on a late payment, whether the plan reports to credit agencies, and how returns work. Returns can be slow to reflect in a pay later plan, so keep proof of return and check that scheduled payments pause or adjust as promised. Finally, use pay later for planned purchases with a payoff date, not for impulse buys. Set payment reminders, keep the payment method funded, and pause new plans if income drops. If you miss a payment, contact the provider early, because early contact often gives more options than waiting for fees to build.
Frequently asked questions
What is the best pay later app?
Klarna suits shoppers who want flexible plan types, Affirm suits larger purchases with longer terms, and Afterpay suits simple four-payment shopping. The best choice depends on the purchase size, the store and whether you want interest-free short terms or a longer monthly plan.
Are pay later apps interest-free?
Pay in 4 plans are often interest-free when paid on time, but longer monthly plans can carry interest. Interest, fees and terms vary by app, retailer and credit profile, so read the plan shown at checkout rather than assuming the app name means interest-free.
Do pay later apps affect credit scores?
Some plans report to credit agencies and some do not, and reporting rules vary by app and region. Missed payments can harm credit records where reporting applies, and some apps run a soft or hard credit check depending on the plan. Check the terms for the exact plan you choose.
What is the best pay over time app for large purchases?
Affirm is often a good fit for large purchases because it offers longer terms and shows the total interest cost upfront. Compare that total with saving for the item or using a low-interest card, because a longer term lowers monthly payments but raises total cost.
Can I use pay later for groceries or everyday items?
Some apps, such as Zip and Sezzle, cover everyday purchases at participating stores, but splitting essentials can hide rising spending. If you use pay later for basics, keep a strict monthly cap and review the total often, because small instalments add up quickly.
Sources we checked (10)

Online Jobs is an independent blog about careers, online work, learning new skills and the tools that help people earn. More about us.
Keep reading
All posts
Top AI Financial Software
Searching for top AI financial software? We compared 9 AI finance tools for AP, spend, close, forecasting and bookkeeping to help teams choose wisely.

Quicken Alternatives
Compare the best quicken alternatives for Mac, Windows, and small business owners, from Monarch Money and YNAB to Copilot, Tiller, and Banktivity in 2026.
GoFundMe Alternatives
Looking for GoFundMe alternatives? We compared 8 fundraising platforms on fees, campaign types, donor tools and who each platform suits best in 2026 today.