Best Instant Cash Apps in 2026: 8 Apps Compared

How we put this together: we compare official feature and pricing pages, app store listings, privacy policies and public user reviews. Prices change, so check the provider's site before you pay.
Key takeaways
- EarnIn is the cheapest for many workers because it has no mandatory monthly fee, although instant delivery still costs extra.
- Brigit and Dave bundle budgeting tools with advances, but their monthly fees keep running even in months when you do not borrow.
- New users usually qualify for far less than the advertised maximum, so treat the headline limit as a ceiling, not a promise.
- Instant delivery fees, tips, and subscription fees add up fast on small advances, so standard delivery is often the cheaper choice when you can wait.
- This is not financial advice. These apps are short term cash flow tools, not a fix for a persistent budget gap, and repayment comes from your next paycheck or deposit.
Quick comparison
| Name | Who it suits | Starting price | Free option | |
|---|---|---|---|---|
 EarnIn | No mandatory fee advances | Free | Yes | Visit |
 Dave | Budget tools with advances | $5 per month | Free trial | Visit |
 Brigit | Overdraft prediction and budgeting | $8.99 per month | Free trial | Visit |
 MoneyLion | No subscription cash advances | Free | Yes | Visit |
 Chime MyPay | Existing Chime customers | Free | Yes | Visit |
 Albert | Higher limits with banking tools | Free | Yes | Visit |
 Klover | No subscription access | Free | Yes | Visit |
 Tilt | Flexible eligibility and fast delivery | $8 per month | Free trial | Visit |
The best instant cash apps
We compared cash advance and earned wage access apps on mandatory fees, instant delivery cost, advance limits, repayment timing, and eligibility. The list below focuses on apps available in the United States, and every fee below should be confirmed in the app before you accept an advance, because fees change and vary by state and account.
EarnIn is our pick for workers who want an advance without paying a monthly fee just to keep the app. It lets eligible users access part of earned wages before payday, with standard delivery taking one to two business days and instant delivery available for a fee. The service fee and instant fee vary by amount and account, so check the total before you confirm.
The catch is access. New users often start with a small daily limit and build up over time, and EarnIn needs to verify income and pay timing, which means it is not instant for everyone on day one. EarnIn fits hourly and salaried workers with regular direct deposits who want occasional help bridging to payday without a subscription.
- No mandatory monthly fee
- Advances based on earnings and pay schedule
- Optional tips instead of interest in many cases
- Instant delivery costs extra
- Advance limits for new users are much lower than the maximum
- Requires income verification and direct deposit history
Dave pairs its ExtraCash advances with budgeting features, account monitoring, and side hustle suggestions, which makes it more than a bare advance app. Eligible users can access up to $500, with repayment taken automatically on the agreed settlement date, usually your next payday. Delivery to a Dave checking account is fastest, while delivery to an external bank can take up to three days without an instant fee.
The honest cost is higher than it first looks. A $100 advance can carry a $5 service fee plus a membership fee, and the 5 percent fee grows with larger advances up to a cap. Dave fits customers who will actually use the budgeting tools and who take advances rarely enough that the membership still makes sense.
- Advances up to $500 for eligible users
- Budgeting tools and spending alerts
- Instant delivery to a Dave account
- Monthly membership up to $5
- Per advance service fee of 5 percent with a $5 minimum
- Instant delivery to an external debit card costs extra
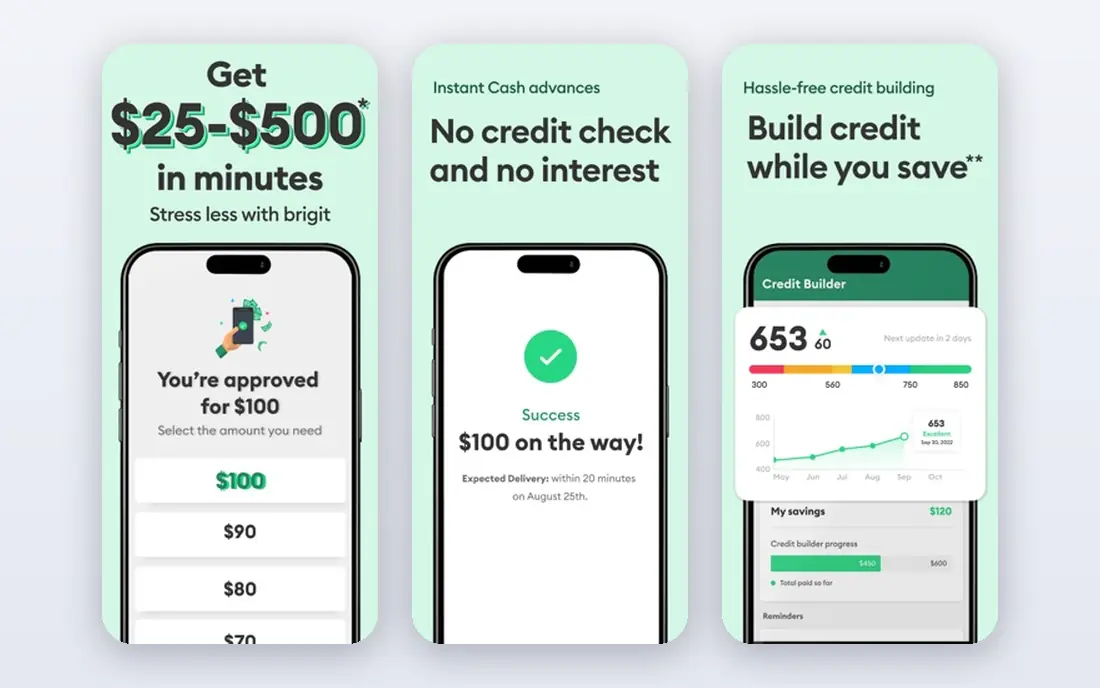
Brigit is built around preventing overdrafts rather than just covering them after they happen. It monitors linked accounts, warns when a balance looks low, and offers advances up to $500 to eligible members, with standard delivery taking one to three business days and express delivery available for a fee. Higher plans add identity monitoring and a credit builder feature.
The catch is the subscription. You pay $8.99 or $15.99 per month whether or not you take an advance that month, so Brigit is expensive for a single small advance and better value if you use its monitoring tools every month. Brigit fits customers who face regular overdraft risk and want alerts and planning tools alongside occasional advances.
- Advances up to $500
- Overdraft prediction alerts
- Budgeting and credit builder tools on higher plans
- Monthly membership of $8.99 to $15.99 required for advances
- Express delivery costs extra
- Subscription continues even if you do not borrow
MoneyLion Instacash is a strong choice for customers who dislike subscriptions. Basic advances carry no mandatory monthly fee, and standard delivery is free, although it can take several business days. Expedited delivery is available for a fee that varies by amount and account, so the cheapest path is to plan ahead when you can.
The limit is patience. If you need money within minutes, the expedited fee eats into a small advance, and new users may qualify for far less than $500 at first. MoneyLion fits customers who want a no subscription option, who can wait for standard delivery, or who already use MoneyLion banking and can reach the higher limit.
- Instacash advances up to $500, or up to $1,000 with a MoneyLion account
- No mandatory subscription for basic advances
- Standard delivery is free
- Expedited delivery costs $0.49 to $8.99
- Standard delivery can take up to five business days
- Higher limits require account activity
Chime MyPay is only useful if you already bank with Chime, but for those customers it is one of the cheapest options. Eligible members can access up to $500 of earned wages, with free delivery often within 24 hours and an instant option for a small fee. Repayment comes from the next qualifying direct deposit, which keeps the process simple inside one app.
The catch is eligibility. You need a Chime account with qualifying direct deposit history, and limits start lower for new users. Chime MyPay fits existing Chime customers who want occasional early access to wages without adding another app, another subscription, or another bank account.
- No mandatory fee for eligible Chime members
- Advances up to $500
- Free delivery within 24 hours in many cases
- Requires a Chime account and qualifying direct deposits
- Instant delivery to some accounts costs extra
- Not available to non Chime customers
Albert Instant offers advances from $25 to $1,000, with higher limits building over time rather than arriving on day one. Delivery to an Albert Cash account is instant, while delivery to an external account takes minutes for a fee or two to three business days for free. The app also bundles budgeting, saving, and investing tools, which some customers value and others will ignore.
The repayment window deserves attention. Albert advances are often due within six days, which is shorter than a full pay cycle for some workers, although extensions may be available in the app. Albert fits customers who want a higher ceiling over time and who can repay quickly, rather than customers who need a full two weeks to cover an advance.
- Advances up to $1,000 over time
- Instant delivery to an Albert account
- Budgeting and saving tools in the same app
- Instant delivery to an external account costs extra
- Free standard delivery takes two to three business days
- Repayment is due within six days in many cases
Klover appeals to customers who want to avoid a monthly fee and who are willing to work through its points system to raise their limit. The base service has no subscription, and advances can reach $750 over time for eligible users with steady income and deposit history. Standard delivery is free but slow, while instant delivery is available for a fee.
The catch is the instant fee range. Published comparisons show instant fees that vary by amount and account, and on a small advance the fee can be a large share of the amount borrowed. Klover fits patient users who can wait for standard delivery, or who only need instant delivery rarely and check the fee before confirming.
- No mandatory subscription
- Advances up to $750 over time
- Points based system for larger advances
- Instant delivery fees vary widely and can be high
- New user limits are much lower
- Free standard delivery takes up to three business days
Tilt, combines cash advances with budgeting and saving tools in one subscription. Eligible users can access up to $500 over time, with standard delivery often within one business day and expedited delivery available for a fee. The app does not use a tipping model, which makes the cost easier to predict than apps where tips are encouraged at checkout.
The trade off is the subscription. At $8 per month, Tilt costs $96 per year even if you borrow only once, so it only makes sense if you use its budgeting tools or borrow regularly enough to justify the fee. Tilt fits customers who want predictable pricing, faster standard delivery, and a single app for advances and budgeting.
- Advances up to $500 over time
- Fast free standard delivery in many cases
- No tipping model
- Monthly subscription of $8 after trial
- Expedited delivery costs extra
- Limits start lower for new users
How we picked these
We compared official app pages, fee disclosures, and public comparisons checked in October 2026, and we favoured apps that are widely available in the United States, that publish advance limits and fee structures, and that cover different needs, from no subscription options to budgeting bundles. We did not claim hands on borrowing, because limits and fees vary by income, state, deposit history, and account type. Confirm the exact fee, delivery time, and repayment date in the app before you accept any advance.
How to use a cash advance app without getting trapped
Treat an advance as a timing tool, not extra income. Borrow only the amount you can repay from your next paycheck without borrowing again, and choose standard delivery when you can wait, because instant fees are the most common surprise cost. Add up the membership fee, the per advance fee, the instant fee, and any tip before you confirm, and compare that total to the cost of waiting, asking an employer for a pay advance, or using a credit union small dollar loan.
Watch for these costs
Tips are optional on some apps but are presented at checkout in a way that feels expected, so decide in advance whether you will tip. Subscriptions keep charging in months when you do not borrow, so cancel if you stop using the app. Repayment is usually automatic, so make sure the repayment date does not collide with rent, utilities, or other automatic payments. If you find yourself borrowing every pay period, that is a sign to seek free budgeting help from a nonprofit credit counsellor or your employer assistance program rather than a larger advance.
Frequently asked questions
What is the best app for instant cash?
EarnIn is the best starting point for many workers because it has no mandatory monthly fee, while MoneyLion and Chime MyPay are strong no subscription options for their own customers. The best app for instant cash depends on whether you can wait for standard delivery, because instant fees change the cost sharply.
What is the best app for instant cash with no fees?
No app is fully free for instant delivery in every case. EarnIn, MoneyLion, and Chime MyPay offer free standard delivery or no mandatory subscription, but instant delivery usually costs extra. Read the fee screen for the exact amount before you confirm, and use standard delivery when timing allows.
How much can I borrow from a cash advance app?
Advertised maximums range from $500 to $1,000 on this list, but new users usually qualify for much less, often $25 to $100 at first. Limits grow with steady income, regular deposits, and a history of on time repayment, and they vary by state and account type.
Do cash advance apps check credit?
Most cash advance apps do not run a hard credit check, and they usually base eligibility on income, bank activity, and deposit history instead. That does not mean borrowing is risk free, because repayment is automatic and a failed repayment can trigger overdraft fees from your bank.
How fast do I get the money?
Standard delivery usually takes one to three business days, and in some cases up to five days, while instant delivery can arrive within minutes to an hour for a fee. Delivery to an account inside the same app is often fastest, while delivery to an external bank or debit card may cost more or take longer.
Is a cash advance app better than a payday loan?
Cash advance apps usually cost less than a traditional payday loan for a small amount, because they do not charge interest in the same way, but fees and tips can still add up to a high effective cost on a small advance. For larger needs or repeated borrowing, a credit union loan, an employer advance, or community assistance may be cheaper and safer.
Sources we checked (9)

Online Jobs is an independent blog about careers, online work, learning new skills and the tools that help people earn. More about us.
Keep reading
All posts
Top AI Financial Software
Searching for top AI financial software? We compared 9 AI finance tools for AP, spend, close, forecasting and bookkeeping to help teams choose wisely.

Quicken Alternatives
Compare the best quicken alternatives for Mac, Windows, and small business owners, from Monarch Money and YNAB to Copilot, Tiller, and Banktivity in 2026.

QuickBooks Online Alternatives
Looking for quickbooks online alternatives? We compared 8 accounting tools on invoicing, bank feeds, payroll, pricing and fit for small businesses today.