Best Home Equity Investment Companies in 2026: 7 Companies Compared

How we put this together: we compare official feature and pricing pages, app store listings, privacy policies and public user reviews. Prices change, so check the provider's site before you pay.
Key takeaways
- Point and Hometap offer some of the largest funding amounts, up to $600,000 in vendor and review listings, with terms that differ sharply.
- Unison is available in more states than most rivals, which matters if you live outside the largest markets.
- Splitero offers a long term of up to 30 years, while Hometap and Unlock use shorter 10-year terms that suit different plans.
- Most home equity investment companies accept lower credit scores than traditional lenders, often from 500, because there is no monthly payment to underwrite.
- A home equity investment is not a loan, and the amount owed at settlement can be much larger than the cash received if your home rises in value.
Quick comparison
| Name | Who it suits | Starting price | Free option | |
|---|---|---|---|---|
 Point | Long term and flexibility | See website | No | Visit |
 Hometap | Large funding amounts | See website | No | Visit |
 Unison | Wide state availability | See website | No | Visit |
 Unlock | Flexible buyout options | See website | No | Visit |
 Splitero | Long timeline and perks | See website | No | Visit |
 Nada | Pricing transparency | See website | No | Visit |
 EquityChoice | Predictable structure | See website | No | Visit |
The best home equity investment companies
A home equity investment, also called a home equity agreement, gives you cash now in exchange for a share of your home's future value. There is usually no monthly payment and no interest rate, but you repay a larger amount when you sell, refinance or reach the end of the term. That trade can help homeowners who cannot qualify for a loan, but it can also be costly if prices rise fast. This is not financial advice, and you should get independent advice and model several price scenarios before signing. Availability, funding limits and fees vary by state and property type, so check the current terms for your address.
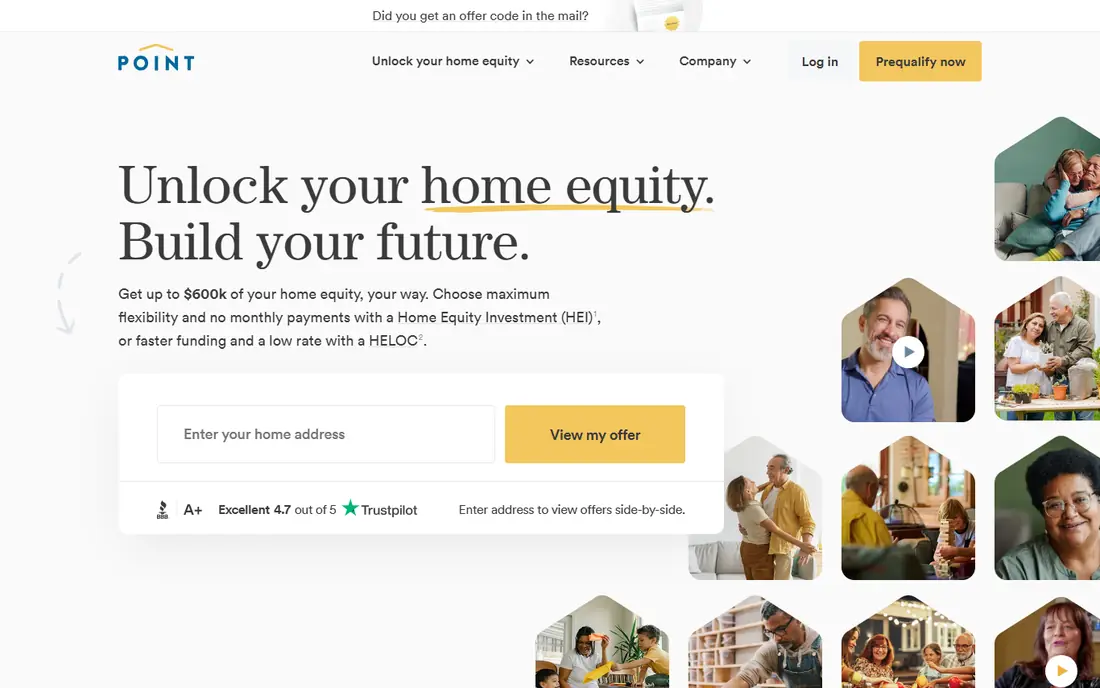
Point is often listed as a strong overall choice because it combines a large funding range with a long term. A term of up to 30 years gives homeowners more time before settlement than 10-year agreements, which can reduce pressure to sell or refinance on a fixed date. The lower credit minimum also helps homeowners with irregular income or past credit issues. The catch is the same as for all equity investments: a long term means more time for appreciation to build, and the share owed at settlement can grow with it. State availability is also limited, so some homeowners cannot apply at all. Point suits owners who want time and flexibility, and who have modelled the cost in a rising market.
- Funding up to $600,000 in listings
- Term up to 30 years
- Credit minimum listed from 500
- Not available in every state
- Settlement share can be large if values rise
Hometap is a good match for homeowners who need a large lump sum and do not want a monthly bill. Funding listings reach $600,000, and the application and funding process is often described as faster than a traditional loan. A dashboard helps owners track the agreement and settlement options over time. A 10-year term is the main limit. Owners must be ready to sell, refinance or buy out the agreement within that period, which can be tight if house prices or interest rates move against them. Hometap suits owners with a clear plan for settlement within 10 years and a need for a larger amount.
- Funding up to $600,000 in listings
- No monthly payments
- Dashboard for tracking the investment
- 10-year term is shorter than some rivals
- Limited state availability
Unison stands out for availability. It is listed in more states than most home equity investment companies, which makes it a first check for owners outside the main markets. A term of up to 30 years also gives flexibility, and many agreements share downside if the home loses value, so the owner does not bear the full fall alone. Credit expectations are higher than Point or Hometap in many listings, often from 620, and the share of home value available can be lower. That means some owners may receive less cash than with a rival. For owners in a state where few providers operate, Unison is often the most practical starting point.
- Available in more than 30 states in listings
- Term up to 30 years
- Downside sharing if values fall
- Higher credit expectations than some rivals
- Funding share is capped at a lower share of value in listings
Unlock is useful for owners who want options at settlement. Early buyout flexibility and varied repayment paths help owners who may refinance, sell part of a property plan, or buy out the agreement before the term ends. It also appears in listings for rental and investment properties, which many rivals do not cover in the same way. The 10-year term still creates a deadline, and final terms depend on the property, state and valuation, so headline figures do not guarantee an offer. Owners should ask for a clear settlement example at several future home values before signing. Unlock suits owners who value exit flexibility over the longest possible term.
- Flexible repayment and early buyout options
- Credit minimum listed from 500
- Investment property options in listings
- 10-year term
- Terms and fees vary by borrower and state
Splitero combines a long term with a funding range up to $500,000 in listings. No repayment is required before the term ends in many agreements, which gives owners time to plan a sale or refinance. The vendor also lists homeowner perks, such as support services, which can add value beyond cash alone. State availability is narrower than Unison, and the cost structure, including a safety cap in listings, needs careful comparison with a simple fee model. Owners should ask how the cap works in both rising and flat markets. Splitero suits owners who want a long timeline and are comfortable reading a more complex agreement.
- Term up to 30 years
- Funding up to $500,000 in listings
- Additional homeowner perks listed by the vendor
- Available in fewer states than Unison
- Cost cap structure needs careful reading
Nada is noted for publishing more pricing detail than many competitors, including an annualised cost cap in listings plus origination and underwriting fees. That transparency helps owners compare total cost, rather than judging by the cash amount alone. Checking eligibility without a hard credit pull is also a benefit for owners who are still comparing options. Availability is more limited, and the term is 10 years, so settlement planning matters. Fees on top of the appreciation share also need to be added to any cost model. Nada suits owners who want clearer published terms and are willing to work through the full fee breakdown.
- More published pricing detail than many rivals
- No hard credit pull to check eligibility in listings
- Credit minimum from 500
- Available in fewer states
- 10-year term
EquityChoice is listed as a choice for owners who want a more predictable structure than a pure appreciation share. Its model is described in reviews as closer to a fixed cost approach, which can make settlement math easier to understand. Funding up to $500,000 covers many homeowner needs, and the 10-year term is clear from the start. Credit minimums in listings are higher, often from 600 or 680 depending on the source, so some owners may not qualify. State availability is also narrower than the largest providers. For owners who value predictability and can meet the credit bar, EquityChoice is worth comparing against Point and Hometap.
- More predictable rate structure in listings
- Funding up to $500,000 in listings
- 10-year term clarity
- Higher credit minimum in listings
- Fewer states than Unison
How we picked these
We compared official feature pages, pricing pages and public reviews for home equity investment companies that are actively operating in October 2026. We weighted funding range, term length, fee transparency, credit flexibility, state availability and settlement options, rather than judging by the largest cash offer alone. Companies that only offered HELOCs or home equity loans, or that had no clear home equity agreement product, did not make the list.
Questions to ask before you sign an agreement
Start with settlement math, not the cash amount. Ask for the amount you would owe if your home rises by 10 percent, 25 percent and 50 percent, and if it stays flat or falls. Compare that total with a HELOC or home equity loan over the same period, including interest and fees, so you can see the true cost in each case. Check the term, the settlement triggers, the valuation method and any fees for early buyout, appraisal or closing. Ask whether you can make partial buyouts, what happens if you need to refinance, and whether the agreement allows rental or investment use. Get the full contract reviewed by an independent adviser, and do not sign based on a headline funding amount alone. If you need ongoing access to equity rather than a lump sum, a HELOC may fit better despite monthly payments.
Frequently asked questions
What is the best home equity agreement company?
Point is a strong overall pick for term flexibility, Hometap suits large funding needs, and Unison suits owners in states where few providers operate. The best company depends on your state, credit profile, funding need and settlement plan. Compare at least two offers with the same future home value assumptions before choosing.
What is the best home equity investment company for low credit?
Point, Hometap, Unlock, Splitero and Nada list credit minimums from 500 in many sources, which is lower than traditional loan requirements. Approval still depends on equity, property type and state, so a low minimum does not guarantee an offer. Check eligibility without a hard credit pull where the vendor offers that option.
How does a home equity investment work?
You receive cash now and agree to pay the company a share of your home's value later, when you sell, refinance or reach the end of the term. There is usually no monthly payment and no interest rate. If your home rises in value, you owe more than you received, and if it falls, many agreements share that downside.
Is a home equity investment better than a HELOC?
It depends on cash flow and cost. A home equity investment has no monthly payment, which helps owners with tight cash flow, but it can cost more if values rise sharply. A HELOC has monthly payments and variable interest, but the total cost is often lower in a rising market. Model both options at several future values before deciding.
How long do home equity agreements last?
Terms in this list range from 10 years for Hometap, Unlock, Nada and EquityChoice to up to 30 years for Point, Unison and Splitero. A longer term gives more time to plan settlement, but it also gives more time for appreciation to increase the amount owed. Choose a term that matches a realistic sale or refinance plan.
What fees do home equity investment companies charge?
Fees vary by company and state, and often fall between 3 percent and 5 percent of the funding amount in listings, plus appraisal and closing costs in some cases. The appreciation share is the main cost, not the upfront fee, so ask for a full settlement example. This is not financial advice, and independent advice is important before signing.
Sources we checked (7)

Online Jobs is an independent blog about careers, online work, learning new skills and the tools that help people earn. More about us.
Keep reading
All posts
Top AI Financial Software
Searching for top AI financial software? We compared 9 AI finance tools for AP, spend, close, forecasting and bookkeeping to help teams choose wisely.
Quicken Alternatives
Compare the best quicken alternatives for Mac, Windows, and small business owners, from Monarch Money and YNAB to Copilot, Tiller, and Banktivity in 2026.
QuickBooks Online Alternatives
Looking for quickbooks online alternatives? We compared 8 accounting tools on invoicing, bank feeds, payroll, pricing and fit for small businesses today.