Best Fiduciary Investment Companies in 2026: 8 Companies Compared

Low-cost managed portfolios · Starting price: See website
How we put this together: we compare official feature and pricing pages, app store listings, privacy policies and public user reviews. Prices change, so check the provider's site before you pay.
Key takeaways
- A fiduciary adviser must act in your best interest, but always confirm that duty in writing for the exact service you buy.
- Flat-fee and hourly advice can beat a percentage fee on larger balances, while percentage fees can be cheaper on small balances.
- Vanguard, Schwab and Fidelity suit investors who want managed portfolios alongside brokerage accounts.
- Facet and Garrett suit buyers who want planning help without handing over a large portfolio.
- Check minimums, total fees and what planning topics are included before you sign.
Quick comparison
| Name | Who it suits | Starting price | Free option | |
|---|---|---|---|---|
| Vanguard Personal Advisor | Low-cost managed portfolios | See website | No | Visit |
 Charles Schwab | Investors who want branches and digital advice | See website | No | Visit |
 Fidelity Investments | Investors who want planning plus brokerage | See website | No | Visit |
 Facet | Flat-fee planning and management | See website | No | Visit |
 Garrett Planning Network | Hourly, one-off advice | See website | No | Visit |
 Edelman Financial Engines | Workplace retirement planning | See website | No | Visit |
 Empower Personal Wealth | High-balance planning and dashboards | See website | No | Visit |
 Fisher Investments | Larger portfolios seeking active management | See website | No | Visit |
The best fiduciary investment companies
We compared the options below on fit for the topic, core features, pricing transparency and current availability. Prices change, so check the vendor page before you buy. This is not financial advice; investing carries risk and values can fall as well as rise.
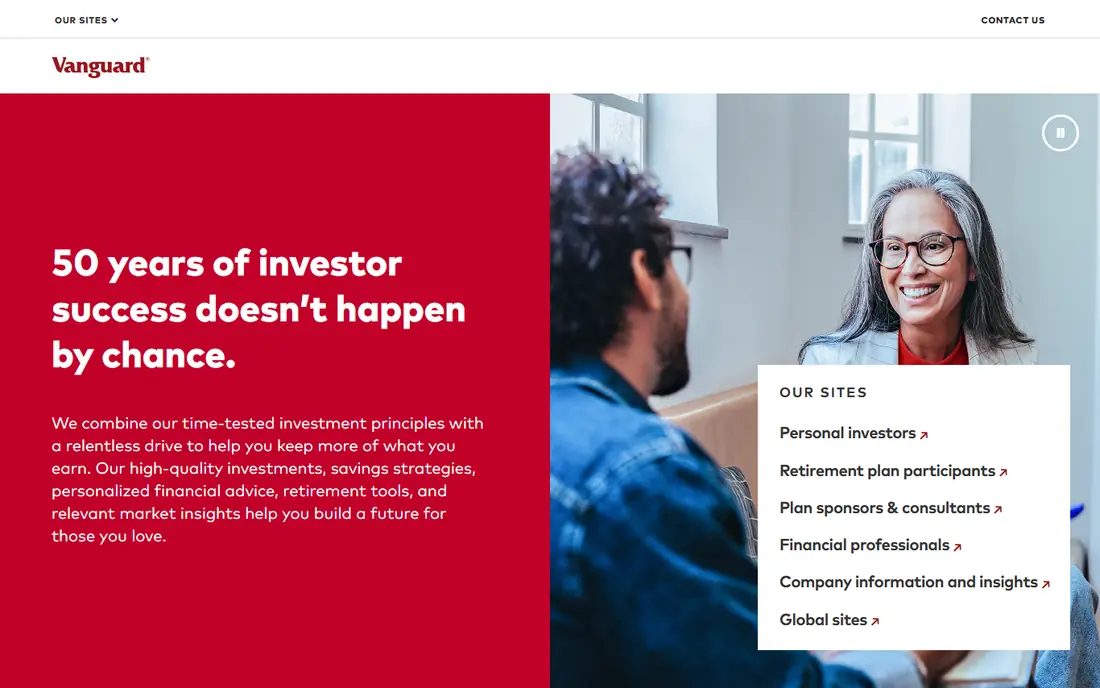
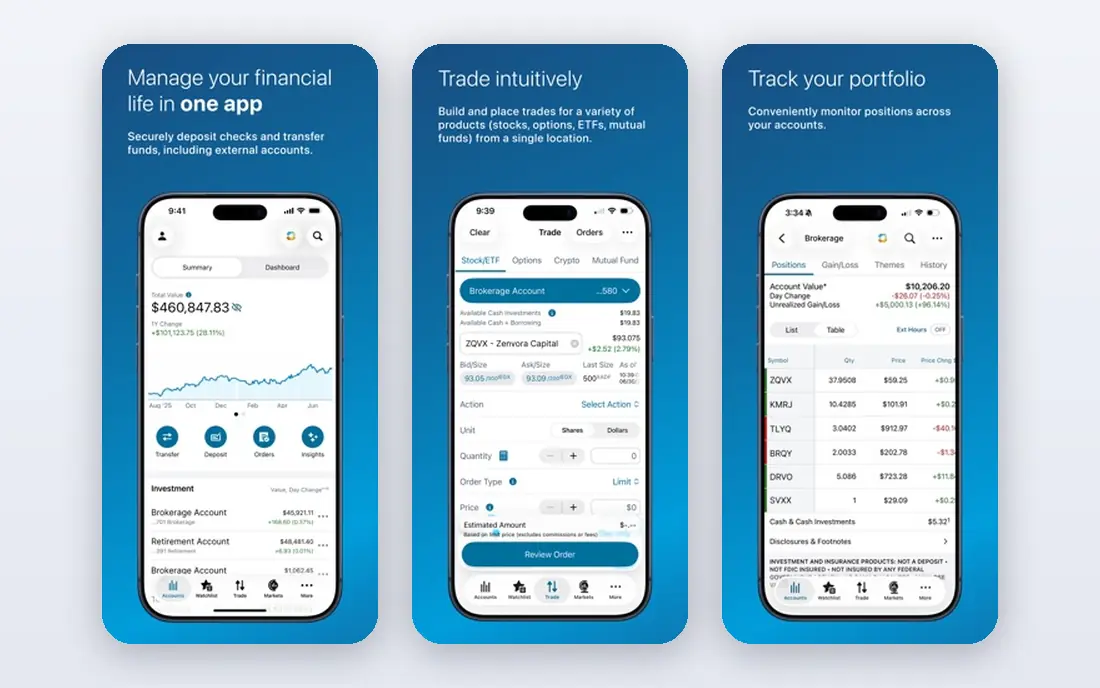
For readers who want a clear first choice, Vanguard Personal Advisor deserves a close look. It is best for low-cost managed portfolios. The main strengths are low-cost index approach and human adviser access. In daily use, the core tools are easy to find, and the main tasks take few steps. In practice, broad planning tools helps with the work most buyers actually do week after week, rather than sitting unused in a menu. The honest catch is that minimum balance applies and service tiers vary by balance. That trade-off will matter more to some buyers than others, so weigh it against the price and the features you will use most, and test the free option or trial where one is offered before you commit.
- Low-cost index approach
- Human adviser access
- Broad planning tools
- Minimum balance applies
- Service tiers vary by balance
If your main concern is value for money, Charles Schwab is worth putting near the top of the shortlist. It is best for investors who want branches and digital advice. The main strengths are wide investment choice and digital and human advice options. The setup process is guided, and most users can get a working result without outside help. In practice, large branch network helps with the work most buyers actually do week after week, rather than sitting unused in a menu. The honest catch is that advice pricing varies by service and some services need a higher balance. That trade-off will matter more to some buyers than others, so weigh it against the price and the features you will use most, and test the free option or trial where one is offered before you commit.
- Wide investment choice
- Digital and human advice options
- Large branch network
- Advice pricing varies by service
- Some services need a higher balance
Fidelity Investments
Who it suits: Investors who want planning plus brokerage
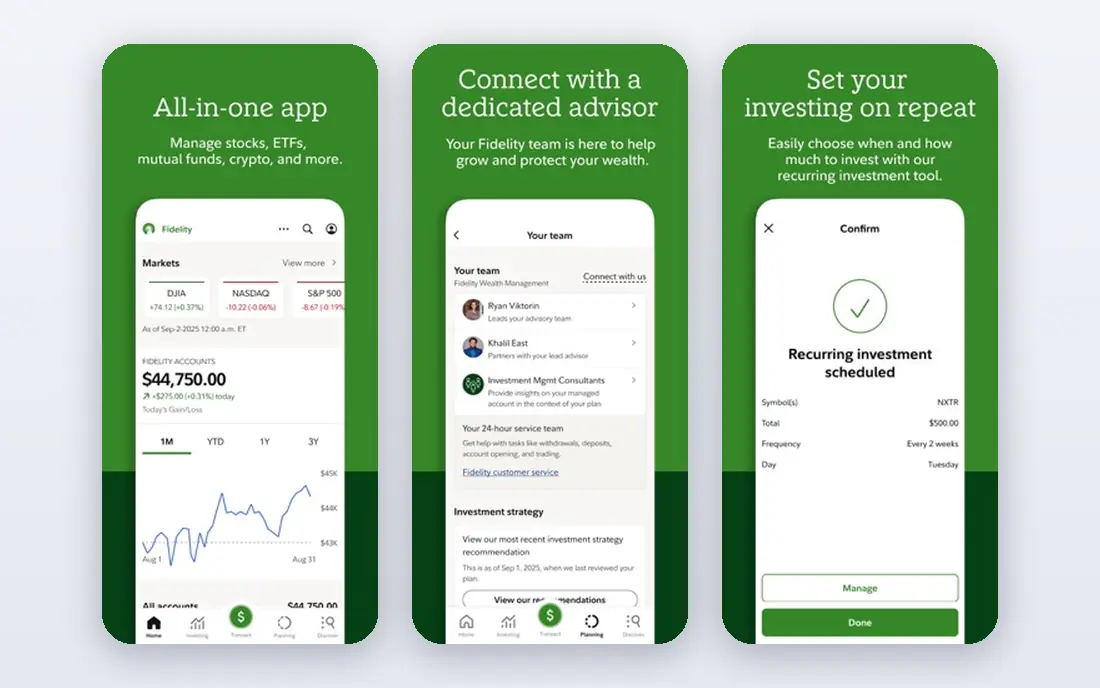
Where simplicity matters more than a long feature list, Fidelity Investments stands out. It is best for investors who want planning plus brokerage. The main strengths are broad account choice and planning tools. The interface keeps everyday tasks in one place, which cuts down on switching between tools. In practice, strong research and support helps with the work most buyers actually do week after week, rather than sitting unused in a menu. The honest catch is that advice fees depend on the service chosen and full-service advice is not free. That trade-off will matter more to some buyers than others, so weigh it against the price and the features you will use most, and test the free option or trial where one is offered before you commit.
- Broad account choice
- Planning tools
- Strong research and support
- Advice fees depend on the service chosen
- Full-service advice is not free
For a more complete, all-in-one option, Facet is a strong candidate. It is best for flat-fee planning and management. The main strengths are flat subscription pricing and dedicated planning team. Once an account or project is set up, repeat tasks follow a familiar pattern. In practice, tax and estate planning topics covered helps with the work most buyers actually do week after week, rather than sitting unused in a menu. The honest catch is that subscription cost can exceed a percentage fee on small balances and investment scope is defined by the plan. That trade-off will matter more to some buyers than others, so weigh it against the price and the features you will use most, and test the free option or trial where one is offered before you commit.
- Flat subscription pricing
- Dedicated planning team
- Tax and estate planning topics covered
- Subscription cost can exceed a percentage fee on small balances
- Investment scope is defined by the plan
If you are comparing on depth rather than price alone, Garrett Planning Network merits attention. It is best for hourly, one-off advice. The main strengths are hourly fee-only planners and pay only for the help you need. The reporting and export options cover the usual needs without forcing extra work. In practice, no asset minimum in many cases helps with the work most buyers actually do week after week, rather than sitting unused in a menu. The honest catch is that quality varies by planner and ongoing management is not the main offer. That trade-off will matter more to some buyers than others, so weigh it against the price and the features you will use most, and test the free option or trial where one is offered before you commit.
- Hourly fee-only planners
- Pay only for the help you need
- No asset minimum in many cases
- Quality varies by planner
- Ongoing management is not the main offer
Edelman Financial Engines
Who it suits: Workplace retirement planning
For people who prefer a well-known name with broad support, Edelman Financial Engines fits that brief. It is best for workplace retirement planning. The main strengths are deep retirement planning focus and workplace plan experience. Collaboration features let more than one person work on the same project or account. In practice, broad adviser network helps with the work most buyers actually do week after week, rather than sitting unused in a menu. The honest catch is that fees can be higher than a digital-only service and experience varies by office. That trade-off will matter more to some buyers than others, so weigh it against the price and the features you will use most, and test the free option or trial where one is offered before you commit.
- Deep retirement planning focus
- Workplace plan experience
- Broad adviser network
- Fees can be higher than a digital-only service
- Experience varies by office
Empower Personal Wealth
Who it suits: High-balance planning and dashboards
Where flexibility and room to grow matter, Empower Personal Wealth is a practical pick. It is best for high-balance planning and dashboards. The main strengths are free dashboard tools for tracking accounts and dedicated adviser service for larger balances. The mobile and desktop experience cover the main tasks, so work is not tied to one device. In practice, retirement planning focus helps with the work most buyers actually do week after week, rather than sitting unused in a menu. The honest catch is that adviser service has a minimum balance and dashboard alone is not advice. That trade-off will matter more to some buyers than others, so weigh it against the price and the features you will use most, and test the free option or trial where one is offered before you commit.
- Free dashboard tools for tracking accounts
- Dedicated adviser service for larger balances
- Retirement planning focus
- Adviser service has a minimum balance
- Dashboard alone is not advice
Fisher Investments
Who it suits: Larger portfolios seeking active management
For a lower-cost or lighter-weight alternative, Fisher Investments is worth considering. It is best for larger portfolios seeking active management. The main strengths are active portfolio management and global investment research. Custom settings let you shape the output to fit a common use case rather than starting over. In practice, dedicated service team helps with the work most buyers actually do week after week, rather than sitting unused in a menu. The honest catch is that minimum balance is high and fees are percentage-based and vary by balance. That trade-off will matter more to some buyers than others, so weigh it against the price and the features you will use most, and test the free option or trial where one is offered before you commit.
- Active portfolio management
- Global investment research
- Dedicated service team
- Minimum balance is high
- Fees are percentage-based and vary by balance
How we picked these
We compared official feature pages, pricing pages, app store listings, privacy policies and public reviews for each option. We kept only products that exist and work today and that fit the topic directly, and we left out options with unclear pricing or a poor fit even when they are well known in a nearby category. We did not claim hands-on testing for these picks. Instead, we weighed published features, plan limits and the kind of buyer each product serves, so the list works as a shortlist for further checks rather than a final verdict on its own.
How to choose a fiduciary adviser without overpaying
Start with the question you need answered. If it is a single decision, such as a pension rollover or a tax-year move, hourly advice may be enough. If you want ongoing portfolio care and yearly planning reviews, a managed service or a subscription makes more sense, even when the headline price looks higher. Ask every firm three things in writing: whether it acts as a fiduciary at all times for your account, the full fee including fund costs, and the minimum balance or subscription term. Compare those answers side by side, and be wary of any firm that will not put its fee and its fiduciary duty in plain terms. Finally, check how you will meet your adviser, how often reviews happen, and what happens if you leave. A good fit is one where the cost, the contact pattern and the planning scope all match your needs, not just the firm with the lowest advertised rate.
Frequently asked questions
Who is the best financial advisor company?
There is no single best firm for every investor. The right choice depends on your balance, whether you need ongoing management or one-off planning, and how much contact you want. Shortlist two or three firms from this list, compare their full fees, and interview each one before you commit.
What is the difference between a fiduciary and a non-fiduciary adviser?
A fiduciary must act in your best interest when giving advice for that account. A non-fiduciary may only need to recommend something suitable, which leaves more room for conflicts. Ask for the fiduciary commitment in writing, and check whether it covers every account and recommendation.
Are best financial advisors companies the same as best financial planner companies?
The terms overlap, but they are not identical. An adviser may focus on investments, while a planner may cover tax, retirement, estate and cash-flow topics in more depth. Many firms do both, so check the planning scope in the plan you are buying, not just the job title.
How much do best financial management companies charge?
Charges vary widely. Some charge a percentage of assets, some charge a flat subscription, and some charge by the hour. Add fund costs and any platform fees to the adviser fee to get the true yearly cost, and compare that total across firms.
Do I need best money management companies if I use index funds?
Not always. If your portfolio is simple and you are comfortable rebalancing, a low-cost fund portfolio may be enough. Advice adds value when tax, retirement timing, estate plans or a large one-off decision make the choice harder, or when you want a second pair of eyes.
What should I ask before hiring a financial advising company?
Ask about fiduciary duty, total fees, minimums, conflicts of interest, how often you will meet, and how you can leave. Also ask what planning topics are included and whether investment management is part of the fee or charged separately.
Sources we checked (8)

Online Jobs is an independent blog about careers, online work, learning new skills and the tools that help people earn. More about us.
Keep reading
All posts
Top AI Financial Software
Searching for top AI financial software? We compared 9 AI finance tools for AP, spend, close, forecasting and bookkeeping to help teams choose wisely.

Quicken Alternatives
Compare the best quicken alternatives for Mac, Windows, and small business owners, from Monarch Money and YNAB to Copilot, Tiller, and Banktivity in 2026.

QuickBooks Online Alternatives
Looking for quickbooks online alternatives? We compared 8 accounting tools on invoicing, bank feeds, payroll, pricing and fit for small businesses today.