Best Bank Customer Service in 2026: 9 Banks Compared

How we put this together: we compare official feature and pricing pages, app store listings, privacy policies and public user reviews. Prices change, so check the provider's site before you pay.
Key takeaways
- Chase and Capital One combine large branch or cafe networks with strong apps, which suits customers who want both in-person and digital help.
- Charles Schwab Bank, Ally Bank, and SoFi lead for online-first customers, with 24-hour support and digital tools as the main service route.
- USAA stands out for eligible military members and families, while American Express suits customers who want a strong online banking and card relationship.
- This is not financial advice. Fees, rates, and account terms vary, so confirm current terms on the bank's official site before you open an account.
Quick comparison
| Name | Who it suits | Starting price | Free option | |
|---|---|---|---|---|
 Chase | Branch plus digital service | See website | No | Visit |
 Capital One | Branches, cafes, and app | See website | No | Visit |
 Charles Schwab Bank | Online banking with support | See website | No | Visit |
 Ally Bank | Online-only banking | See website | No | Visit |
 USAA | Military members and families | See website | No | Visit |
 American Express | Online banking and cards | See website | No | Visit |
 SoFi | Digital banking and finance app | See website | No | Visit |
 Discover Bank | Online banking with cashback | See website | No | Visit |
 PNC Bank | Branch bank with digital tools | See website | No | Visit |
The best bank customer service
Good bank service means different things to different people: a branch nearby, a person on the phone at midnight, a chat that actually solves a problem, or an app that rarely needs support at all. We compared official bank pages, support descriptions, and public satisfaction summaries to find banks that score well across those routes in 2026.
Chase is the branch-bank pick for customers who want help in person and on their phone. Its branch and ATM network is one of the largest in the United States, and the app covers everyday banking, payments, deposits, and card management. That combination suits customers who sometimes need a banker face to face, for example for a complex account change or a safe-deposit need, but who do most banking digitally. Account fees, minimum balance rules, and waiver conditions vary by account type, so check the terms for the specific account you want. Branch service quality also varies by location. Chase fits customers who value a national branch network alongside a strong app, and who are willing to check fee waivers before opening an account.
- Large branch and ATM network
- Strong app
- Wide account range
- Fees and minimums vary by account
- Branch experience varies by location
Capital One blends traditional banking with a more casual service model, including Capital One Cafes in many cities alongside branches and a strong app. Customers can talk to staff in person, use digital tools for most tasks, and manage cards and accounts in one place. Some checking accounts are positioned as no-fee options, which helps customers who want to avoid monthly maintenance charges. Branch and cafe coverage is not even across the country, so customers outside major markets may rely more on digital support. Terms also vary by account and card product. Capital One fits customers who like a modern branch experience, a strong app, and clear no-fee checking terms where available.
- Branch and cafe locations
- Strong app
- No-fee checking options in some accounts
- Branch coverage is uneven by region
- Support experience varies by product
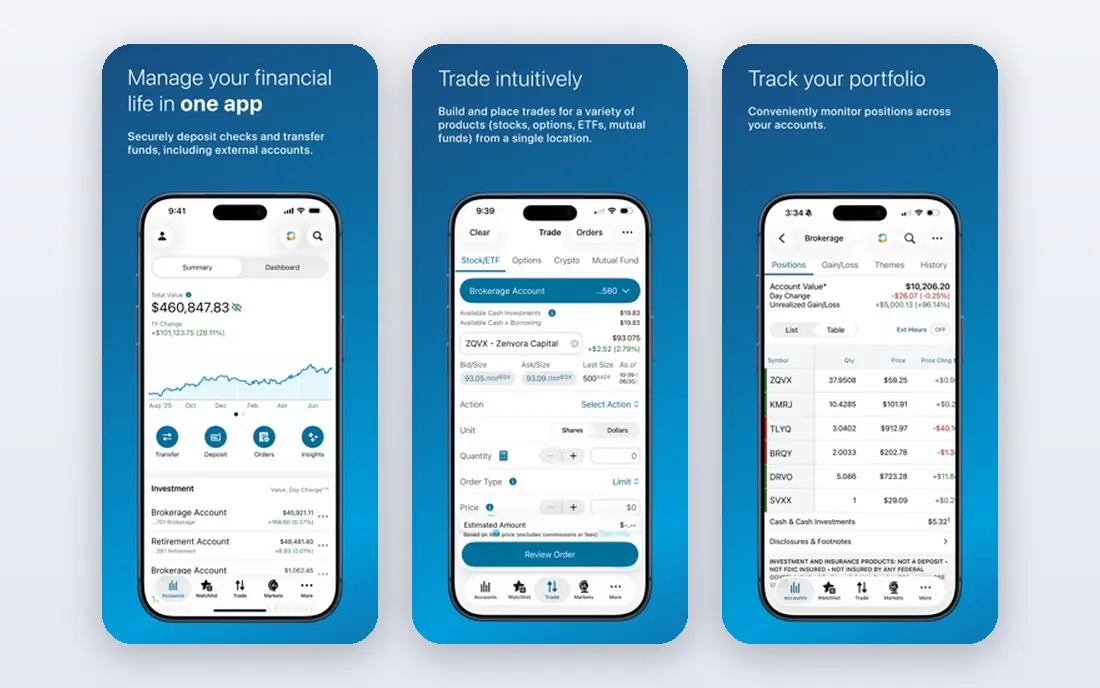
Charles Schwab Bank ranks highly in public satisfaction summaries for direct banking, thanks to responsive support and a clean online experience. Customers can manage checking and savings alongside investments, which suits people who want banking and brokerage in one relationship. Support is available around the clock in many channels, which helps when a problem arises outside business hours. Schwab Bank does not offer the same everyday branch network as Chase or PNC, so customers who need frequent in-person banking may miss that option. The investing side can also feel like extra weight if you only want a simple checking account. Schwab Bank fits online-first customers who value support quality and an integrated banking and investing relationship.
- Highly rated online banking satisfaction
- 24-hour support
- Banking plus investing
- No traditional branch network for everyday banking
- Investing focus may not suit all
Ally Bank is built for customers who are happy to bank entirely online. Support is available around the clock by phone and chat, and the app covers checking, savings, and money management in one place. Without branches, Ally can focus on digital service and savings features, which many online customers value more than a local office. The trade-off is cash handling. Depositing cash is less direct than at a branch bank, and some services rely on partners. Ally fits customers who rarely need a branch, want round-the-clock digital support, and prefer an online bank with a straightforward account range.
- 24-hour phone and chat support
- No traditional branches to maintain
- Competitive savings features
- No branches for cash deposits
- Some services need third-party partners
USAA is the standout for eligible military members, veterans, and their families. Its service model is built around deployments, moves, and military pay cycles, and it pairs banking with insurance and financial planning in one relationship. Support teams are familiar with military-specific needs, which many members value more than a generic bank service model. Eligibility is the limit. USAA membership is restricted to military members and eligible family members, so it is not an option for the general public. If you are eligible, USAA deserves a close look. If you are not, Ally, Schwab Bank, or SoFi offer a similar online-first service model without the eligibility restriction.
- Service built for military life
- Strong support reputation
- Banking plus insurance
- Eligibility is limited to military members and eligible family
- Not open to everyone
American Express ranks highly in direct banking satisfaction summaries, thanks to a clean online experience and responsive support. Customers who already use American Express cards can manage banking and cards together, and savings and checking products are designed for digital use. That simplicity suits customers who want a small, clear account range rather than a full branch bank menu. There is no branch network, and the banking range is narrower than Chase or PNC, with fewer specialised account types. American Express fits online customers who value service quality and a simple digital relationship, especially if they already use American Express cards.
- Highly rated direct banking satisfaction
- Strong app
- Card and banking in one relationship
- No branch network
- Banking range is narrower than full-service banks
SoFi suits customers who want banking, investing, and lending tools in one app. Checking and savings sit alongside investing, credit, and loan products, with direct deposit features and savings tools that help customers automate money management. Support is available through digital channels and phone, which fits an app-first customer. SoFi has no branch network, so customers who need in-person help will need another bank for that. The bundled product range can also feel like more than a simple checking customer needs. SoFi fits younger, digital-first customers who want one app for banking and wider finances, not just a standalone checking account.
- All-in-one finance app
- Direct deposit and savings features
- 24-hour support in many channels
- No branches
- Product range can feel bundled
Discover Bank pairs online banking with cashback features on eligible debit purchases, which appeals to customers who want a reward for everyday spending without a credit card. Support is available around the clock, and many accounts are positioned without monthly maintenance fees, subject to account terms. The app covers checking, savings, and money market accounts in one place. As with other online banks, there are no branches, and cash deposits are less direct. Discover fits online customers who want cashback, no-fee account terms where available, and round-the-clock support, rather than branch access or a wide business banking range.
- Online banking with cashback debit features
- 24-hour support
- No monthly fees on many accounts
- No branches
- Cash deposit options are limited
PNC Bank suits customers who want a traditional branch bank with modern digital tools. Its Virtual Wallet range combines spending, reserve, and growth accounts in one view, which helps customers organise money for bills, short-term goals, and savings. Branches and ATMs cover many eastern and central regions, and the app handles everyday banking well. Branch coverage is weaker in some western and rural areas, so check local availability before you choose PNC for in-person service. Account fees and waiver rules also vary by product. PNC fits customers in its branch footprint who want in-person help plus a clear digital money-management view.
- Branch and ATM network
- Virtual Wallet tools
- Strong app
- Branch coverage varies by region
- Account fees vary by product
How we picked these
We compared official bank pages, support channel descriptions, and public satisfaction summaries, including J.D. Power direct banking results reported in 2026, and we kept only banks that are actively offering consumer accounts in October 2026. We favoured banks with clear support routes, a strong app, and a consistent service reputation, rather than ranking banks on a single survey score. Where fees, rates, or account terms varied by account, we wrote "See website" instead of repeating a figure that could be out of date. We did not claim hands-on testing of every account, and we did not invent satisfaction scores or rankings. Satisfaction results vary by study, region, and product, so use this list as a shortlist and check current terms and local availability before you open an account. This is not financial advice.
How to choose the right bank for service
Decide how you want help
If you need a branch, shortlist Chase, Capital One, and PNC and check local coverage. If you are happy online, shortlist Schwab Bank, Ally, American Express, SoFi, and Discover, and test their chat and phone support before you move your main account.
Test support before you switch
Open a secondary account or use a demo and contact support with a real question. Note wait times, whether the first person solves the problem, and whether follow-up is clear. That test tells you more than any satisfaction headline.
Check fees, not just service
A bank with great service but high fees may still be a poor fit. Compare monthly fees, waiver rules, ATM fees, overdraft terms, and savings rates for the exact account you want. Service quality and total cost together decide the best bank for you.
Frequently asked questions
Which bank has the best customer service?
Chase and Capital One are strong for branch plus digital service, while Charles Schwab Bank, Ally Bank, and American Express rank highly for online banking satisfaction in public summaries. USAA stands out for eligible military members. The best bank for you depends on whether you want branches, online support, or both.
What is the best online banking platform?
Schwab Bank, Ally Bank, SoFi, and American Express all offer strong online banking platforms, with 24-hour support and clean apps. Ally and Schwab Bank suit customers who want banking plus savings tools, while SoFi suits customers who want banking, investing, and lending in one app. Test the app and support before you switch.
Which banks have the best customer service for military members?
USAA is built for military members and eligible families, with service designed around deployments, moves, and military pay. Other banks, including Chase and Schwab Bank, also serve military customers, but USAA's military-specific model is its main advantage. Check eligibility on the USAA site first.
Do online banks offer good customer service?
Yes, many online banks offer 24-hour phone and chat support that rivals branch banks for everyday problems. The limit is in-person help for complex or cash-heavy tasks, where branch banks have an edge. If you rarely need a branch, an online bank can offer faster, round-the-clock service.
How do I switch banks without missing payments?
List direct deposits, automatic payments, and subscriptions, then move them one by one and keep the old account open for a month. Confirm each payment has moved before you close the old account. Most banks offer switch tools, but a manual checklist prevents missed payments during the change.
Sources we checked (9)
- https://www.chase.com/personal/checking
- https://www.capitalone.com/bank/checking-accounts
- https://www.schwab.com/bank
- https://www.ally.com/bank
- https://www.usaa.com/bank
- https://www.americanexpress.com/banking
- https://www.sofi.com/banking
- https://www.discover.com/online-banking
- https://www.pnc.com/en/personal-banking.html

Online Jobs is an independent blog about careers, online work, learning new skills and the tools that help people earn. More about us.
Keep reading
All posts
Top AI Financial Software
Searching for top AI financial software? We compared 9 AI finance tools for AP, spend, close, forecasting and bookkeeping to help teams choose wisely.

Quicken Alternatives
Compare the best quicken alternatives for Mac, Windows, and small business owners, from Monarch Money and YNAB to Copilot, Tiller, and Banktivity in 2026.

QuickBooks Online Alternatives
Looking for quickbooks online alternatives? We compared 8 accounting tools on invoicing, bank feeds, payroll, pricing and fit for small businesses today.