Best Annuity Companies in 2026: 9 Companies Compared

Lifetime income with top financial strength · Starting price: $10,000 minimum
How we put this together: we compare official feature and pricing pages, app store listings, privacy policies and public user reviews. Prices change, so check the provider's site before you pay.
Key takeaways
- New York Life and MassMutual hold the highest A++ financial strength rating from AM Best, which matters most for contracts that may pay out for decades.
- The best-rated company is not always the best annuity for you: a slightly lower-rated insurer may offer higher income payouts or better contract terms.
- Annuity rates, minimums and surrender terms vary by state and contract, so always request a current rate sheet and read the contract before buying.
- Most top companies sell through financial professionals rather than direct online checkout, so expect a guided sales process.
- This article is general information only and is not financial advice; annuities are long-term contracts with surrender charges for early withdrawals.
Quick comparison
| Name | Who it suits | Starting price | Free option | |
|---|---|---|---|---|
| New York Life | Lifetime income with top financial strength | $10,000 minimum | No | Visit |
 MassMutual | Conservative savers prioritizing safety | $10,000 minimum | No | Visit |
 Nationwide | Indexed annuities with strong income riders | See website | No | Visit |
 Pacific Life | Wide product range bought direct | $25,000 minimum | No | Visit |
 Allianz Life | Fixed indexed annuities | $5,000 minimum | No | Visit |
 Lincoln Financial | Flexible income and legacy options | See website | No | Visit |
 Prudential | Fixed annuities with strong backing | See website | No | Visit |
 Athene | Competitive fixed indexed rates | See website | No | Visit |
 USAA Life | Military families wanting top service | See website | No | Visit |
The best annuity companies
An annuity is a contract with an insurance company that turns a lump sum into guaranteed income, tax-deferred growth, or both, and the company's ability to pay decades from now matters as much as today's rate. We compared financial strength ratings from AM Best, product ranges, published minimums and how each company sells, using official company pages and published rating actions. Where a company does not publish a figure, we say so rather than guessing.
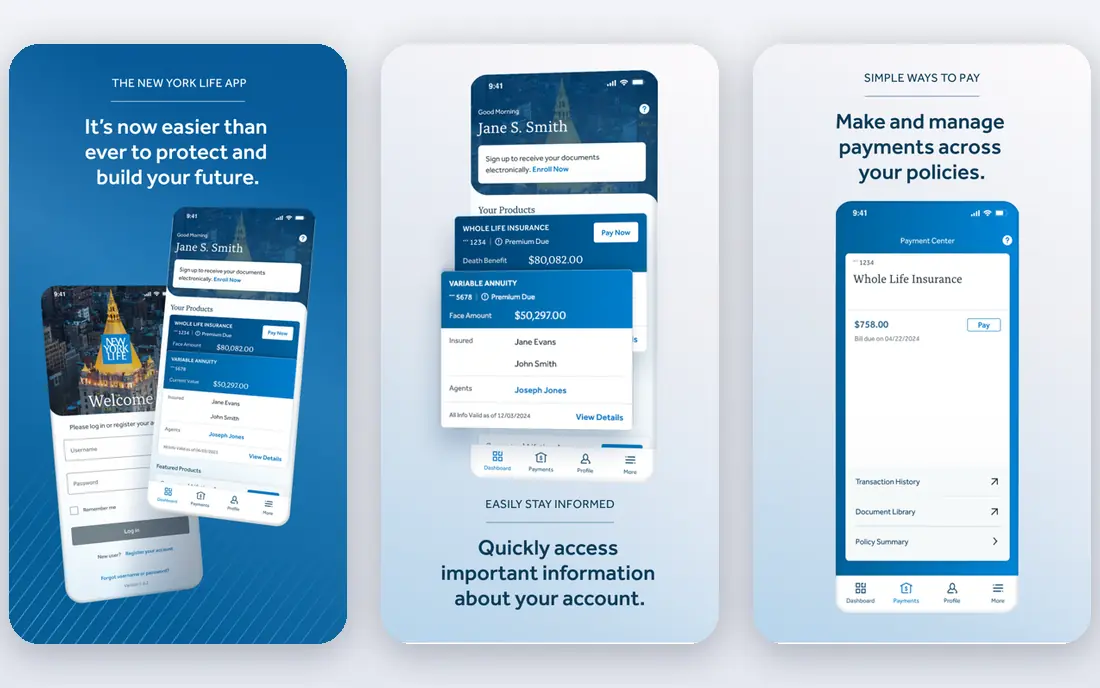
New York Life is the safest name on this list by the standard measure of financial strength, with an A++ rating from AM Best and top marks from other agencies. It is also the largest seller of income annuities in the US, and as a mutual company it is owned by policyholders rather than stockholders. Its product range covers fixed deferred, income and variable annuities, and it publishes a weekly rate comparison chart for its most popular products.
The trade-offs are process and scope. Most New York Life annuities are sold through agents, so you cannot simply buy online, and rates and terms vary by state. If your priority is a company that is very likely to be paying decades from now, New York Life is the benchmark. If you want the highest quoted rate, compare it against a slightly lower-rated rival before deciding.
- A++ AM Best rating, the highest available
- Largest income annuity seller in the US
- Mutual company owned by policyholders
- Rates vary by state and contract
- Most products sold through agents, not direct online
- Income annuity focus means fewer growth-oriented options
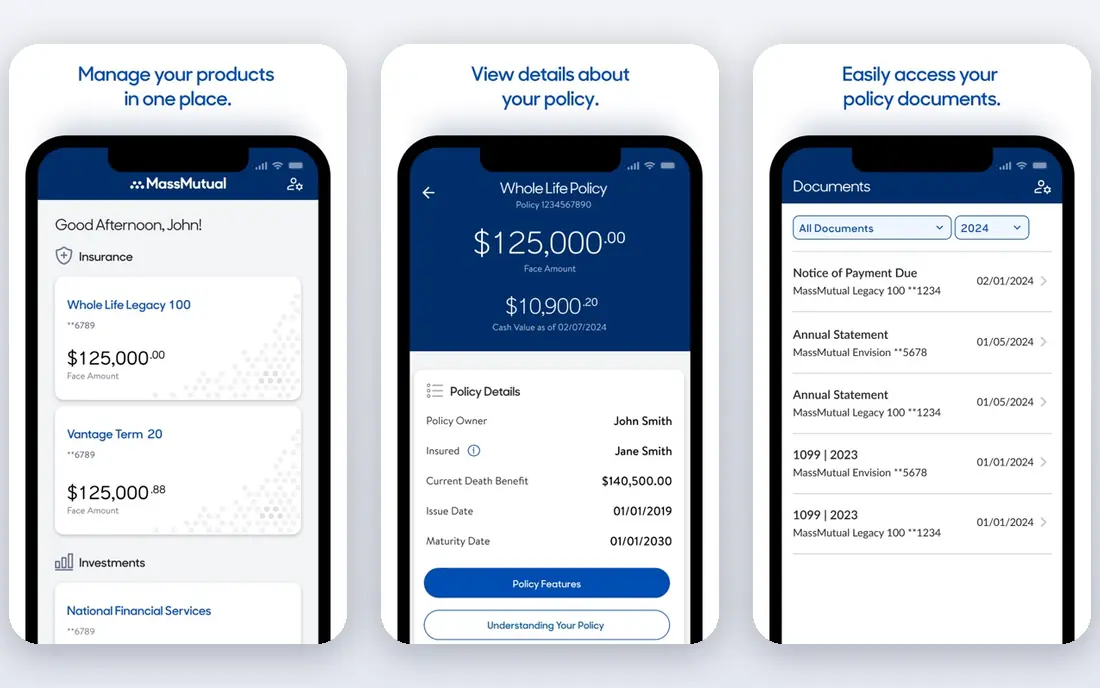
MassMutual matches New York Life on financial strength with an A++ AM Best rating, and its mutual structure means it answers to policyholders rather than shareholders. Advisors describe its fixed annuities as among the most stable available, which appeals to savers who want no surprises. Its fixed-rate annuity range includes terms from two to seven years starting at 10,000 dollars.
That stability comes at a price: MassMutual rates often sit below those of newer or lower-rated carriers. Products are sold through financial professionals, so expect an advice-led process. For conservative savers who put safety first and can accept a lower rate for it, MassMutual is a strong, calm choice.
- A++ AM Best rating
- Mutual ownership structure
- Conservative investment approach with a long operating history
- Rates are often lower than less established carriers
- Products sold through financial professionals
- Fixed annuity focus over variable growth
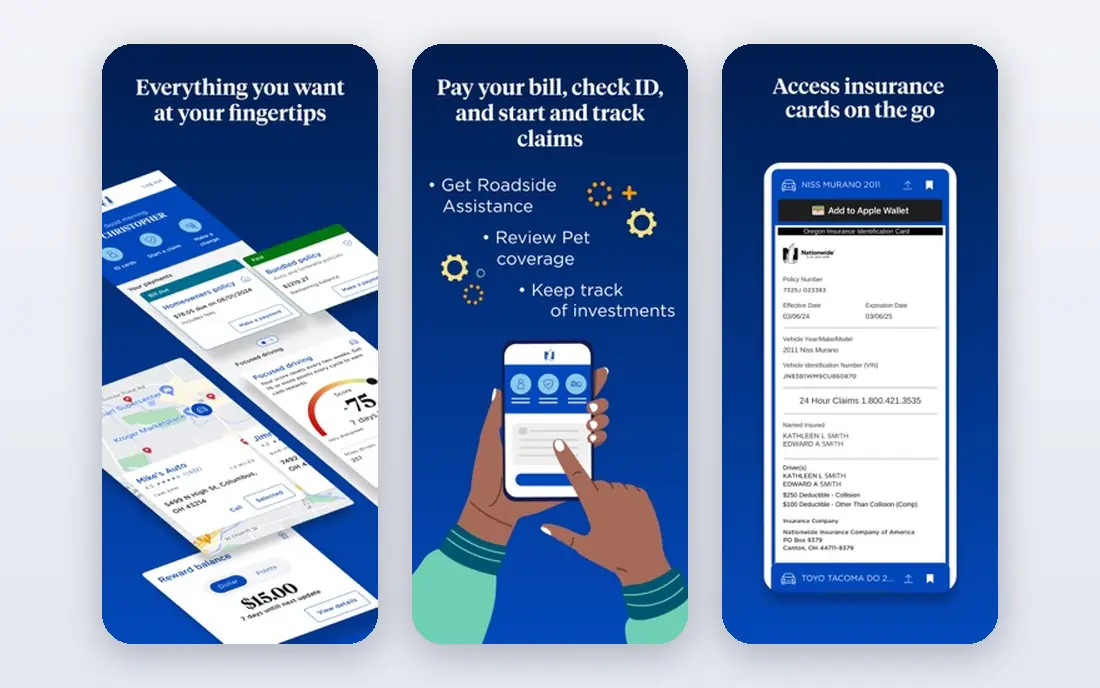
Nationwide is a major indexed annuity seller with an A+ AM Best rating, and its fixed indexed annuities are among the most popular in the US by sales. Indexed products link growth to a market index while protecting principal from market losses, and Nationwide's income riders add guaranteed lifetime income options on top. That combination suits pre-retirees who want some growth without direct market risk.
Indexed annuities are complex: caps, participation rates and spreads determine what you actually earn, and the details matter more than the headline. Nationwide sells through financial professionals or its own annuity sales line, so use that conversation to get the full illustration, not just the brochure rate. For indexed growth with income options, Nationwide belongs on every shortlist.
- A+ AM Best rating
- Strong fixed indexed annuity lineup
- Income riders with competitive features
- Products sold through financial professionals or its annuity sales line
- Contract complexity on indexed products
- Rates vary by state
Pacific Life stands out for breadth and access. It offers fixed, immediate, indexed, variable and registered index-linked annuities, and consumers can buy directly from the company rather than only through an agent. Its variable annuity range includes options with shorter surrender periods than the industry standard, which gives more flexibility to buyers who want market exposure with income guarantees.
The minimums are higher than most competitors, with fixed annuity minimums commonly around 25,000 dollars. Variable annuities also carry ongoing fees that reduce returns, so they suit buyers who understand what they are paying for. If you want choice and a direct route to purchase, Pacific Life is the most flexible major carrier here.
- A+ AM Best rating
- Fixed, immediate, indexed, variable and index-linked annuities
- Direct purchase available to consumers
- Higher minimum premiums than most rivals
- Variable annuity fees add up
- Product range can overwhelm first-time buyers
Allianz Life is the second-largest fixed indexed annuity seller in the US, with an A+ AM Best rating and a deep indexed lineup. Its products pair principal protection with index-linked growth and optional income riders, and minimum premiums on some products start as low as 5,000 dollars, which is friendlier than most rivals for smaller savers.
As with all indexed annuities, the contract terms decide the outcome: caps and participation rates limit upside, and riders cost extra. Allianz sells through financial professionals, so the advice conversation matters. For indexed annuities with a lower entry point, Allianz is a leading option.
- A+ AM Best rating
- Second-largest fixed indexed annuity seller
- Low minimum premium on some products
- Sold through financial professionals
- Indexed contract terms are complex
- Income rider costs add to the base contract
Lincoln Financial offers one of the broadest annuity lineups, from fixed and indexed to variable and registered index-linked products, with flexible payout options and legacy features for beneficiaries. That range lets buyers tailor income timing, survivor benefits and growth exposure in one relationship, which suits people planning both retirement income and estate transfer.
The complication is that Lincoln issues annuities through different insurers, so ratings and terms vary by product rather than being uniform. Read the specific contract, not the brand summary, and confirm the issuing insurer's rating. For buyers who want flexibility and legacy planning, Lincoln is worth a detailed comparison.
- Wide annuity range including indexed and variable
- Flexible payout customization
- Strong legacy and beneficiary features
- Financial strength ratings vary by issuing insurer
- Contract details vary widely by product
- Sold mainly through professionals
Prudential is a household name in retirement income with an A+ AM Best rating and a solid fixed annuity range. Its fixed products suit savers who want a guaranteed rate for a set term with tax-deferred growth, and the company's scale and history give conservative buyers confidence in long-term payment ability.
Prudential is less prominent in indexed annuities than Allianz or Nationwide, so growth-oriented buyers may find thinner options here. Minimums, rates and surrender terms vary by product and state, and sales run through professionals. For a straightforward fixed annuity from a major carrier, Prudential is a reliable shortlist entry.
- A+ AM Best rating
- Long history in retirement income
- Solid fixed annuity range
- Minimums and rates vary by product and state
- Sold through professionals
- Less prominent in indexed annuities than Allianz or Nationwide
Athene is the largest fixed indexed annuity seller in the US by recent sales, with an A+ AM Best rating and rates that often beat the mutual giants. Its indexed lineup is broad, and its scale in the indexed market means its products are widely available through independent agents and brokers.
Some conservative buyers pause at Athene's ownership by Apollo Global Management, an asset manager, rather than a traditional mutual structure. That is a preference question, not a rating problem, since the rating remains strong. If your priority is the most competitive indexed rate from a highly rated carrier, Athene deserves a quote alongside Allianz and Nationwide.
- Largest fixed indexed annuity seller by recent sales
- Competitive rates
- A+ AM Best rating
- Owned by an asset management parent, which gives some conservative buyers pause
- Sold through professionals
- Indexed terms need careful reading
USAA Life combines an A++ AM Best rating with the highest customer satisfaction scores in recent annuity studies, which is a rare combination. Its fixed annuities sell well, and its service reputation is the main reason it makes this list despite a smaller product footprint than the giants.
Eligibility is the catch: USAA sells only to military members, veterans and their eligible families. If you qualify, USAA is an excellent first call for a fixed annuity. If you do not, the other companies on this list cover the same ground.
- A++ AM Best rating
- Highest-ranked for customer satisfaction in recent annuity studies
- Strong fixed annuity sales
- Available only to military members, veterans and eligible family
- Annuities bought direct from USAA, not through brokers
- Narrower product marketing than rivals
How we picked these
We compared each company on the issuing insurer's AM Best financial strength rating, the range of annuity types offered, published minimums, how you buy, and fee or surrender disclosures. Data came from each company's official site and published rating actions, and from industry sales rankings. Where a company does not publish a figure, we say so. Ratings describe financial strength only, not the quality of any specific contract's income or growth terms.
What to check before you buy
Start with the contract type, not the company. Fixed annuities guarantee a rate for a term, indexed annuities link growth to an index with caps and participation rates, variable annuities expose you to market ups and downs, and immediate annuities start paying right away. Each suits a different goal, and mixing them up is the most common annuity mistake.
Next, read the surrender schedule and rider costs. Early withdrawals can trigger surrender charges for years, and income riders, death benefits and long-term care features each add cost. Ask for a full illustration showing what you receive in good, average and poor market years.
Finally, compare at least three quotes for the same contract type and term, and check the issuing insurer's current rating. A top-rated carrier may pay less than a lower-rated rival, so weigh safety against income honestly. This article is general information only and is not financial advice; consider speaking with a licensed financial professional before buying.
Frequently asked questions
What is the best annuity company overall?
New York Life and MassMutual lead on financial strength with A++ AM Best ratings, and New York Life is the largest income annuity seller. The best company for you depends on contract type: Allianz and Athene lead indexed annuities, while Pacific Life offers the widest product range. Compare quotes for the same contract type before deciding.
What are the best rated annuity companies?
New York Life, MassMutual and USAA Life hold A++ ratings from AM Best, the highest available. Nationwide, Pacific Life, Allianz and Prudential hold A+ ratings. Ratings measure an insurer's financial strength and claims-paying ability, not the income level of any specific annuity contract.
How much money do you need to buy an annuity?
Minimums vary by company and product. Allianz lists minimums as low as 5,000 dollars on some products, while New York Life and MassMutual commonly start at 10,000 dollars and Pacific Life fixed annuities often start around 25,000 dollars. Always confirm the minimum for the specific contract you are considering.
Are annuities safe?
Fixed and indexed annuities protect principal from market losses, but all annuities depend on the issuing insurer's ability to pay, which is why financial strength ratings matter. Annuities are not bank deposits and are not covered by federal deposit insurance, though state guaranty associations offer limited protection that varies by state.
What is the difference between fixed and indexed annuities?
A fixed annuity pays a guaranteed interest rate for a set term, similar to a certificate of deposit with tax-deferred growth. An indexed annuity links growth to a market index, with caps, participation rates or spreads limiting the gain, but your principal does not fall when the index drops. Fixed suits certainty, indexed suits savers wanting some market-linked growth.
Should I buy an annuity through an agent or direct?
Most top companies sell through financial professionals, who can compare contracts and explain riders. Pacific Life and USAA allow direct purchase. An independent agent or broker can compare several carriers at once, which usually produces better terms than buying from a single company. This is general information only and is not financial advice.
Sources we checked (9)

Online Jobs is an independent blog about careers, online work, learning new skills and the tools that help people earn. More about us.
Keep reading
All posts
Who Is the Best Company to Get Travel Insurance
Compare the best travel insurance companies, including World Nomads, Allianz Travel, SafetyWing and AXA, with coverage types, limits and who each suits.
Top AI Financial Software
Searching for top AI financial software? We compared 9 AI finance tools for AP, spend, close, forecasting and bookkeeping to help teams choose wisely.
Quicken Alternatives
Compare the best quicken alternatives for Mac, Windows, and small business owners, from Monarch Money and YNAB to Copilot, Tiller, and Banktivity in 2026.