Best 401k Investment Companies in 2026: 9 Companies Compared

Broad retirement choice · Starting price: See website
How we put this together: we compare official feature and pricing pages, app store listings, privacy policies and public user reviews. Prices change, so check the provider's site before you pay.
Key takeaways
- Fidelity, Vanguard, and Charles Schwab suit investors who want broad fund choice and low-cost index options for retirement accounts and rollovers.
- Empower, ADP, and Guideline suit employers who need a managed 401k plan with payroll integration and employee support.
- Betterment for Business, Human Interest, and ForUsAll suit smaller employers that want automation and simpler administration.
- This is not financial advice. Fees, fund menus, and plan rules vary by employer and plan, so confirm details on the provider's official site before you choose.
Quick comparison
| Name | Who it suits | Starting price | Free option | |
|---|---|---|---|---|
| Fidelity Investments | Broad retirement choice | See website | No | Visit |
 Vanguard | Low-cost index investing | See website | No | Visit |
 Charles Schwab | Flexible brokerage retirement | See website | No | Visit |
 Empower | Employer plans with planning tools | See website | No | Visit |
 Guideline | Small business 401k plans | See website | No | Visit |
 ADP Retirement Services | Payroll-linked retirement plans | See website | No | Visit |
 Betterment for Business | Automated employer plans | See website | No | Visit |
 Human Interest | Small business plans with support | See website | No | Visit |
 ForUsAll | Small business plans with guidance | See website | No | Visit |
The best 401k investment companies
A 401k provider does two jobs: it holds and invests retirement savings, and it handles the administration that keeps a plan compliant. Employees usually choose from the plan their employer offers, while employers and solo workers choose the provider. We compared official company and retirement pages and public reviews to separate large, flexible providers from simpler small-business options.
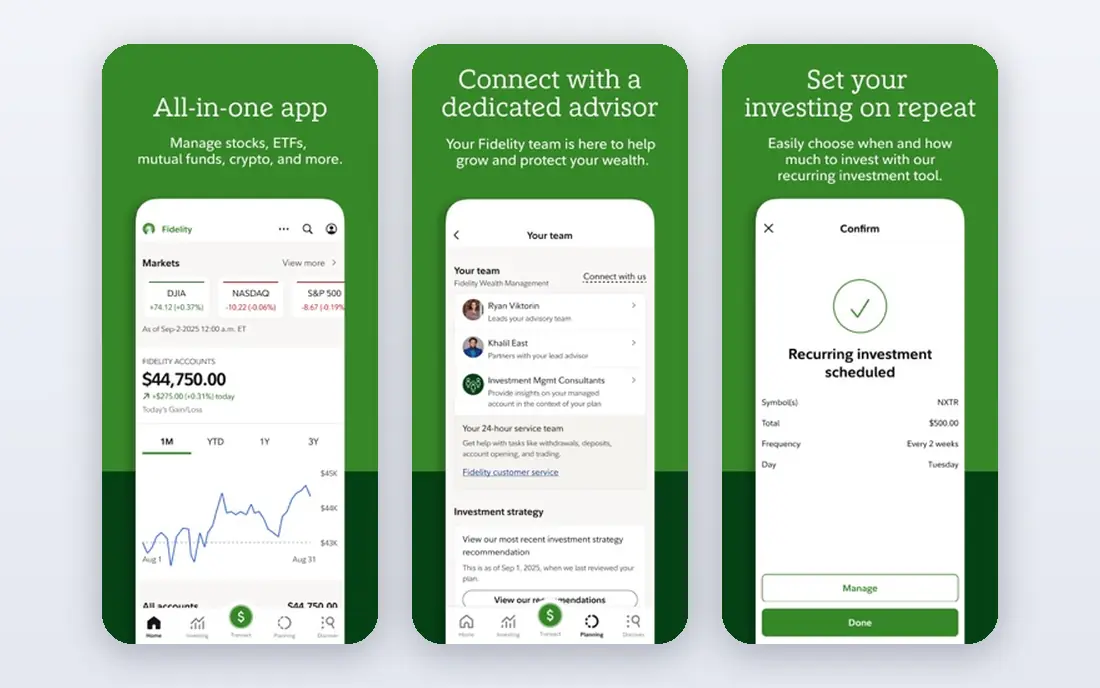
Fidelity is a strong all-round pick for retirement investing, whether you hold a rollover IRA, a solo 401k, or an employer plan administered by Fidelity. The fund menu includes low-cost index funds alongside a wide range of other funds and ETFs, and planning tools help you model contributions and retirement income. Support is widely available, which helps when you need to change investments or handle a rollover. The breadth can be a drawback for a new investor who just wants a simple default. Employer plans also vary, so the fund menu and fees in your own plan may differ from what another Fidelity customer sees. If you want choice, tools, and a provider that covers both individual and employer retirement accounts, Fidelity is a solid first look.
- Wide fund and ETF choice
- Strong planning tools
- Solo 401k option
- Choice can overwhelm new investors
- Employer plan terms vary
Vanguard built its reputation on low-cost index investing, and that focus still shapes its retirement offering. Investors who want a small set of diversified index funds and a buy-and-hold approach will find the menu straightforward. Target-date and balanced options give hands-off investors a single-fund route without needing to pick each holding. The platform is less feature-rich than Fidelity or Schwab for active trading and research, which may matter if you trade often. Some Vanguard retirement services are also administered through partners, so check who handles your specific plan. Vanguard fits investors who value low costs and simplicity over a wide trading toolkit.
- Low-cost index fund heritage
- Simple portfolio options
- Strong for buy-and-hold investors
- Platform feels simpler than rivals
- Some services are now handled by partners
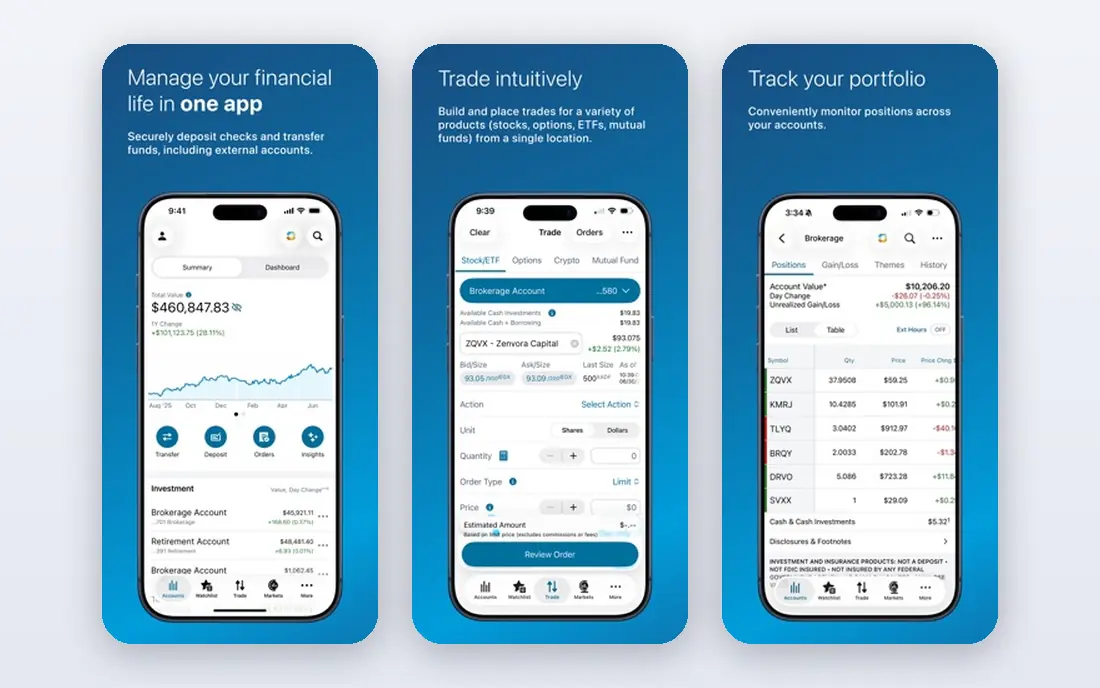
Charles Schwab suits retirement investors who want a full brokerage alongside their retirement account. You can hold a broad range of funds, ETFs, and individual securities, use research and education tools, and manage banking in the same relationship. Schwab also offers solo 401k and employer plan options, which helps small business owners who want one provider. That flexibility comes with a busier platform, and new investors may need time to find the simple retirement path inside it. As with other employer plans, fees and fund menus depend on the specific plan. Schwab fits investors who want brokerage flexibility and are comfortable with a feature-rich platform.
- Wide investment choice
- Strong research and education
- Banking alongside investing
- Interface has many features to learn
- Employer plan terms vary
Empower focuses on employer retirement plans, with administration, recordkeeping, and planning tools designed for workplaces. Employees get tools to model retirement income and track progress, while employers get support for plan design, compliance tasks, and employee communication. That workplace focus makes Empower a common choice for mid-sized and larger employers. If you are an individual looking for a solo plan, Empower is less direct than Fidelity, Vanguard, or Schwab. Pricing and fund menus are also specific to each employer plan, so you will need plan documents for exact terms. Empower fits employers that want a managed plan with planning tools employees will actually use.
- Employer plan administration
- Retirement planning tools
- Employee engagement features
- Mainly an employer plan provider
- Pricing is plan-specific
Guideline is built for small businesses that want a 401k without a heavy administration burden. The platform automates much of the setup, compliance testing, and ongoing administration, and it integrates with common payroll providers. That automation helps a small employer offer a credible retirement benefit without hiring a dedicated benefits team. The fund menu is narrower than a large brokerage, which suits hands-off investors but may frustrate employees who want wide choice. Pricing varies by employer size and plan features, so get a quote for your headcount. Guideline fits startups and small firms that want a simple, automated 401k they can run alongside payroll.
- Designed for small businesses
- Automated administration
- Payroll integrations
- Fund menu is more limited than large brokerages
- Pricing varies by plan size
ADP Retirement Services suits employers already using ADP for payroll and HR. Retirement contributions flow from payroll into the plan, which reduces manual steps and errors, and ADP handles much of the administration and compliance support. For an employer that wants payroll and retirement in one relationship, that integration is the main appeal. The trade-off is bundling. An employer that wants a fully independent fund menu or a separate provider may find the ADP route less flexible. Plan terms, fees, and fund choices vary by employer, so review plan documents carefully. ADP fits employers that value payroll integration and single-vendor administration.
- Tight payroll integration
- Employer administration support
- Wide employer reach
- Plan design can feel bundled with payroll
- Terms vary by employer
Betterment for Business brings robo-advisor automation to employer 401k plans. Employees answer questions about goals and risk tolerance, and portfolios are managed and rebalanced automatically. That hands-off approach suits employees who would otherwise leave money uninvested or struggle to pick funds, and it keeps the employer experience simple. Hands-on investors who want to pick individual funds will find less control than at a brokerage. Pricing and plan features also vary, so confirm the fee structure for your plan size. Betterment for Business fits employers whose staff want automated investing rather than a large fund menu to manage themselves.
- Automated portfolio management
- Simple employee experience
- Payroll integrations
- Less control for hands-on investors
- Pricing is plan-specific
Human Interest focuses on small and mid-sized employers that need a 401k plan with clear support. The company handles administration and compliance tasks, integrates with payroll providers, and offers guidance to employers setting up a plan for the first time. That support matters when a small business has no benefits specialist on staff. The investment menu is curated, which keeps choices simple but limits investors who want a fully open brokerage menu. Pricing depends on employer size and plan features. Human Interest fits small employers that want a guided, supported route to offering a 401k.
- Built for small and mid-sized employers
- Administration support
- Payroll integrations
- Fund choice is curated rather than open
- Pricing varies by plan
ForUsAll targets small businesses that want help setting up and running a 401k without building benefits expertise in-house. It offers administration, compliance support, and employee guidance, with payroll integrations to keep contributions flowing. For a founder or small HR team, that bundled help can make the difference between offering a plan and delaying one. As a smaller provider, ForUsAll does not match the fund breadth or brand reach of Fidelity, Vanguard, or Schwab. Plan terms and fees also vary by employer. ForUsAll fits small employers that want a guided plan and are willing to trade some investment breadth for simpler administration.
- Small business focus
- Administration and compliance help
- Employee guidance
- Smaller provider than market leaders
- Plan terms vary
How we picked these
We compared official retirement and employer plan pages, fund and service descriptions, and public reviews, and we kept only companies that actively offer 401k or retirement plan services in October 2026. We favoured providers with a clear fit for a specific buyer: individual and solo investors, large employers, or small businesses. Where fees, fund menus, or employer plan terms varied by plan, we wrote "See website" and avoided repeating a single figure as if it applied to every plan. We did not claim hands-on testing of every plan, and we did not rank providers by unverified ratings or employee counts. This is not financial advice. Retirement choices depend on your age, income, tax situation, and employer match, so review plan documents and consider regulated financial advice for your own situation.
What to check before you choose
If you are an employee, start with your own plan
Most employees cannot choose a different 401k provider; they choose investments inside the plan their employer offers. Check the employer match first, then the fund menu, fees, and default investment. Contributing enough to capture the full match is usually the first step, subject to your own finances.
If you are an employer, compare total administration cost
Look beyond the headline fee to recordkeeping, compliance testing, payroll integration, and employee support. A cheaper plan that creates admin work for your team may cost more in time than a slightly pricier managed plan. Ask for a written quote for your headcount and payroll setup.
If you are self-employed, compare solo plan features
Solo 401k plans differ on Roth options, loan options, rollover handling, and investment choice. Fidelity, Vanguard, and Schwab all offer solo routes, but features differ, so compare the plan document for each before you open an account. Check contribution rules for your tax situation as well.
Frequently asked questions
What is the best retirement company?
There is no single best retirement company for every buyer. Fidelity suits broad choice, Vanguard suits low-cost index investing, and Schwab suits flexible brokerage retirement. For employer plans, Empower, ADP, and Guideline suit different employer sizes. Match the provider to whether you are an employee, an employer, or self-employed.
What is the best 401k company for small businesses?
Guideline, Human Interest, and ForUsAll suit small businesses that want automated administration and payroll integration without a large benefits team. Betterment for Business also suits small employers whose staff prefer automated portfolios. Get a quote for your headcount, because pricing varies by employer size.
What is the best 401k company for individuals?
Individuals usually use a solo 401k or a rollover IRA rather than an employer plan. Fidelity, Vanguard, and Schwab all offer solo and rollover routes with broad fund choice. Compare Roth options, loan options, and investment menus in the plan documents before you choose.
Are 401k fees the same at every provider?
No. Fees vary by employer plan, fund choice, and provider, and the same provider can offer different terms to different employers. Check the fee disclosure for your specific plan, including fund expenses and any administration fees, rather than assuming a headline figure applies to you.
Should I choose a robo-advisor 401k?
A robo-advisor plan such as Betterment for Business suits employees who want automated portfolio management and rebalancing without picking funds. It suits hands-off investors best. If you want to pick individual funds or hold a specific portfolio, a brokerage provider with a wide fund menu may suit you better. This is not financial advice.
Sources we checked (9)
- https://www.fidelity.com/retirement-ira/401k
- https://www.vanguard.com/retirement
- https://www.schwab.com/retirement
- https://www.empower.com/retirement-plans
- https://www.guideline.com/pricing
- https://www.adp.com/what-we-offer/benefits/retirement.aspx
- https://www.betterment.com/401k
- https://humaninterest.com/pricing
- https://www.forusall.com/pricing

Online Jobs is an independent blog about careers, online work, learning new skills and the tools that help people earn. More about us.
Keep reading
All posts
Top AI Financial Software
Searching for top AI financial software? We compared 9 AI finance tools for AP, spend, close, forecasting and bookkeeping to help teams choose wisely.

Quicken Alternatives
Compare the best quicken alternatives for Mac, Windows, and small business owners, from Monarch Money and YNAB to Copilot, Tiller, and Banktivity in 2026.

QuickBooks Online Alternatives
Looking for quickbooks online alternatives? We compared 8 accounting tools on invoicing, bank feeds, payroll, pricing and fit for small businesses today.