Best Loan Origination Software in 2026: 8 Systems Compared

Mortgage lending at scale · Starting price: See website
How we put this together: we compare official feature and pricing pages, app store listings, privacy policies and public user reviews. Prices change, so check the provider's site before you pay.
Key takeaways
- Encompass suits mortgage lenders that need a widely used, full mortgage pipeline.
- Blend suits lenders that want a cleaner borrower application experience on top of existing systems.
- MeridianLink suits credit unions and community banks running consumer and mortgage lending together.
- nCino suits banks already committed to Salesforce for wider banking workflows.
- Most enterprise loan systems are priced by quote, so demos and total implementation cost matter more than a headline price.
Quick comparison
| Name | Who it suits | Starting price | Free option | |
|---|---|---|---|---|
| Encompass by ICE | Mortgage lending at scale | See website | No | Visit |
 Blend | Borrower application experience | See website | No | Visit |
 MeridianLink | Credit unions and community banks | See website | No | Visit |
 nCino | Salesforce-based banks | See website | No | Visit |
 LendingPad | Cloud mortgage origination | $50 per user per month | Free trial | Visit |
 Calyx Point | Small mortgage brokers | See website | No | Visit |
 Floify | Mortgage document collection | See website | Free trial | Visit |
 Finastra Loan IQ | Large commercial and syndicated lending | See website | No | Visit |
The best loan origination software
Loan origination software takes a loan from application to closing, with documents, compliance checks, pricing and pipeline tracking in one place. This guide covers software for lenders, not loan advice for borrowers, and pricing for most enterprise systems is set by quote.
Encompass is one of the most widely used mortgage loan origination systems in the United States, and that scale is its main advantage. It covers application intake, processing, underwriting support, closing and secondary market steps, with a large set of integrations for credit, pricing, documents and eClosing. Lenders that need to handle high volume across many loan types will find fewer gaps than in a smaller system.
The trade-off is complexity and cost transparency. Implementation, training and configuration take time, and pricing is set through sales, so two lenders may pay very different amounts for similar use. Smaller brokers should ask for total first-year cost, including implementation and integrations, before comparing Encompass with a lighter cloud system.
- Broad mortgage workflow
- Large lender and partner network
- Deep compliance and closing tools
- Implementation can be long
- Pricing is quote based and can be hard to compare
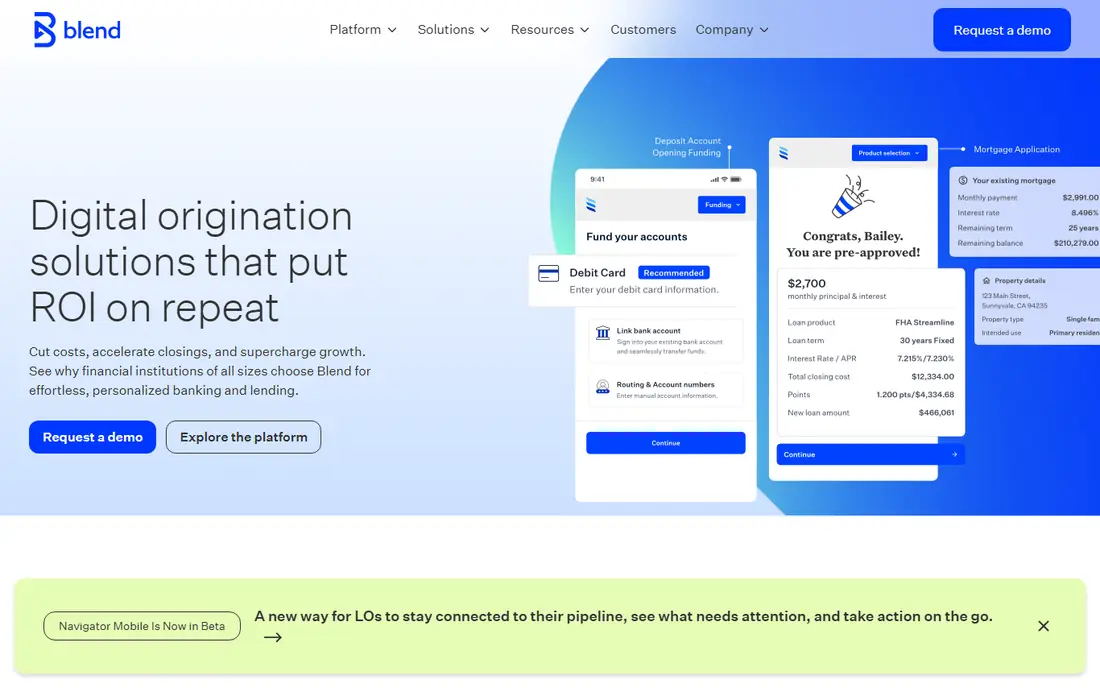
Blend focuses on the front end of lending: the application a borrower actually sees. Applicants can complete forms, upload documents and track progress online, which reduces back-and-forth emails and missing paperwork. For lenders, that cleaner intake can shorten cycle times even when the back-office system stays the same.
Blend is best viewed as a borrower experience layer rather than a single system for every lending job. Lenders should check how it connects to their current loan origination system, core platform and document tools, and whether the features they need require additional modules. Pricing is quoted, so a demo with real loan scenarios is the fairest test.
- Clean digital application
- Strong document collection
- Works with existing systems
- Not a full replacement for every back-office workflow
- Pricing is quote based
MeridianLink serves credit unions and community banks that lend across consumer, auto, card and mortgage products. Its consumer system supports online applications, decisioning and cross-selling, while its mortgage system adds pricing, eClosing and broker portals. That breadth suits institutions that want one vendor relationship across several loan types.
The catch is scope. With many modules and configuration options, implementation needs a clear owner on the lender side and a realistic timeline. Pricing varies by module and size, so buyers should compare the full set of modules they will actually use, not just the entry product. For a credit union replacing a consumer system, MeridianLink is a natural shortlist entry.
- Consumer and mortgage options
- Cross-sell tools
- Many core and partner integrations
- Configuration can be heavy
- Module pricing needs careful review
nCino runs on Salesforce, which is a major advantage for banks that already use that platform for customer and workflow management. It covers commercial, consumer and mortgage lending with workflow, document and approval tools, and it gives managers a clear view of pipeline, exceptions and audit trails. Banks that want lending inside a wider Salesforce strategy will find the fit natural.
For lenders without Salesforce, nCino is a larger commitment, since licensing, administration and training extend beyond the lending team. Single-product mortgage brokers will usually find a mortgage-focused system simpler and cheaper. nCino fits best when the bank already plans to standardize on Salesforce.
- Built on Salesforce
- Strong commercial and consumer workflows
- Audit and reporting depth
- Salesforce commitment adds cost and complexity
- Overkill for a single-product lender
LendingPad is a cloud mortgage origination system aimed at lenders and brokers that want a modern, browser-based pipeline without managing servers. It covers application intake, processing, documents and closing steps, with pricing published from about $50 per user per month in recent listings. That transparency makes early budgeting easier than with quote-only vendors.
The honest limit is scale of ecosystem. Its partner and integration network is smaller than the largest mortgage systems, so lenders with unusual investors, products or compliance tools should verify each integration before switching. For a growing broker or mid-size lender that values a clean cloud workflow, LendingPad is a practical choice.
- Cloud based with no local install
- Modern interface
- Clear entry pricing
- Smaller partner network than Encompass
- Advanced needs may require add-ons
Calyx Point has served mortgage brokers for many years, and its strength is familiarity. Loan officers who have used it before will recognize the forms, document handling and pipeline views, which shortens training. It suits small broker shops that want a known mortgage workflow without a large enterprise rollout.
Its weakness is age. The interface and cloud options do not feel as modern as newer systems, and teams that work remotely or on mobile should test those workflows carefully. Pricing is not published as a single list price, so brokers should request a quote that includes support and updates. For a small shop that values stability over novelty, Point remains a credible option.
- Long history with brokers
- Familiar loan forms and documents
- Desktop option
- Interface feels dated next to cloud rivals
- Cloud and mobile options need review
Floify focuses on the part of mortgage lending that causes the most delays: collecting documents from borrowers. Borrowers receive clear requests, upload files through a portal, and get reminders when items are missing. Loan teams spend less time chasing paperwork and more time moving files forward.
Floify is best used alongside a loan origination system, not as a replacement for one, so buyers should confirm how it connects to their current system and whether documents flow both ways. Pricing is not published as a simple list, and a trial with a real loan file is the best way to judge time saved. For teams drowning in document chasing, it can be a useful addition.
- Strong borrower document portal
- Automated requests and reminders
- Integrates with loan systems
- Not a full loan origination system on its own
- Value depends on integration quality
Finastra Loan IQ is built for large banks handling commercial, corporate and syndicated loans, where a single loan may involve many participants, complex terms and long servicing periods. It covers origination, booking, servicing and reporting in one lifecycle, with controls suited to large, regulated portfolios.
That depth comes with enterprise scale. Implementation, cost and staffing are far beyond what a small lender needs, and it is not a fit for simple consumer or mortgage origination. For a large bank with syndicated lending, Loan IQ belongs on the shortlist. For everyone else, a consumer or mortgage-focused system will be faster and cheaper.
- Deep commercial loan lifecycle
- Syndicated loan support
- Strong servicing and reporting
- Enterprise scale and cost
- Too heavy for consumer or small mortgage lending
How we picked these
We compared vendor product pages, lending industry comparisons and pricing listings, and kept only systems that are live in October 2026 and truly handle loan origination. We covered mortgage, consumer and commercial lending, and we mixed widely used enterprise systems with smaller broker and document tools. Where a vendor does not publish a price, we wrote See website rather than repeating a third-party estimate as fact.
How to choose the right system
Start with loan type, not features. A mortgage broker, a credit union and a syndicated lender need different systems, and a tool that excels in one area can be a poor fit in another. Next, map your current stack: core banking system, document tools, credit vendors, pricing engines and eClosing providers. The system with the cleanest integrations will usually beat the system with the longest feature list.
Ask for a demo using your own loan scenarios, including an exception case and a document problem, not just a clean application. Confirm implementation time, training, support hours and first-year total cost in writing. Finally, check compliance and audit tools, since a system that makes reporting easy will save more time than one that only looks fast in the demo.
Frequently asked questions
What is the best loan origination software?
There is no single best system for every lender. Encompass suits large mortgage volume, MeridianLink suits credit unions, nCino suits Salesforce-based banks, and LendingPad suits cloud-based mortgage teams. The best choice follows loan type, current systems and team size.
What is the best mortgage loan origination software?
For mortgage lending at scale, Encompass is the most widely used choice, while LendingPad and Calyx Point suit smaller broker teams. Blend and Floify add strong borrower and document experiences on top of a core system. Compare integration depth and total implementation cost, not just monthly price.
How much does loan origination software cost?
Most enterprise systems are priced by quote, based on volume, users and modules, so a single public price rarely exists. LendingPad lists entry pricing from about $50 per user per month in recent listings. Always request a written first-year total that includes implementation, training and integrations.
Is loan origination software the same as a CRM?
No. A CRM tracks relationships and sales activity, while a loan origination system moves a loan from application through underwriting to closing, with documents, compliance checks and pipeline controls. Some systems include CRM features, but the core jobs are different.
Can a small broker use enterprise loan software?
Yes, but it is often wasteful. Small brokers usually do better with a broker-focused system or a cloud system with clear per-user pricing, plus a document tool if needed. Enterprise systems pay off when volume, product range or regulatory reporting justify the implementation effort.
Sources we checked (8)

Online Jobs is an independent blog about careers, online work, learning new skills and the tools that help people earn. More about us.
Keep reading
All posts
Wise Alternatives
Compare the best Wise alternatives in 2026, from Revolut and Remitly to OFX and Xe, with fees, speed, cash pickup options, and honest trade-offs today.
Top AI Financial Software
Searching for top AI financial software? We compared 9 AI finance tools for AP, spend, close, forecasting and bookkeeping to help teams choose wisely.
Quicken Alternatives
Compare the best quicken alternatives for Mac, Windows, and small business owners, from Monarch Money and YNAB to Copilot, Tiller, and Banktivity in 2026.